



S&P 500 technical analysis: Testing broken trend
The S&P 500 futures were edging higher early Thursday, mirroring gains across European markets and extending Wednesday’s late-session rally on Wall Street. The buying in the previous session was led by heavyweight technology stocks, with sentiment buoyed by the perception that the Federal Reserve may be edging closer to a September rate cut.
Share this:
- S&P 500 technical analysis: Bulls holding the line, but price action shows hesitation near resistance
- Macro backdrop: Bond yields retreat as September rate cut bets grow
- Key zones: 6,460/70 is pivotal – breakout could unlock 6,500–6,600 range.
The S&P 500 futures were edging higher early Thursday, mirroring gains across European markets and extending Wednesday’s late-session rally on Wall Street. The buying in the previous session was led by heavyweight technology stocks, with sentiment buoyed by the perception that the Federal Reserve may be edging closer to a September rate cut. The JOLTS job openings data offered further evidence of cooling in the labour market, reinforcing hopes of looser policy. Investors now turn their attention to a busy run of employment data: today’s ADP private payrolls, weekly jobless claims, and ISM Services employment index should help refine expectations for Friday’s non-farm payrolls report – the week’s main event. Ahead of all that, our S&P 500 technical analysis points to caution, especially as September tends to be a not-so-great month for stocks.
Bond market still in the driving seat
The real catalyst for this week’s swings has been the bond market. Tuesday’s sell-off in equities was triggered by a rout in long-dated bonds, which sent yields higher and unnerved risk assets. The turnaround came on Wednesday as bonds staged a recovery, driving the 10-year Treasury yield back down to 4.19% by Thursday morning.
This stabilisation in yields has helped risk appetite return, but it is worth keeping in mind that valuations remain elevated and fiscal concerns continue to linger. If upcoming data hints at stagflationary pressures – weaker growth with sticky inflation – yields could climb again, putting pressure back on equities. Traders would be wise to keep one eye firmly on Treasuries while navigating this week’s macro releases.
S&P 500 technical analysis – Watching broken trend line
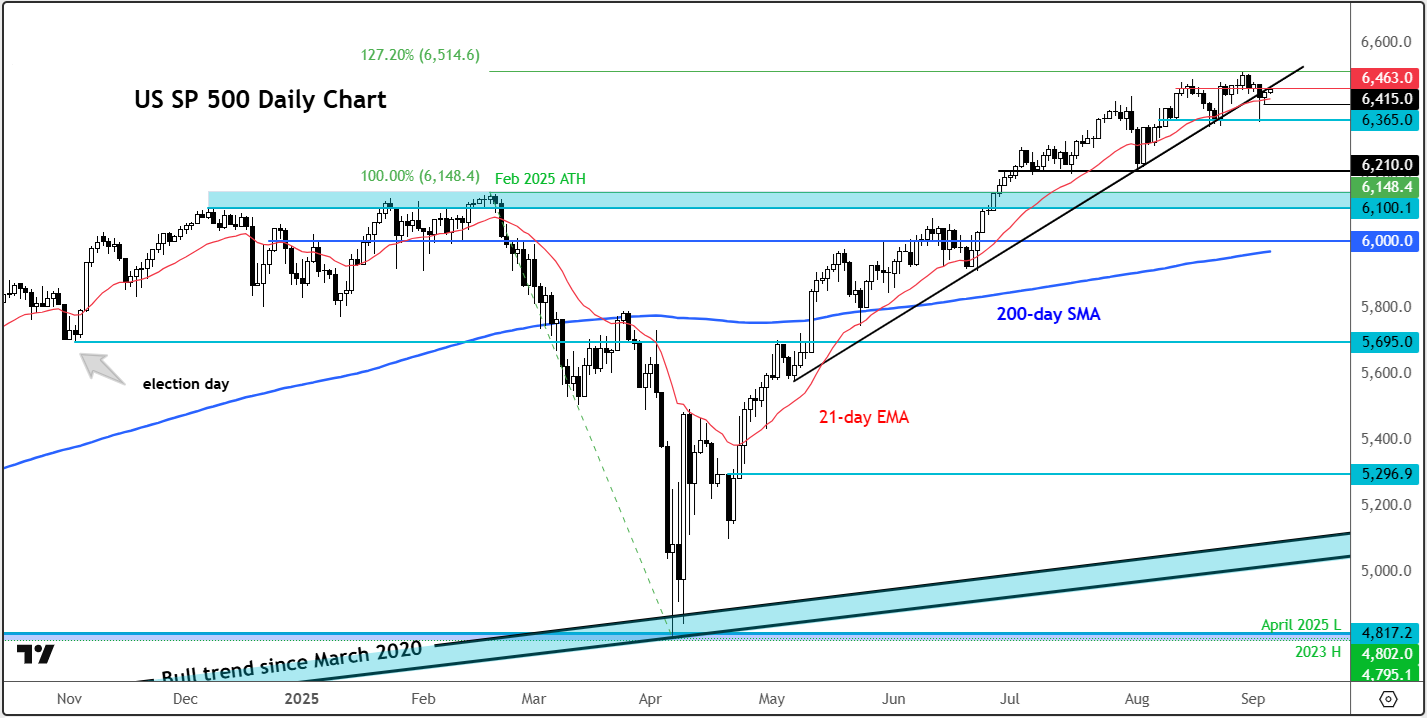
From a technical standpoint, the S&P 500 technical analysis picture remains broadly bullish, but the recent loss of momentum cannot be ignored. Tuesday’s decline saw our US SP 500 index, which is derived from the underlying S&P 500 futures, break its short-term trendline, which led to follow-through selling before dip-buyers stepped in at 6,365ish – a level that has acted as a reliable support zone in recent weeks.
Price action has since rebounded to the 6,460/70 area, which now represents a critical pivot. This area is not just resistance but also marks the underside of the broken trendline. A decisive daily close above here would be technically significant, opening the door for a retest of 6,500 and potentially a new leg higher.
The daily chart also reveals an inside bar pattern, reflecting market indecision after Wednesday’s bounce. Inside bars near resistance often precede sharp moves – either a breakout higher or a reversal lower. Should the index fail to clear 6,460/70 and drop back under Tuesday’s high at 6,453, we could see a quick flush towards 6,415 and potentially a deeper move towards 6,365 to test liquidity below that support.
But should the bulls reclaim 6,460/70 area, the path of least resistance will remain to the upside. Beyond 6,500, there is little overhead supply until the round number of 6,600, with intermediate targets including 6,515 – the 127.2% Fibonacci extension of the February–April downswing.
Short-term risk, long-term structure
While a shakeout cannot be ruled out in the near term, the longer-term structure remains constructive. A measured pullback towards 6,300 or even the 6,100–6,150 zone (the old record high area) would still be considered a healthy retest within a broader uptrend. These levels could attract fresh buyers if the market sees them as value areas.
In short, the bulls remain in control, but they must prove their strength at this key juncture. The next couple of sessions – particularly Friday’s payrolls – could well set the tone for September trading. For now, staying nimble seems the most prudent approach, especially as September is historically one of the worst months for the markets.
-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R
Related tags:


Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
British Pound Technical Outlook: GBP/USD Rebound Challenges September Downtrend 9 30 2026
Sterling has rallied sharply from key support, with GBP/USD at an inflection point that could determine whether a larger recovery is underway.

S&P 500 Forecast: SPX rises after cooler-than-expected inflation data
U.S. stocks are rising and Treasury yields are falling after data showed that inflation increased at a cooler pace than expected, while U.S. consumer spending rose again in August.


EUR/USD forecast: Eurozone stagflation risks mount as dollar holds firm ahead of data
The dollar was bouncing back at the time of writing, after it had eased overnight on the back of some weaker-than-expected economic data yesterday which had prompted markets to scale back expectations of an October Fed rate hike. However, with more significant US data due today and Friday, and with oil prices continuing to remain elevated, the dollar’s broader direction remains bullish.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.