



Asia Morning Sep 23
Twitter, Amazon.com and Ralph Lauren were top gainers...
Share this:

On Tuesday, U.S. stocks rebounded. The Dow Jones Industrial Average rose 140 points (+0.52%) to 27288, the S&P 500 climbed 34 points (+1.05%) to 3315, and the Nasdaq 100 jumped 206 points (+1.88%) to 11186.
S&P 500 Index: Daily Chart
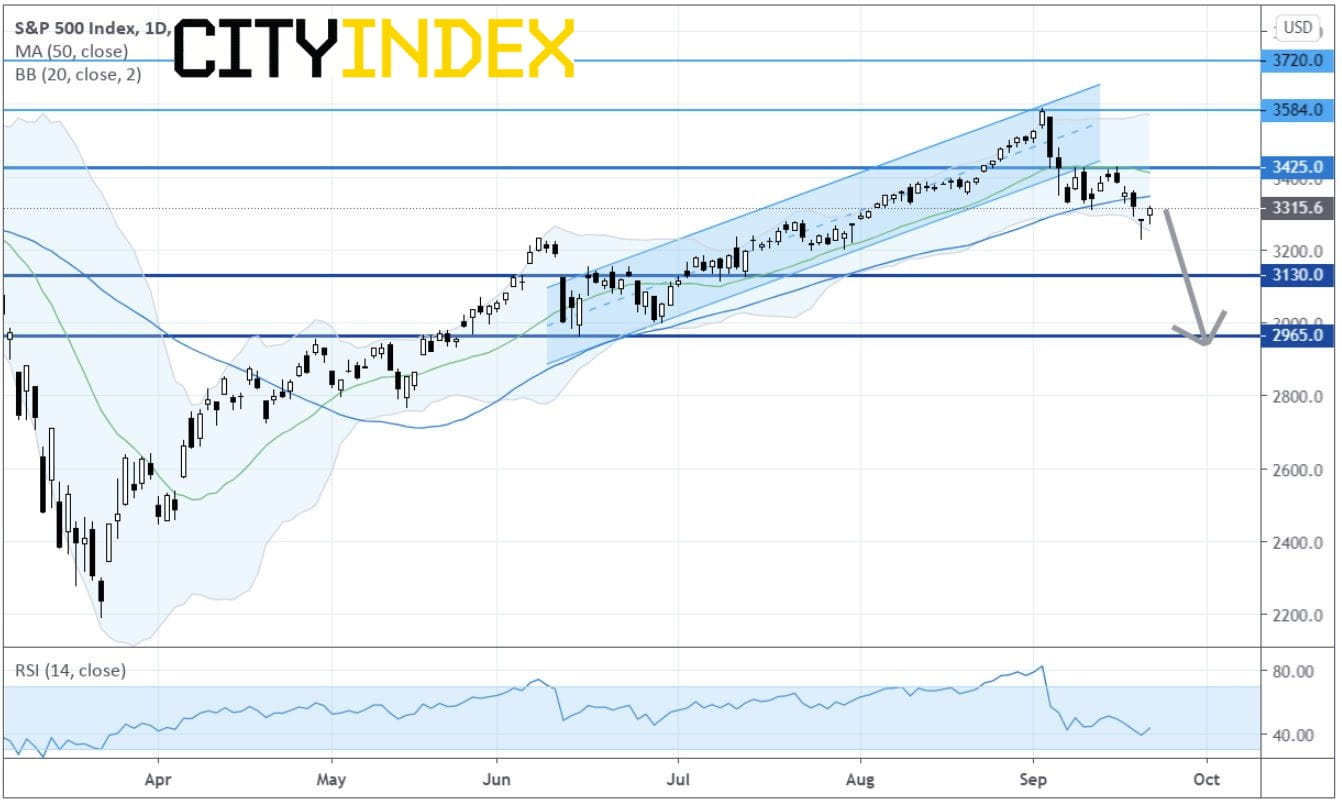
Sources: GAIN Capital, TradingView
In his prepared testimony to a congressional panel, Federal Reserve Chairman Jerome Powell said: "Many economic indicators show marked improvement, (...) Both employment and overall economic activity, however, remain well below their pre-pandemic levels, and the path ahead continues to be highly uncertain."
Retailing (+3.64%), Consumer Durables & Apparel (+2.57%) and Media (+2.24%) sectors performed the best. Twitter (TWTR +6.87%), Amazon.com (AMZN +5.56%) and Ralph Lauren (RL +4.76%) were top gainers. Meanwhile, Tesla (TSLA) fell 5.60% and Gamestop (GME) soared 20.69%.
Approximately 56% (61% in the prior session) of stocks in the S&P 500 Index were trading above their 200-day moving average and 14% (41% in the prior session) were trading above their 20-day moving average.
European stocks closed mixed. The Stoxx Europe 600 Index rebounded 0.20%, Germany's DAX 30 rose 0.41% and the U.K.'s FTSE 100 was up 0.43%, while France's CAC 40 declined 0.40%.
The benchmark U.S. 10-year Treasury yield was little changed at 0.663%.
Spot gold was down for a second session as it fell $12 to $1,900 an ounce.
U.S. WTI crude oil futures (October) advanced 0.7% to $39.60 a barrel.
On the forex front, the ICE U.S. Dollar Index rose 0.4% on day to 93.97, the highest level since late July. Chicago Federal Reserve President Charles Evans said the Fed could start raising rates before inflation averages 2%.
EUR/USD dropped 0.5% to 1.1708, posting a three-day decline. Official data showed that the eurozone's Consumer Confidence Index improved to -13.9 in September (-14.7 expected) from -14.7 in August. Later today, research firm Markit will post the eurozone's Manufacturing PMI (51.9 expected) and Services PMI (50.6 expected) for September.
GBP/USD slid 0.6% to 1.2734, the lowest level since July 23. Bank of England Governor Andrew Bailey said the central bank has "looked hard" at cutting interest rates and while negative rates remain an option, the markets had read too much into the central bank's statement last week. Meanwhile, the Markit U.K. Manufacturing PMI (54.0 expected) and Services PMI (56.0 expected) for September will be released later today.
USD/JPY advanced 0.3% to 105.00.
NZD/USD lost 0.5% to 0.6630. The Reserve Bank of New Zealand is expected to keep its benchmark rate at 0.25% unchanged later in the day.
Other Commodity-linked currencies were mixed against the greenback. AUD/USD sank 0.8% to 0.7169, while USD/CAD was little changed at 1.3305.
S&P 500 Index: Daily Chart
Sources: GAIN Capital, TradingView
In his prepared testimony to a congressional panel, Federal Reserve Chairman Jerome Powell said: "Many economic indicators show marked improvement, (...) Both employment and overall economic activity, however, remain well below their pre-pandemic levels, and the path ahead continues to be highly uncertain."
Retailing (+3.64%), Consumer Durables & Apparel (+2.57%) and Media (+2.24%) sectors performed the best. Twitter (TWTR +6.87%), Amazon.com (AMZN +5.56%) and Ralph Lauren (RL +4.76%) were top gainers. Meanwhile, Tesla (TSLA) fell 5.60% and Gamestop (GME) soared 20.69%.
Approximately 56% (61% in the prior session) of stocks in the S&P 500 Index were trading above their 200-day moving average and 14% (41% in the prior session) were trading above their 20-day moving average.
European stocks closed mixed. The Stoxx Europe 600 Index rebounded 0.20%, Germany's DAX 30 rose 0.41% and the U.K.'s FTSE 100 was up 0.43%, while France's CAC 40 declined 0.40%.
The benchmark U.S. 10-year Treasury yield was little changed at 0.663%.
Spot gold was down for a second session as it fell $12 to $1,900 an ounce.
U.S. WTI crude oil futures (October) advanced 0.7% to $39.60 a barrel.
On the forex front, the ICE U.S. Dollar Index rose 0.4% on day to 93.97, the highest level since late July. Chicago Federal Reserve President Charles Evans said the Fed could start raising rates before inflation averages 2%.
EUR/USD dropped 0.5% to 1.1708, posting a three-day decline. Official data showed that the eurozone's Consumer Confidence Index improved to -13.9 in September (-14.7 expected) from -14.7 in August. Later today, research firm Markit will post the eurozone's Manufacturing PMI (51.9 expected) and Services PMI (50.6 expected) for September.
GBP/USD slid 0.6% to 1.2734, the lowest level since July 23. Bank of England Governor Andrew Bailey said the central bank has "looked hard" at cutting interest rates and while negative rates remain an option, the markets had read too much into the central bank's statement last week. Meanwhile, the Markit U.K. Manufacturing PMI (54.0 expected) and Services PMI (56.0 expected) for September will be released later today.
USD/JPY advanced 0.3% to 105.00.
NZD/USD lost 0.5% to 0.6630. The Reserve Bank of New Zealand is expected to keep its benchmark rate at 0.25% unchanged later in the day.
Other Commodity-linked currencies were mixed against the greenback. AUD/USD sank 0.8% to 0.7169, while USD/CAD was little changed at 1.3305.
On Tuesday, U.S. stocks rebounded. The Dow Jones Industrial Average rose 140 points (+0.52%) to 27288, the S&P 500 climbed 34 points (+1.05%) to 3315, and the Nasdaq 100 jumped 206 points (+1.88%) to 11186.
S&P 500 Index: Daily Chart
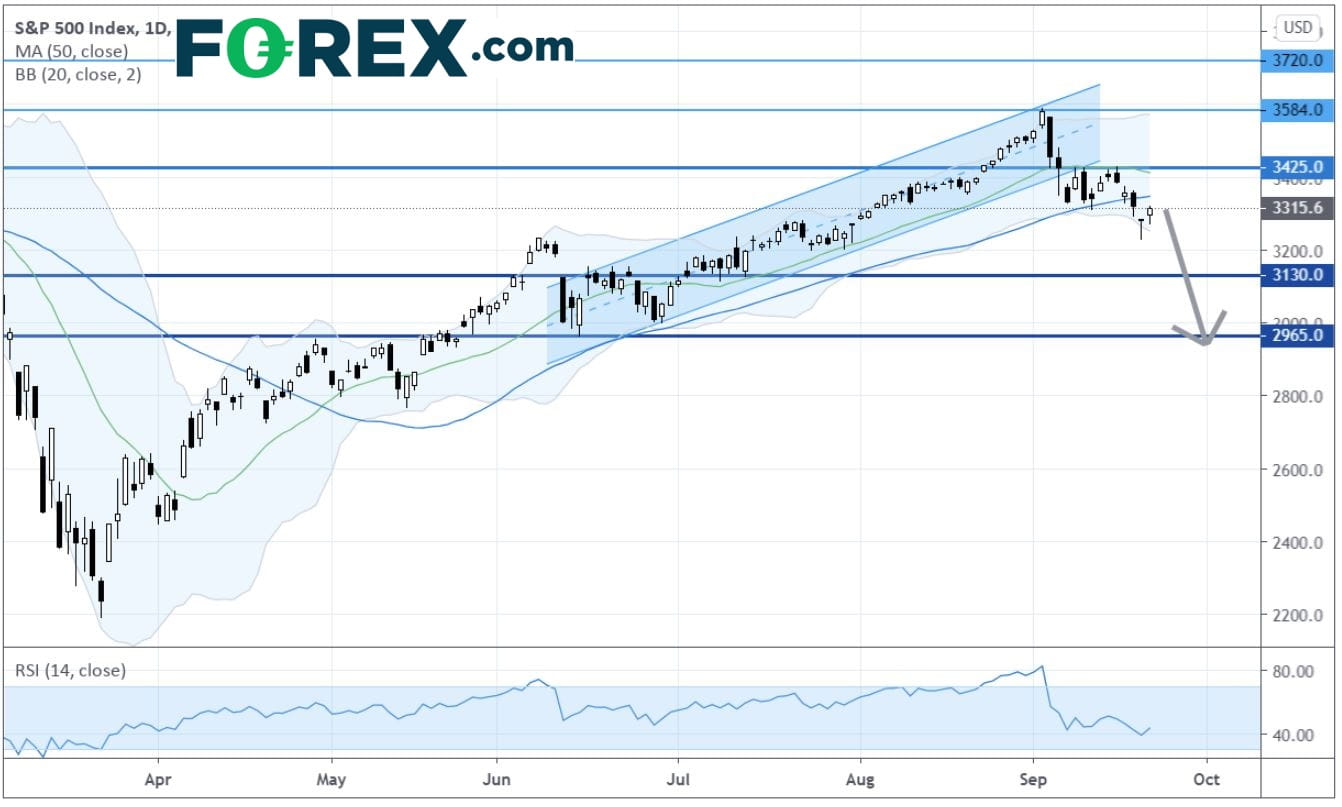
Sources: GAIN Capital, TradingView
In his prepared testimony to a congressional panel, Federal Reserve Chairman Jerome Powell said: "Many economic indicators show marked improvement, (...) Both employment and overall economic activity, however, remain well below their pre-pandemic levels, and the path ahead continues to be highly uncertain."
Retailing (+3.64%), Consumer Durables & Apparel (+2.57%) and Media (+2.24%) sectors performed the best. Twitter (TWTR +6.87%), Amazon.com (AMZN +5.56%) and Ralph Lauren (RL +4.76%) were top gainers. Meanwhile, Tesla (TSLA) fell 5.60% and Gamestop (GME) soared 20.69%.
Approximately 56% (61% in the prior session) of stocks in the S&P 500 Index were trading above their 200-day moving average and 14% (41% in the prior session) were trading above their 20-day moving average.
European stocks closed mixed. The Stoxx Europe 600 Index rebounded 0.20%, Germany's DAX 30 rose 0.41% and the U.K.'s FTSE 100 was up 0.43%, while France's CAC 40 declined 0.40%.
The benchmark U.S. 10-year Treasury yield was little changed at 0.663%.
Spot gold was down for a second session as it fell $12 to $1,900 an ounce.
U.S. WTI crude oil futures (October) advanced 0.7% to $39.60 a barrel.
On the forex front, the ICE U.S. Dollar Index rose 0.4% on day to 93.97, the highest level since late July. Chicago Federal Reserve President Charles Evans said the Fed could start raising rates before inflation averages 2%.
EUR/USD dropped 0.5% to 1.1708, posting a three-day decline. Official data showed that the eurozone's Consumer Confidence Index improved to -13.9 in September (-14.7 expected) from -14.7 in August. Later today, research firm Markit will post the eurozone's Manufacturing PMI (51.9 expected) and Services PMI (50.6 expected) for September.
GBP/USD slid 0.6% to 1.2734, the lowest level since July 23. Bank of England Governor Andrew Bailey said the central bank has "looked hard" at cutting interest rates and while negative rates remain an option, the markets had read too much into the central bank's statement last week. Meanwhile, the Markit U.K. Manufacturing PMI (54.0 expected) and Services PMI (56.0 expected) for September will be released later today.
USD/JPY advanced 0.3% to 105.00.
NZD/USD lost 0.5% to 0.6630. The Reserve Bank of New Zealand is expected to keep its benchmark rate at 0.25% unchanged later in the day.
Other Commodity-linked currencies were mixed against the greenback. AUD/USD sank 0.8% to 0.7169, while USD/CAD was little changed at 1.3305.
S&P 500 Index: Daily Chart
Sources: GAIN Capital, TradingView
In his prepared testimony to a congressional panel, Federal Reserve Chairman Jerome Powell said: "Many economic indicators show marked improvement, (...) Both employment and overall economic activity, however, remain well below their pre-pandemic levels, and the path ahead continues to be highly uncertain."
Retailing (+3.64%), Consumer Durables & Apparel (+2.57%) and Media (+2.24%) sectors performed the best. Twitter (TWTR +6.87%), Amazon.com (AMZN +5.56%) and Ralph Lauren (RL +4.76%) were top gainers. Meanwhile, Tesla (TSLA) fell 5.60% and Gamestop (GME) soared 20.69%.
Approximately 56% (61% in the prior session) of stocks in the S&P 500 Index were trading above their 200-day moving average and 14% (41% in the prior session) were trading above their 20-day moving average.
European stocks closed mixed. The Stoxx Europe 600 Index rebounded 0.20%, Germany's DAX 30 rose 0.41% and the U.K.'s FTSE 100 was up 0.43%, while France's CAC 40 declined 0.40%.
The benchmark U.S. 10-year Treasury yield was little changed at 0.663%.
Spot gold was down for a second session as it fell $12 to $1,900 an ounce.
U.S. WTI crude oil futures (October) advanced 0.7% to $39.60 a barrel.
On the forex front, the ICE U.S. Dollar Index rose 0.4% on day to 93.97, the highest level since late July. Chicago Federal Reserve President Charles Evans said the Fed could start raising rates before inflation averages 2%.
EUR/USD dropped 0.5% to 1.1708, posting a three-day decline. Official data showed that the eurozone's Consumer Confidence Index improved to -13.9 in September (-14.7 expected) from -14.7 in August. Later today, research firm Markit will post the eurozone's Manufacturing PMI (51.9 expected) and Services PMI (50.6 expected) for September.
GBP/USD slid 0.6% to 1.2734, the lowest level since July 23. Bank of England Governor Andrew Bailey said the central bank has "looked hard" at cutting interest rates and while negative rates remain an option, the markets had read too much into the central bank's statement last week. Meanwhile, the Markit U.K. Manufacturing PMI (54.0 expected) and Services PMI (56.0 expected) for September will be released later today.
USD/JPY advanced 0.3% to 105.00.
NZD/USD lost 0.5% to 0.6630. The Reserve Bank of New Zealand is expected to keep its benchmark rate at 0.25% unchanged later in the day.
Other Commodity-linked currencies were mixed against the greenback. AUD/USD sank 0.8% to 0.7169, while USD/CAD was little changed at 1.3305.
Related tags:




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.