




Week Ahead Now that US China Trade Deal is Signed Whats Next
The markets next week are likely to focus once again on macro-economic data.
Share this:

Aside from the ceremonial signing of “Phase One” of the US-China Trade Deal, this past week was seemingly uneventful. The US Senate passed the United State- Mexico-Canada Agreement (USMCA) and it is currently waiting President Trump’s signature. Things between the US and Iran in the Middle East have calmed down, and stocks have continued their climb to all time highs on the back of better bank earnings.
The World Economic Forum’s annual meeting will be held next week in Davos, beginning on Wednesday. Many world leaders and large companies attend this event, including large oil companies, and it may be good for some potentially market moving soundbites.
With many of the political and geo-political events on the sidelines (for now), the markets next week are likely to begin focusing once again on central banks, macro-economic data and earnings.
There are three Central Bank meetings next week, which include the Bank of Japan, the Bank of Canada, and the European Central Bank.
Earnings season kicks into high gear next week, with such notables reporting as HAL, NFLX, TXN, JNJ, and AXP.
In addition, macro-economic data highlights for next week are as follows:
Monday
- Martin Luther King Jr. Day – US Markets closed
- ECB President Lagarde Speech
Tuesday
- BOJ Interest Rate Decision and Quarterly Outlook Report
- UK Employment data (DEC) Claimant Count expecting +26,000 vs +28,800 last
- German and EU ZEW Economic Sentiment Index (JAN). Expectations are for 15 and 6, respectively.
Wednesday
- Canada Inflation Rate (YoY) (DEC) Expectations are for 2.2% vs 2.2% last
- (MoM) expectation is for 0% vs -0.1% last
- BOC Interest Rate Decision and Monetary Policy Report
Thursday
- Australian Consumer Inflation Expectations (JAN) Expecting 3.7% vs 4% last
- Australian Employment Change (DEC) Expecting +16,000 vs +39,900 last
- ECB Interest Rate Decision, Press Conference, and Strategic Review
- Crude Oil Inventories
Friday
- BOJ Monetary Policy Meeting Minutes
- Worldwide Flash PMIs – In particular, for the US this will be the first piece of manufacturing data since the US-China trade deal was agreed. Markets participants will look closed to watch for an uptick in US PMIs.
- ECB President Lagarde Speech
- Canadian Retail Sales (MoM) (NOV) Expecting 0.4% vs -1.2% last
Chart to Watch: USD/JPY
Source: Tradingview, City Index
As stocks continue to put in new all-time highs, USD/JPY is moving right along with them. During the first week of the year, price put in a bullish engulfing candle after a false breakout out of the rising wedge. Last week, USD/JPY squeezed above strong horizontal resistance and the 200-week moving average near 109.70. The pair is currently approaching a long term downward sloping trending dating back to mid-2015. If price breaks above the trendline, it will look to fill the gap from the first week of May 2019 near 110.90/111.00.
Aside from the ceremonial signing of “Phase One” of the US-China Trade Deal, this past week was seemingly uneventful. The US Senate passed the United State- Mexico-Canada Agreement (USMCA) and it is currently waiting President Trump’s signature. Things between the US and Iran in the Middle East have calmed down, and stocks have continued their climb to all time highs on the back of better bank earnings.
The World Economic Forum’s annual meeting will be held next week in Davos, beginning on Wednesday. Many world leaders and large companies attend this event, including large oil companies, and it may be good for some potentially market moving soundbites.
With many of the political and geo-political events on the sidelines (for now), the markets next week are likely to begin focusing once again on central banks, macro-economic data and earnings.
There are three Central Bank meetings next week, which include the Bank of Japan, the Bank of Canada, and the European Central Bank.
Earnings season kicks into high gear next week, with such notables reporting as HAL, NFLX, TXN, JNJ, and AXP.
In addition, macro-economic data highlights for next week are as follows:
Monday
- Martin Luther King Jr. Day – US Markets closed
- ECB President Lagarde Speech
Tuesday
- BOJ Interest Rate Decision and Quarterly Outlook Report
- UK Employment data (DEC) Claimant Count expecting +26,000 vs +28,800 last
- German and EU ZEW Economic Sentiment Index (JAN). Expectations are for 15 and 6, respectively.
Wednesday
- Canada Inflation Rate (YoY) (DEC) Expectations are for 2.2% vs 2.2% last
- (MoM) expectation is for 0% vs -0.1% last
- BOC Interest Rate Decision and Monetary Policy Report
Thursday
- Australian Consumer Inflation Expectations (JAN) Expecting 3.7% vs 4% last
- Australian Employment Change (DEC) Expecting +16,000 vs +39,900 last
- ECB Interest Rate Decision, Press Conference, and Strategic Review
- Crude Oil Inventories
Friday
- BOJ Monetary Policy Meeting Minutes
- Worldwide Flash PMIs – In particular, for the US this will be the first piece of manufacturing data since the US-China trade deal was agreed. Markets participants will look closed to watch for an uptick in US PMIs.
- ECB President Lagarde Speech
- Canadian Retail Sales (MoM) (NOV) Expecting 0.4% vs -1.2% last
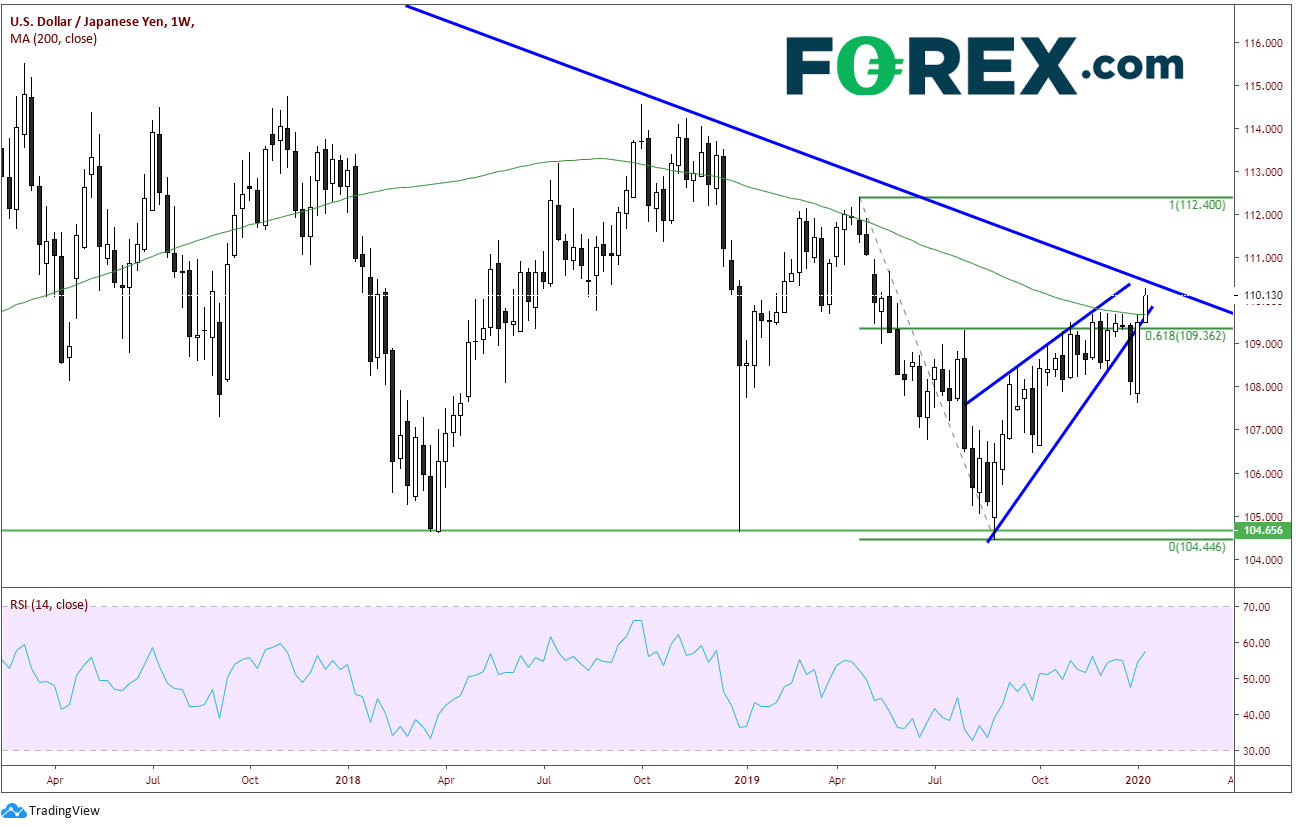
Chart to Watch: USD/JPY
Source: Tradingview, FOREX.COM
As stocks continue to put in new all-time highs, USD/JPY is moving right along with them. During the first week of the year, price put in a bullish engulfing candle after a false breakout out of the rising wedge. Last week, USD/JPY squeezed above strong horizontal resistance and the 200-week moving average near 109.70. The pair is currently approaching a long term downward sloping trending dating back to mid-2015. If price breaks above the trendline, it will look to fill the gap from the first week of May 2019 near 110.90/111.00.


Open an account today
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

USD/JPY Outlook: Yen Strength Builds as Carry Trades Come Under Threat
Rising equity volatility threatens yen carry trades as USD/JPY struggles at 160 resistance and AUD/JPY leads a broader recovery in the Japanese yen.


Gold and Silver's Deepening Dollar Dilemma
The dollar has broken higher, gold and silver have been crushed, and US financial conditions are tightening rapidly. Our historical analysis suggests this is no ordinary precious metals selloff.

British Pound Short-term Outlook: GBP/USD 3% Plunge Hits 12-Month Low—Key Support in Focus 11 19 2026
Sterling’s October rebound has unraveled, leaving GBP/USD bears in control—but stretched momentum raises the stakes for the weekly close

From time to time, StoneX Financial Pty Ltd (“we”, “our”) website may contain links to other sites and/or resources provided by third parties. These links and/or resources are provided for your information only and we have no control over the contents of those materials, and in no way endorse their content. Any analysis, opinion, commentary or research-based material on our website is for information and educational purposes only and is not, in any circumstances, intended to be an offer, recommendation or solicitation to buy or sell. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. No representation or warranty is made, express or implied, that the materials on our website are complete or accurate. We are not under any obligation to update any such material.
As such, we (and/or our associated companies) will not be responsible or liable for any loss or damage incurred by you or any third party arising out of, or in connection with, any use of the information on our website (other than with regards to any duty or liability that we are unable to limit or exclude by law or under the applicable regulatory system) and any such liability is hereby expressly disclaimed.