



Could BoE inaction propel FTSE to fresh record
The UK’s FTSE 100 index has had an amazing run of late, outperforming many of its peers. It has been supported above all by a weaker pound after a run of poor economic pointers sharply reduced the probability of a Bank of England rate increase in May.
Share this:

The UK’s FTSE 100 index has had an amazing run of late, outperforming many of its peers. It has been supported above all by a weaker pound after a run of poor economic pointers sharply reduced the probability of a Bank of England rate increase in May. Just a few weeks ago the BoE was widely expected to increase interest rates 25 basis points today, which now looks highly unlikely. As speculators priced out the prospects of an imminent rate increase from the BoE, this weighed heavily on the pound which helped to underpin the FTSE. Lower interest rates means UK companies and households will have access to very low rates for longer, in order to finance expansion and spending. The weaker pound also helps boost exports, as it makes UK goods and services more appealing to foreign buyers, while also boosting overseas company earnings when converted back to sterling. The commodity-heavy FTSE has also found good support from firmer oil and metal prices, while the rising global bond yields have supported bank and financial stocks, of which there’s plenty in the FTSE 100. If the BoE were to hold interest rates today as widely expected then this should provide a further short-term boost for the FTSE, while a surprise rate increase will surely have the opposite impact. But it is not as simple as that. After all, the market is now almost fully expecting the BoE to remain on hold, so the pound and FTSE may only move sharply if the BoE is surprisingly more dovish or surprisingly more hawkish than expected. But given the extent to of the FTSE’s recovery post the February drop, we think it will now reach a new record high – possibly as early as this week (see the chart below).
European stocks also finding support from weaker euro
It is not the FTSE 100 that’s showing good strength. European indices have risen sharply across the board, too. Like the UK, economic data in the Eurozone has surprised to the downside of late and this is helping to lower the probability of a sooner-than-expected policy normalisation from the European Central Bank. Reflecting the positive sentiment in Europe, the German DAX index is now up for the seventh consecutive weeks. But Italian stocks have remained under a bit of pressure due to the ongoing political turmoil there.
Wall Street has underperformed despite strong earnings; US CPI eyed
Meanwhile in the US, the stock markets have lagged behind, although even there the indices are now showing some strength. The relative underperformance of US stocks comes despite generally positive company earnings on Wall Street and due to a sharp rebound in the value of the dollar. Still, given the positive sentiment elsewhere, the S&P 500, which has been coiling for several months now, could break higher too. Stock market participants in the US have had a difficult task of weighing the negative impact of higher interest rates on equity prices against the benefit of stronger growth and higher oil prices. Company earnings have been positive on the whole while geopolitical concerns stemming from North Korea abated. However this has been overshadowed by the withdrawal of the US from the Iranian nuclear agreement and ongoing trade war concerns. Consequently, speculators have been quick to exit their positions each time the market moved sharply, causing the major indices to go into wide ranges without much progress in either direction following the vicious sell-off at the start of February. This indecisiveness has been reflected in the charts of the major indices, with the SP&P 500 for example making both higher lows and lower highs recently. But soon or later the market will break in one or the other direction and lead to a sharp move in the direction of the break. A trigger for the breakout could be if today’s US CPI data comes in weaker than expected, which should help to lower the odds of Fed hikes from three more to two more this year.
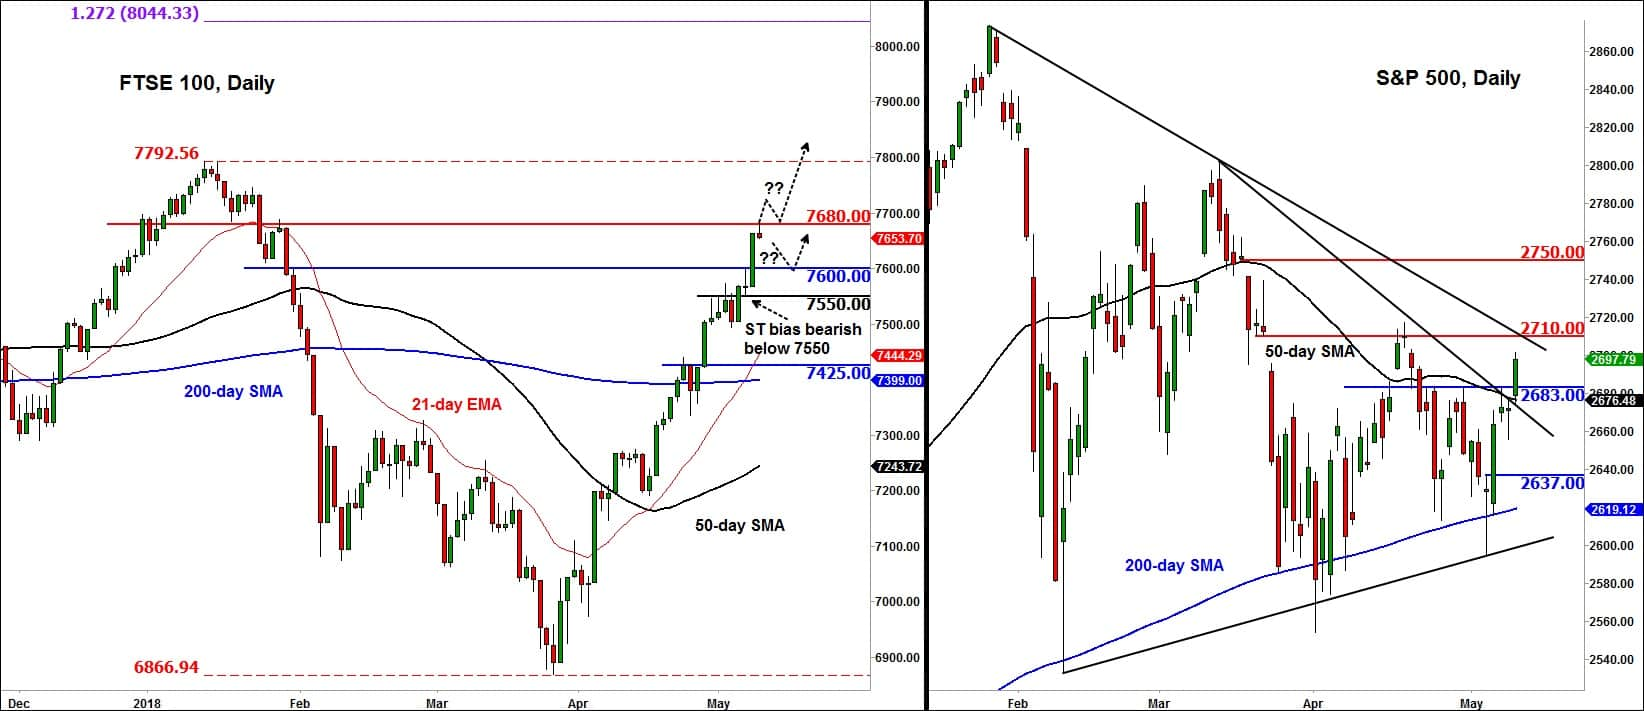
Source: eSignal and FOREX.com. Please note, these markets are not available to our US customers.
Related tags:
Latest market news




Open an account today
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
FTSE, Oil Forecast: Two trades to watch 181126
FTSE underperforms as miners slide and inflation rises. Oil breaks below key support as stockpiles rise.

GBP/USD approaches breaking point as US yields surge
A historic repricing of US interest rate expectations has propelled the dollar higher, leaving GBP/USD testing a crucial support level ahead of UK GDP.
GBP/USD Forecast: BoE Caution Leaves the Pound Searching for Direction
Although GBP/USD has gained close to 0.5% over the last three trading sessions, reflecting a period of relative strength for the British pound, today's session has started to show a more neutral tone and the bullish momentum seen earlier in the week has begun to slow.

From time to time, StoneX Financial Pty Ltd (“we”, “our”) website may contain links to other sites and/or resources provided by third parties. These links and/or resources are provided for your information only and we have no control over the contents of those materials, and in no way endorse their content. Any analysis, opinion, commentary or research-based material on our website is for information and educational purposes only and is not, in any circumstances, intended to be an offer, recommendation or solicitation to buy or sell. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. No representation or warranty is made, express or implied, that the materials on our website are complete or accurate. We are not under any obligation to update any such material.
As such, we (and/or our associated companies) will not be responsible or liable for any loss or damage incurred by you or any third party arising out of, or in connection with, any use of the information on our website (other than with regards to any duty or liability that we are unable to limit or exclude by law or under the applicable regulatory system) and any such liability is hereby expressly disclaimed.