



Dow Jones outlook: CPI, oil and yields put the rally to the test
US index futures rebounded in the first half of Wednesday’s session, along with European indices ahead of the release of US CPI. Some slightly dovish remarks from the Fed’s Williams seem to have helped sentiment a little, but whether those comments will be backed by data remains to be seen. While slightly hotter than expected inflation data shouldn’t be enough for markets to price in an October Fed hike with more than a coin flip probability, it can nonetheless reinforce expectations of further tightening later in the year.
Share this:
US index futures rebounded in the first half of Wednesday’s session, along with European indices ahead of the release of US CPI. Some slightly dovish remarks from the Fed’s Williams seem to have helped sentiment a little, but whether those comments will be backed by data remains to be seen. While slightly hotter than expected inflation data shouldn’t be enough for markets to price in an October Fed hike with more than a coin flip probability, it can nonetheless reinforce expectations of further tightening later in the year. As well as boosting the dollar, it could undermine equities which are already having to come to terms with the recent upsurge in bond yields and elevated oil prices. We maintain a cautious Dow Jones outlook for now.
US indices have had mixed performances of late
The abovementioned macro factors are making life increasingly difficult for US equity bulls to justify continued dip buying near record levels.
The S&P 500 and Nasdaq have remained remarkably resilient until a few days ago, but much of that strength has been concentrated in a relatively small group of mega-cap technology and AI stocks. Elsewhere, the picture is less convincing.
The Dow Jones and Russell 2000 are particularly worth watching in this respect. Their recent weakness points to a broader deterioration in risk appetite that is becoming harder for investors to dismiss.
Crude oil continues to apply pressure
Oil is at the centre of the problem. Prices have now risen for the third consecutive week to near their range highs, with Brent now comfortably above $100 a barrel, at around $105-A$106 area.
Rising oil prices matter not just because of the direct hit to consumers and businesses, but because of what it means for inflation and interest rates. Higher energy prices risk keeping inflation elevated for longer, while Treasury yields have already moved sharply higher in recent weeks as markets reassessed the outlook for monetary policy.
The 10-year Treasury yield has recent highs reached its highest levels since the early 2000s. At these levels, bonds are also becoming a more credible alternative to equities, potentially making investors less willing to pay the high valuations that have supported the stock market.
That makes today’s US inflation report particularly important.
CPI takes centre stage
Markets expect core CPI to rise 0.2% month-on-month, taking the annual rate to 2.5%, while headline inflation is expected to accelerate to 3.6%.
The problem for anyone looking for a major market move is that expectations are already fairly well established. Unless the numbers deliver a meaningful surprise, the initial reaction could prove relatively muted. That said, with oil prices elevated and Treasury yields already putting pressure on equities, even a modest upside surprise could reinforce concerns about the inflation outlook.
For the Dow, the more interesting question is whether CPI provides the catalyst for the next decisive move.
Dow Jones outlook: technical analysis and key levels
The Dow’s recent price action suggests that the market is becoming less comfortable at these elevated levels.
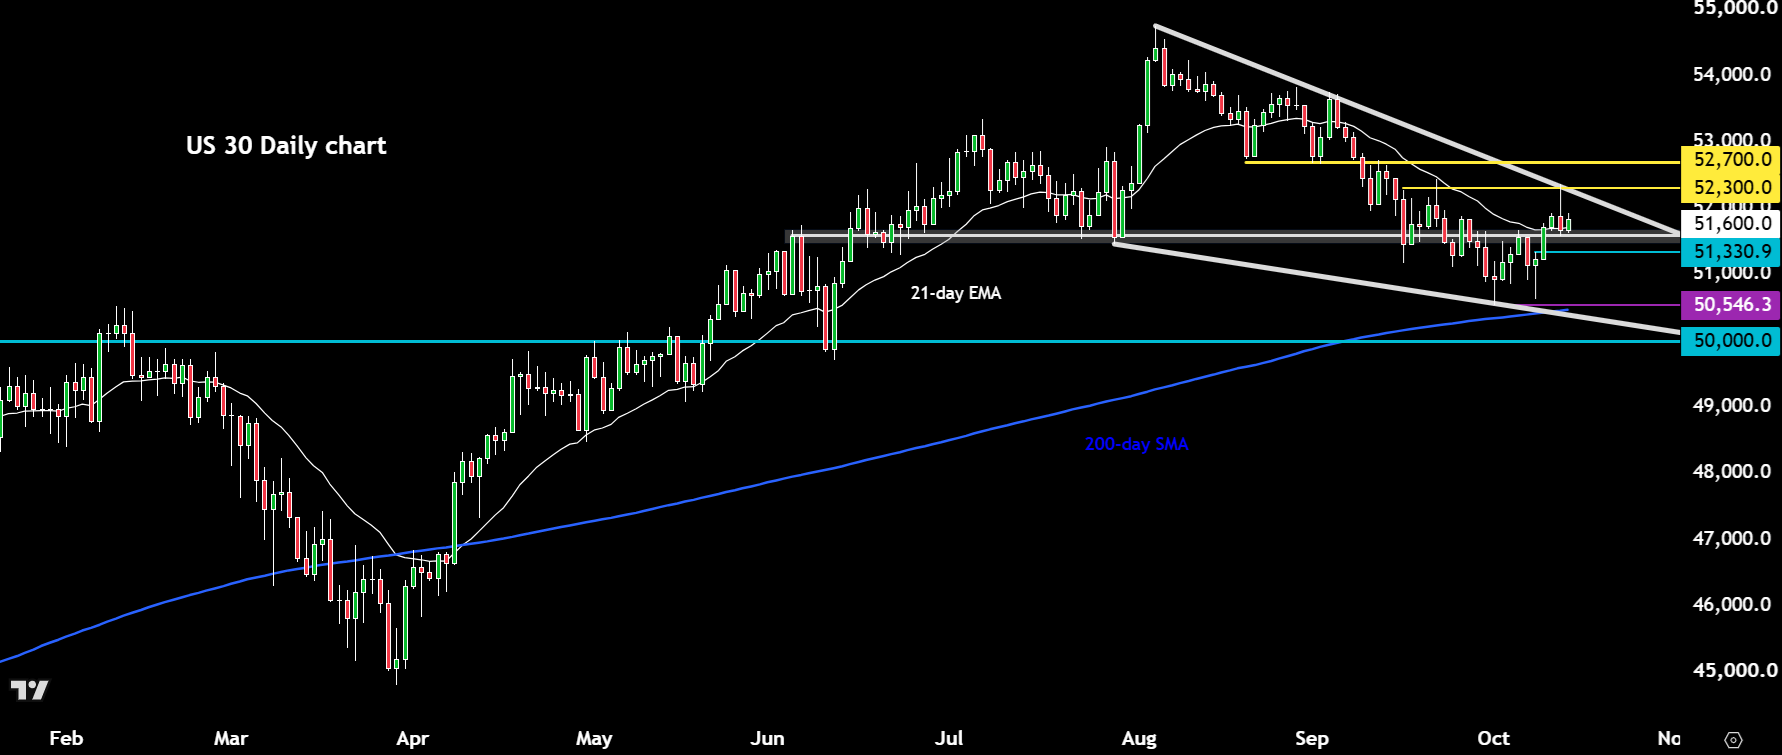
Tuesday’s session produced an inverted hammer after the Dow Jones index reversed sharply from the bearish trend line and resistance around 52,300 area. That is hardly an encouraging signal, particularly with CPI looming.
That said, we have not yet seen any meaningful downside follow-through. Key support around 51,600 has held firm for now.
But if that changes later, then the index could drop to test the next important support area around 51,330, below which there is nothing significant until the recent lows near 50,500 – 50,600 area.
On the upside, a potential move above 52,300 would improve the technical picture and potentially open the way towards 52,700 or even 53,000. But the risk is that Tuesday’s reversal proves to be the start of something more significant.
For now, the bulls are still hanging on. But with Brent oil back above $105+, Treasury yields remaining elevated and the Dow struggling to regain momentum, the technical picture is becoming increasingly fragile. Today’s CPI report could determine whether this is simply another pause in the broader rally or the beginning of a more meaningful correction.

Related tags:


Open an account today
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Nasdaq 100, SOX: Tech rout may be a symptom of something far larger
The financial tide is going out, and some of the market's biggest winners are being hammered. Our research suggests there's more to the tech rout than the AI headlines.

ASX 200 On Track for Worst Week in Four Years, Raising Bear Market Fears
The ASX 200 faces its worst week in four years as falling commodities, China's economic weakness and broad-based selling threaten a deeper correction.


S&P 500 Analysis: SPX Is Going Through One of Its Most Difficult Periods of 2026
Confidence around the U.S. equity market continues to face significant pressure. Over the last three trading sessions alone, the S&P 500 has fallen nearly 3.3%, highlighting a bearish bias that has become increasingly evident across the broader market.

From time to time, StoneX Financial Pty Ltd (“we”, “our”) website may contain links to other sites and/or resources provided by third parties. These links and/or resources are provided for your information only and we have no control over the contents of those materials, and in no way endorse their content. Any analysis, opinion, commentary or research-based material on our website is for information and educational purposes only and is not, in any circumstances, intended to be an offer, recommendation or solicitation to buy or sell. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. No representation or warranty is made, express or implied, that the materials on our website are complete or accurate. We are not under any obligation to update any such material.
As such, we (and/or our associated companies) will not be responsible or liable for any loss or damage incurred by you or any third party arising out of, or in connection with, any use of the information on our website (other than with regards to any duty or liability that we are unable to limit or exclude by law or under the applicable regulatory system) and any such liability is hereby expressly disclaimed.