



Draghis modest parting gift to sterling
Sterling briefly touched a three-month high after the ECB cut rates and relaunched QE
Share this:

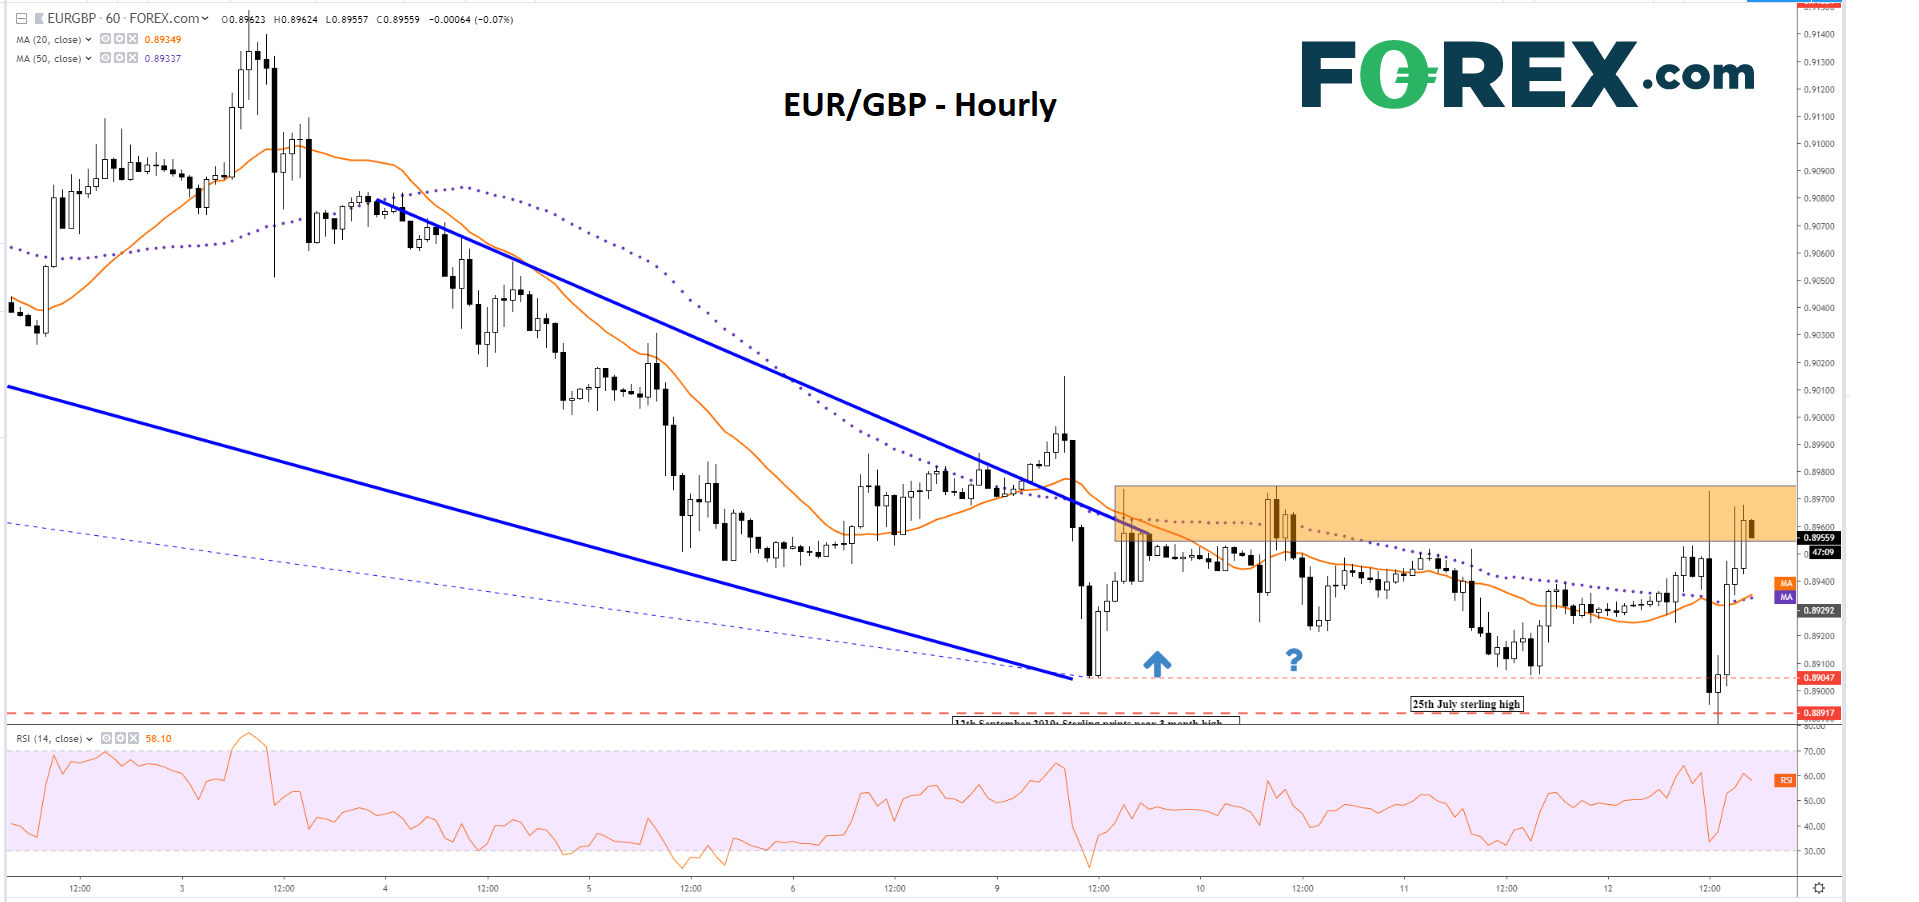
Sterling’s short-lived surge to a three-month high against the euro underscores both the ‘non-lethal’ nature of the ECB’s new bazooka as well as myriad Brexit pressures that remain for the pound. The rate’s immediate reaction was an 86-odd pip tip to tail slump to an almost three-month low (or high for the pound). But the euro subsequently moved to retake almost all of that a few hours afterwards.
The shared currency isn’t the only market that reacted like this. For instance, European bank shares went on a round trip that saw them shoot ahead of the overall market the instant the ECB said it was cutting rates and resuming QE, only to slump to the day’s lows soon afterwards. STOXX’s bank’s gauge eventually ended a tenth of a percentage point higher.
In many ways, the market anticipated this ambivalence quite accurately. For one thing, bank stocks have risen over the last few days, reflecting dwindling hopes of a ‘shock and awe’ policy announcement. Whilst overnight rate markets continued to price some sort of easing, the extent was doubtful. In the end, the 10-basis point deposit rate cut announced was close to the minimum the market was expecting. Investors also appear to have come to the same conclusion as ECB President Mario Draghi, who described the central bank’s package of measure as “adequate” this afternoon, possibly a signal that the Governing Council is coming around to the view that ‘unconventional measures’ are reaching the limits of their effectiveness. The bank’s new €20bn per month asset purchase programme has some mild tweaks relative to the previous round. That leaves the ‘tiered’ aspect of the new negative rates—which can exempt a large tranche of European bank deposits from punishment—as the key new condition overall.
Indeed, a rally across so-called core and periphery Eurozone sovereign rates suggests that the announcement of any new QE was a mild surprise to some investors, even if indications point to an expectation of increased QE to come.
All told, perhaps the pound’s modest reaction isn’t so much of a signal of the extent of underlying sterling weakness aa reflection of relatively tame ECB policy changes. On the other hand, sterling’s Brexit alert remains elevated, even during a Parliamentary hiatus. A Belfast Court added its verdict to those seen in recent days siding with the UK government, this time on whether a no-deal Brexit would break the Good Friday peace accord. Downing Street published no-deal plans as demanded by MPs, and they made for soberer reading than Prime Minister Boris Johnson earlier suggested. Either way, an early election which the market disfavours, and opposition politicians appear hesitant over, still looks to be on the cards this year. Sterling’s 4% advance off August lows was always going to be tough to extend on the back of ECB policy alone
EUR/GBP: Daily
Source: FOREX.com
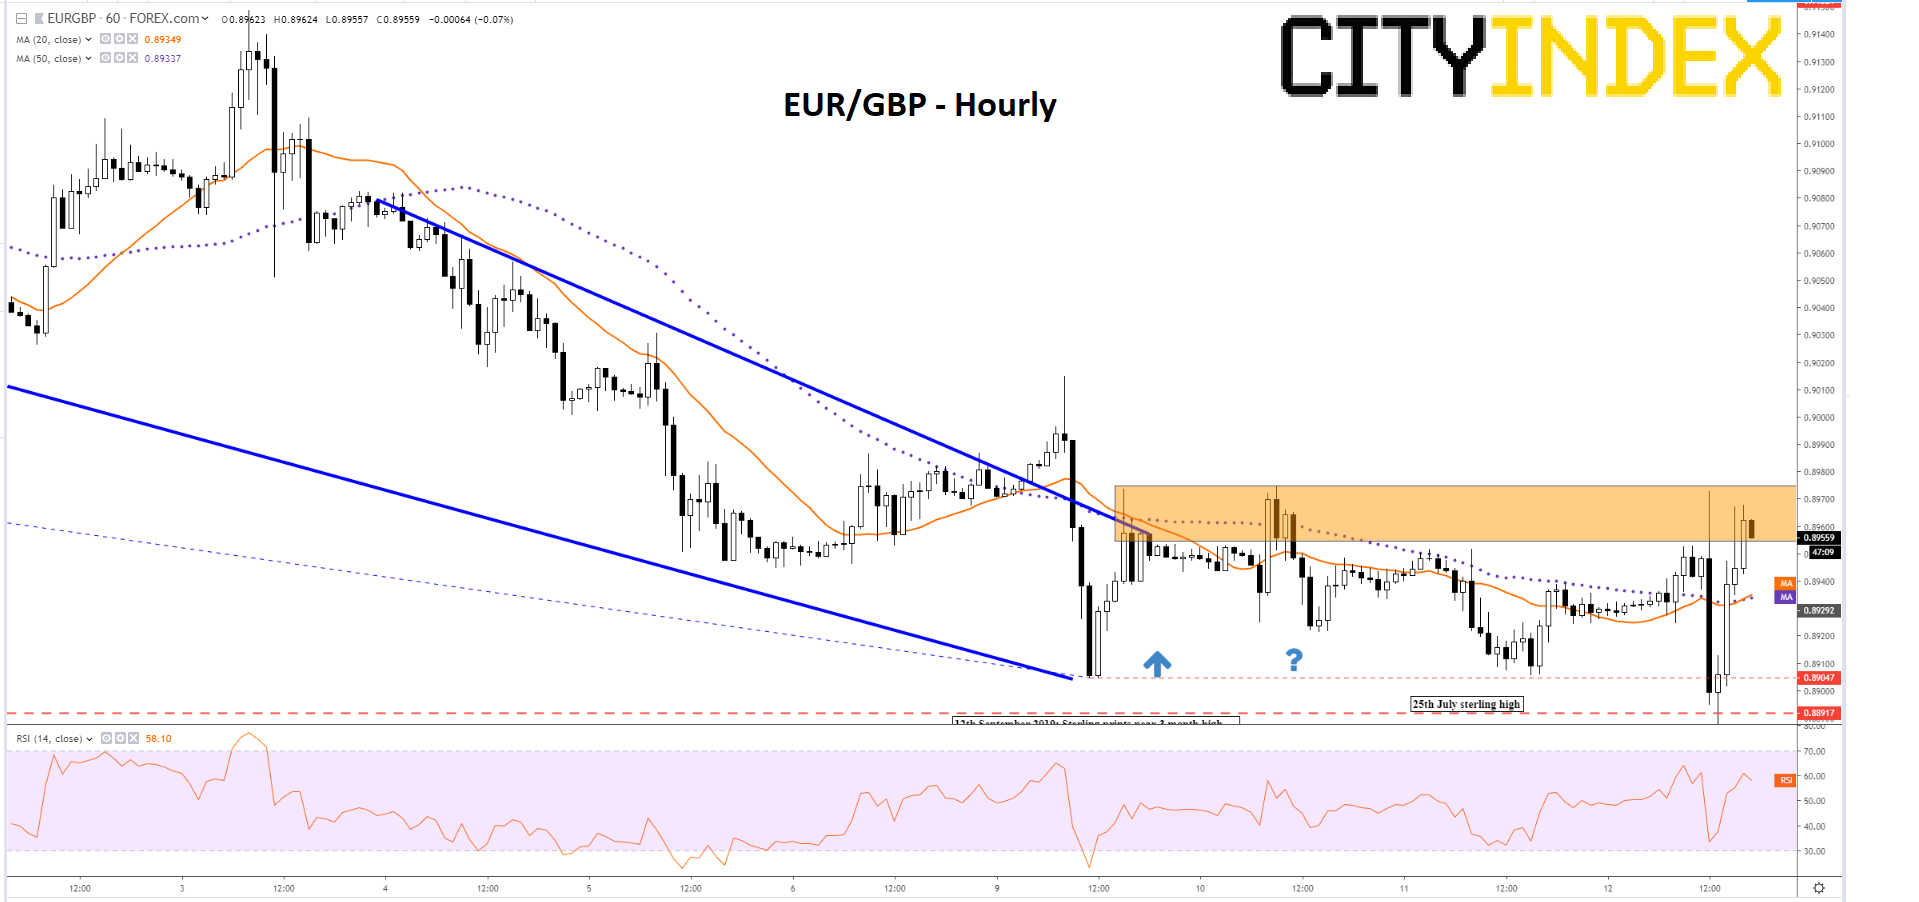
Sterling’s short-lived surge to a three-month high against the euro underscores both the ‘non-lethal’ nature of the ECB’s new bazooka as well as myriad Brexit pressures that remain for the pound. The rate’s immediate reaction was an 86-odd pip tip to tail slump to an almost three-month low (or high for the pound). But the euro subsequently moved to retake almost all of that a few hours afterwards.
The shared currency isn’t the only market that reacted like this. For instance, European bank shares went on a round trip that saw them shoot ahead of the overall market the instant the ECB said it was cutting rates and resuming QE, only to slump to the day’s lows soon afterwards. STOXX’s bank’s gauge eventually ended a tenth of a percentage point higher.
In many ways, the market anticipated this ambivalence quite accurately. For one thing, bank stocks have risen over the last few days, reflecting dwindling hopes of a ‘shock and awe’ policy announcement. Whilst overnight rate markets continued to price some sort of easing, the extent was doubtful. In the end, the 10-basis point deposit rate cut announced was close to the minimum the market was expecting. Investors also appear to have come to the same conclusion as ECB President Mario Draghi, who described the central bank’s package of measure as “adequate” this afternoon, possibly a signal that the Governing Council is coming around to the view that ‘unconventional measures’ are reaching the limits of their effectiveness. The bank’s new €20bn per month asset purchase programme has some mild tweaks relative to the previous round. That leaves the ‘tiered’ aspect of the new negative rates—which can exempt a large tranche of European bank deposits from punishment—as the key new condition overall.
Indeed, a rally across so-called core and periphery Eurozone sovereign rates suggests that the announcement of any new QE was a mild surprise to some investors, even if indications point to an expectation of increased QE to come.
All told, perhaps the pound’s modest reaction isn’t so much of a signal of the extent of underlying sterling weakness aa reflection of relatively tame ECB policy changes. On the other hand, sterling’s Brexit alert remains elevated, even during a Parliamentary hiatus. A Belfast Court added its verdict to those seen in recent days siding with the UK government, this time on whether a no-deal Brexit would break the Good Friday peace accord. Downing Street published no-deal plans as demanded by MPs, and they made for soberer reading than Prime Minister Boris Johnson earlier suggested. Either way, an early election which the market disfavours, and opposition politicians appear hesitant over, still looks to be on the cards this year. Sterling’s 4% advance off August lows was always going to be tough to extend on the back of ECB policy alone
EUR/GBP: Daily
Source: City Index


Open an account today
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

USD/JPY Outlook: Yen Strength Builds as Carry Trades Come Under Threat
Rising equity volatility threatens yen carry trades as USD/JPY struggles at 160 resistance and AUD/JPY leads a broader recovery in the Japanese yen.


Gold and Silver's Deepening Dollar Dilemma
The dollar has broken higher, gold and silver have been crushed, and US financial conditions are tightening rapidly. Our historical analysis suggests this is no ordinary precious metals selloff.

British Pound Short-term Outlook: GBP/USD 3% Plunge Hits 12-Month Low—Key Support in Focus 11 19 2026
Sterling’s October rebound has unraveled, leaving GBP/USD bears in control—but stretched momentum raises the stakes for the weekly close

From time to time, StoneX Financial Pty Ltd (“we”, “our”) website may contain links to other sites and/or resources provided by third parties. These links and/or resources are provided for your information only and we have no control over the contents of those materials, and in no way endorse their content. Any analysis, opinion, commentary or research-based material on our website is for information and educational purposes only and is not, in any circumstances, intended to be an offer, recommendation or solicitation to buy or sell. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. No representation or warranty is made, express or implied, that the materials on our website are complete or accurate. We are not under any obligation to update any such material.
As such, we (and/or our associated companies) will not be responsible or liable for any loss or damage incurred by you or any third party arising out of, or in connection with, any use of the information on our website (other than with regards to any duty or liability that we are unable to limit or exclude by law or under the applicable regulatory system) and any such liability is hereby expressly disclaimed.