


Euro Forecast: EUR/USD Recovery Persists Ahead of Euro Area CPI Report
EUR/USD may further retrace the decline from the start of the month as the Relative Strength Index (RSI) continues to recover from oversold territory.
Share this:
Euro Outlook: EUR/USD
EUR/USD extends the advance from the start of the week as the Euro Area Gross Domestic Product (GDP) report shows a larger-than-expected rise in the growth rate, and the exchange rate may further retrace the decline from the start of the month as the Relative Strength Index (RSI) continues to recover from oversold territory.
Euro Forecast: EUR/USD Recovery Persists Ahead of Euro Area CPI Report
EUR/USD trades to a fresh weekly high (1.0871) as the Euro Area expands 0.4% in the third quarter of 2024 versus forecasts for a 0.2% print, and little signs of an imminent recession may encourage the European Central Bank (ECB) to the keep interest rates on hold following the 25bp rate cut at the October meeting.
Join David Song for the Weekly Fundamental Market Outlook webinar. David provides a market overview and takes questions in real-time. Register Here
In turn, the ECB may continue to unwind its restrictive policy at a gradual pace as the central bank is ‘determined to ensure that inflation returns to our two per cent medium-term target in a timely manner,’ but the update to the Euro Area Consumer Price Index (CPI) may put pressure on the central bank to achieve a neutral policy sooner rather than later as the report is anticipated to show another slowdown in core inflation.
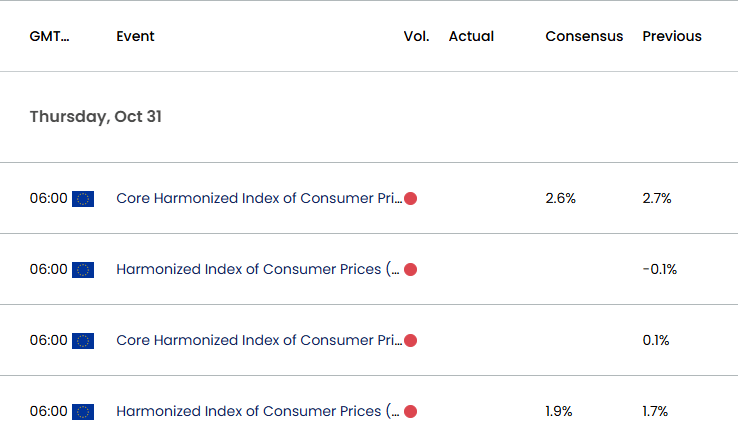
Euro Economic Calendar
Even though the headline CPI is expected to increase to 1.9% in October from 1.7% per annum the month prior, the core reading is seen narrowing to 2.6% from 2.7% during the same period.
With that said, signs of easing price growth may curb the recent recovery in EUR/USD as it fuels speculation for another rate cut at the next ECB meeting on December 12, but an uptick in both the headline and core CPI may generate a bullish reaction in the Euro as it raises the central bank’s scope to further combat inflation.
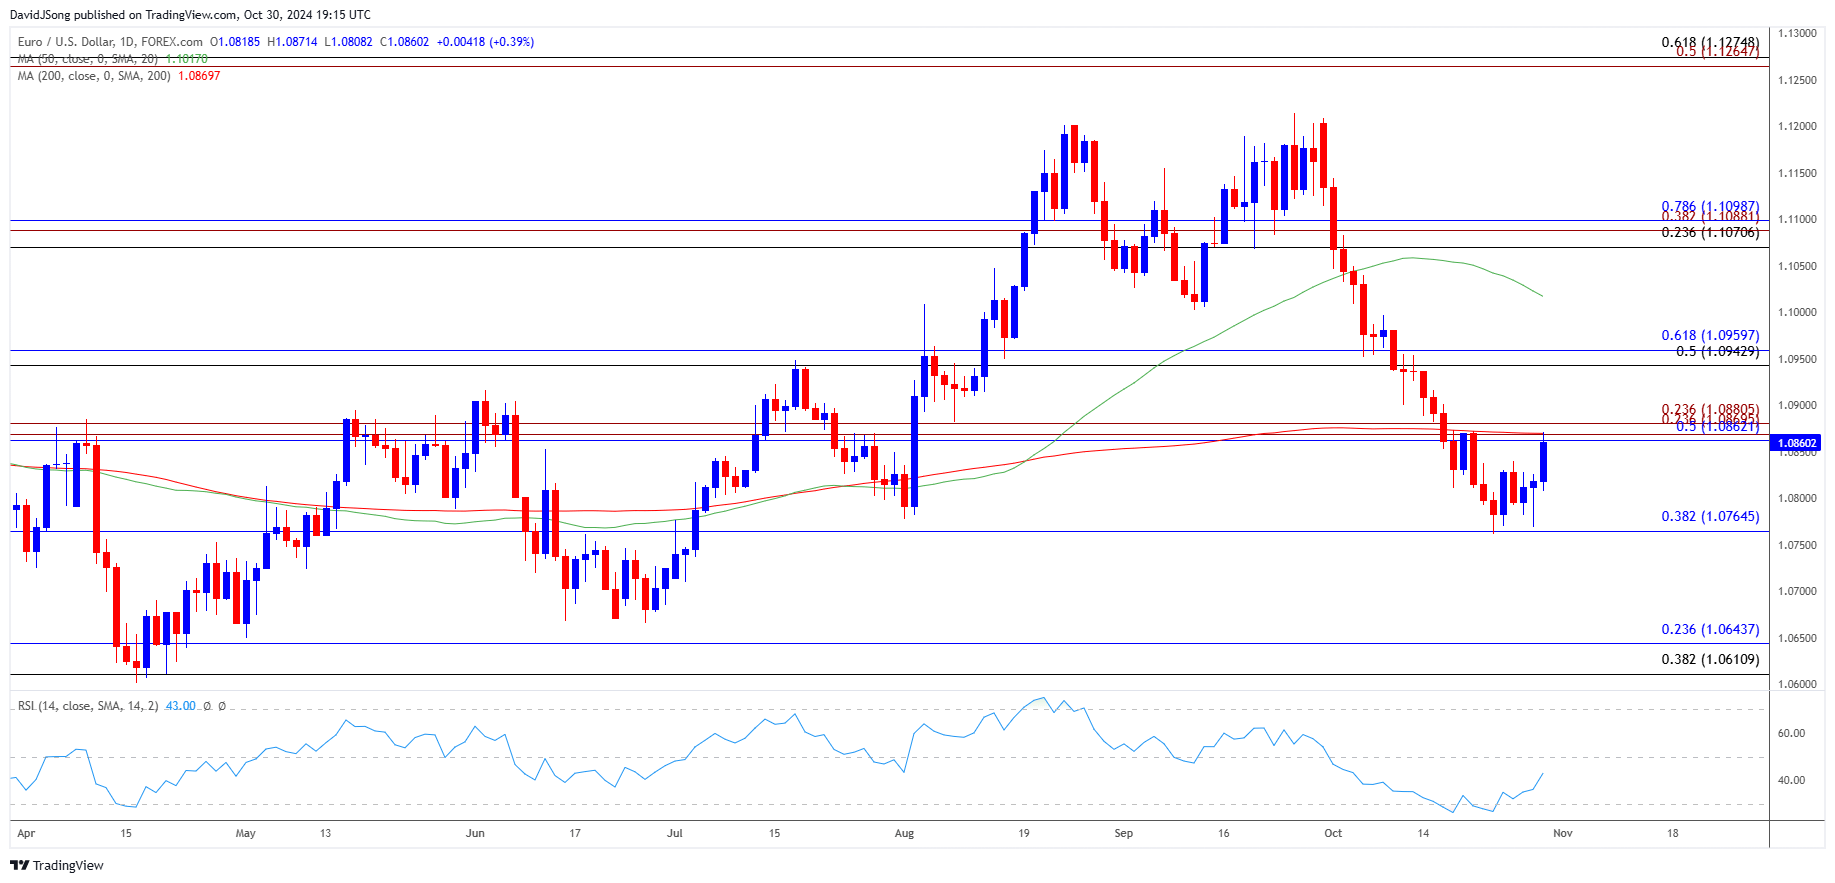
EUR/USD Chart – Daily
Chart Prepared by David Song, Strategist; EUR/USD on TradingView
- EUR/USD rises after defending the monthly low (1.0761) earlier this week, and the Relative Strength Index (RSI) may continue to show the bearish momentum abating as it moves away from oversold territory.
- A break/close above the 1.0860 (50% Fibonacci retracement) and 1.0880 (23.6% Fibonacci extension) region brings the 1.0940 (50% Fibonacci retracement) to 1.0960 (61.8% Fibonacci retracement) zone back on the radar.
- However, failure to break/close above the 1.0860 (50% Fibonacci retracement) and 1.0880 (23.6% Fibonacci extension) region may push EUR/USD back towards the monthly low (1.0761), with a close below 1.0770 (38.2% Fibonacci retracement) open up the June low (1.0666).
Additional Market Outlooks
Monetary vs Fiscal Policy: Implications for FX Markets
US Personal Consumption Expenditure (PCE) Report Preview (SEP 2024)
British Pound Outlook: GBP/USD Recovery Emerges Ahead of UK Budget
USD/CAD Eyes August High as RSI Holds in Overbought Territory
--- Written by David Song, Senior Strategist
Follow on Twitter at @DavidJSong
Related tags:
Latest market news



Open an account today
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

US Dollar Freight Train Drives EUR/USD, GBP/USD to Fresh Lows
A hawkish Fed and growing jitters around AI have pushed a continued rally in the Greenback, and there’s not yet an end in sight.


silver-crash-2026-vs-2011-collapse
Silver has collapsed some 65% from its January peak, drawing uncomfortable comparisons with the 2011 crash. The parallels are striking, but a bigger bubble, a hawkish Federal Reserve and years of supply deficits make this episode different.


Nasdaq 100, SOX: Tech rout may be a symptom of something far larger
The financial tide is going out, and some of the market's biggest winners are being hammered. Our research suggests there's more to the tech rout than the AI headlines.

From time to time, StoneX Financial Pty Ltd (“we”, “our”) website may contain links to other sites and/or resources provided by third parties. These links and/or resources are provided for your information only and we have no control over the contents of those materials, and in no way endorse their content. Any analysis, opinion, commentary or research-based material on our website is for information and educational purposes only and is not, in any circumstances, intended to be an offer, recommendation or solicitation to buy or sell. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. No representation or warranty is made, express or implied, that the materials on our website are complete or accurate. We are not under any obligation to update any such material.
As such, we (and/or our associated companies) will not be responsible or liable for any loss or damage incurred by you or any third party arising out of, or in connection with, any use of the information on our website (other than with regards to any duty or liability that we are unable to limit or exclude by law or under the applicable regulatory system) and any such liability is hereby expressly disclaimed.