


Quiet day in the market while Fed Easing Bets increase
Global equities gained in a thin session as traders priced in a December Fed rate cut. US indices rose ahead of Thanksgiving, led by tech, while the dollar softened and the yen hovered near intervention levels. Oil retreated on peace-talk optimism, gold eased, and Bitcoin rebounded above USD 91,000. Productivity trends and Greece’s outperformance highlight structural market drivers.
Share this:

Market Summary – 27 November 2025
Equities
- Global gains: Asian stocks advanced (MSCI Asia ex-Japan +0.4%) in a thin, holiday-affected session as traders priced in a potential December Fed rate cut.
- US performance: Major US indices rose ahead of Thanksgiving. Tech led, with AI-related stocks rebounding, while Communications lagged after Alphabet pulled back.
- SPX and Nasdaq both gained; Russell 2000 outperformed.
- US data were mixed — jobless claims remained low, durable goods orders beat, but Chicago PMI weakened sharply.
Currencies & Fixed Income
- Yen near intervention zone: Firmed toward JPY 156/USD, with traders monitoring potential BoJ action before year-end.
Commodities & Crypto
- Oil: Pulled back as optimism over Russia–Ukraine peace talks capped crude sentiment; EIA data showed a larger-than-expected inventory build.
- Gold: Slightly lower today after earlier gains, tracking the weaker dollar.
- Copper: Paused after recent strength; ICSG forecasts a 2026 global copper deficit (~150k tons) as mine output rises +2.3% and refined demand +2.1%.
- Bitcoin: Extended its rebound above USD 91,000, snapping back a four-week losing streak.
Germany 40 Technical analysis 4H Chart
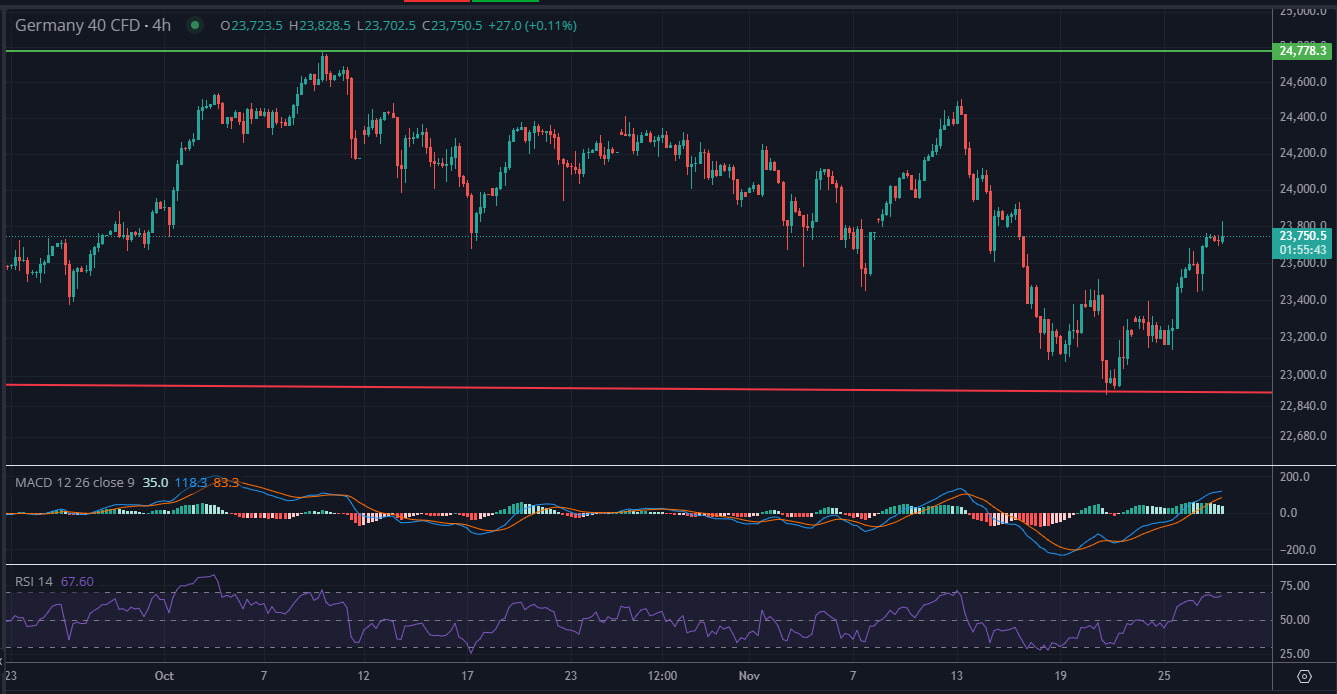
Price action on the Germany 40 4-hour chart shows a recovery from a recent low near 22,900, which aligns with a strong horizontal support level marked in red. The current price at 23,750 is approaching a short-term resistance zone but remains below the major resistance at 24,783. The overall structure suggests a medium-term downtrend with lower highs and lower lows since early November, but the recent rally indicates a potential corrective phase within that trend.
Momentum indicators confirm the bullish correction. The MACD histogram is positive, and the signal line crossover favors upward momentum. RSI at 67.80 is nearing overbought territory but not yet extreme, implying room for further upside before exhaustion. If price breaks above 23,900 decisively, the next target is the 24,200–24,400 zone, while failure to sustain above 23,700 could trigger a retest of 23,200 and possibly 22,900 support.
Corporate & Sector Highlights
- China property: Developer Vanke requested an extension on CNY 2 bn onshore bond repayments, sending the real estate index to a one-year low.
- US communications: Sector profits rose +17% YoY in Q3, led by three large media and entertainment firms that dominate over 75% of market cap.
- Telecoms remain weaker but offer dividend yields of 4–7%.
- US healthcare: Pharma and biotech stocks have climbed +25% since September on new government deals and weight-loss drug momentum, though medical device makers lag amid weaker household spending.
Macro & Policy Themes
- Productivity divergence: Since 1995, US productivity has grown 2.1% annually, over twice the eurozone rate, driven by stronger R&D, efficient capital allocation, and deeper capital markets.
- The US lead is expected to widen as AI adoption accelerates, underpinning higher profit forecasts and continued US equity outperformance.
- Greece outperforms: Athex +42.9%, MSCI Greece +54.1% YTD, buoyed by banks and strong earnings revisions. Supportive EU recovery funding and a steeper yield curve could sustain momentum into 2026.
Asia-Pacific Headlines
- China: Regulators tightened guidance on anti-competitive practices in smartphones and apps.
- Japan: BoJ’s Noguchi signalled gradual policy normalization if inflation trends persist; fiscal 2025 budget ~JPY 18.3 tn with increased 2- and 5-year JGB issuance.
- South Korea: BoK held at 2.5%, divided on near-term cuts; Governor Rhee sees growth near potential but warned of FX volatility.
- New Zealand: RBNZ’s Hawkesby said the OCR is now stimulative, adding the hurdle for further easing is high.
Other News
- Trump–Xi relations: Trump urged Japan to de-escalate Taiwan rhetoric after his recent call with Xi.
- South Africa tensions: Trump said the US would end subsidies and exclude South Africa from the 2026 G20, citing human-rights concerns; President Ramaphosa called the statement “regrettable.”
Summary:
Markets advanced on Fed easing hopes and strong tech sentiment. The dollar weakened, the yen steadied near intervention levels, and oil retreated on geopolitical optimism. Regionally, Greek and US equities remain outperformers, while Asia’s policy divergence and productivity dynamics continue to shape the global growth outlook.
--Written by Philip Papageorgiou – Market Analyst
-Follow me on X ex Twitter: PhilipForexCom


Open an account today
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Nasdaq 100, SOX: Tech rout may be a symptom of something far larger
The financial tide is going out, and some of the market's biggest winners are being hammered. Our research suggests there's more to the tech rout than the AI headlines.

Gold and Silver's Deepening Dollar Dilemma
The dollar has broken higher, gold and silver have been crushed, and US financial conditions are tightening rapidly. Our historical analysis suggests this is no ordinary precious metals selloff.

ASX 200 On Track for Worst Week in Four Years, Raising Bear Market Fears
The ASX 200 faces its worst week in four years as falling commodities, China's economic weakness and broad-based selling threaten a deeper correction.

From time to time, StoneX Financial Pty Ltd (“we”, “our”) website may contain links to other sites and/or resources provided by third parties. These links and/or resources are provided for your information only and we have no control over the contents of those materials, and in no way endorse their content. Any analysis, opinion, commentary or research-based material on our website is for information and educational purposes only and is not, in any circumstances, intended to be an offer, recommendation or solicitation to buy or sell. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. No representation or warranty is made, express or implied, that the materials on our website are complete or accurate. We are not under any obligation to update any such material.
As such, we (and/or our associated companies) will not be responsible or liable for any loss or damage incurred by you or any third party arising out of, or in connection with, any use of the information on our website (other than with regards to any duty or liability that we are unable to limit or exclude by law or under the applicable regulatory system) and any such liability is hereby expressly disclaimed.