



Market Brief FX Subdued Ahead of ECB Tomorrow US Indices Rally Across the Board
See a summary of the top market themes and trends from today's US trading session!
Share this:

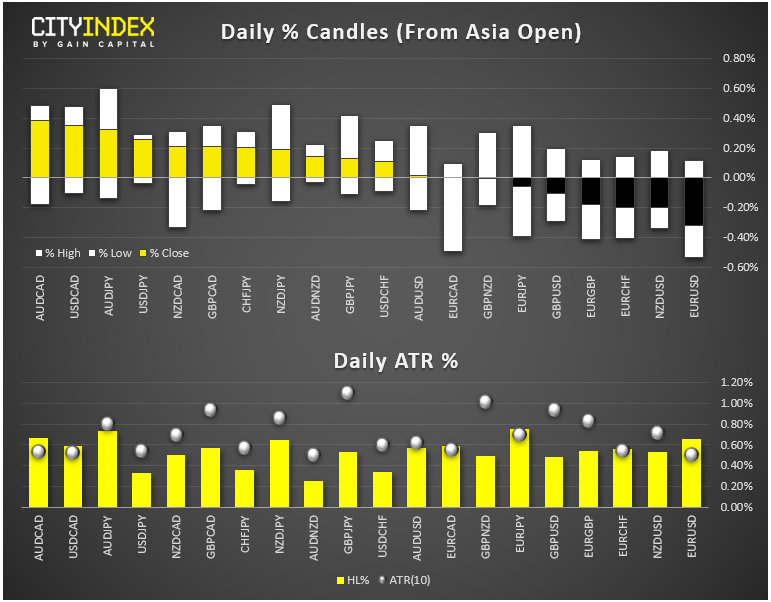
- FX: The aussie was the strongest major currency and the loonie was the weakest as PM Trudeau called for an election on October 21, introducing an element of political uncertainty into the currency. For more on today’s moves and the outlook for major currencies moving forward, today’s articles on GBP/USD and USD/CHF.
- US data: August PMI came in at +1.8% y/y, above expectations of a +1.7% reading. Continued solid inflation readings have caused traders to cut back the odds of a 50bps “double” rate cut from the Fed next week, though a 25bps cut looks like a done deal at this point.
- Separately, President Trump met with his advisors to discuss a possible capital gains tax cut.
- Tomorrow’s ECB decision will be the week’s marquee event – see our full preview here!
- Commodities: Oil fell around -2.5% on the day while gold edged higher after four straight days of selling.
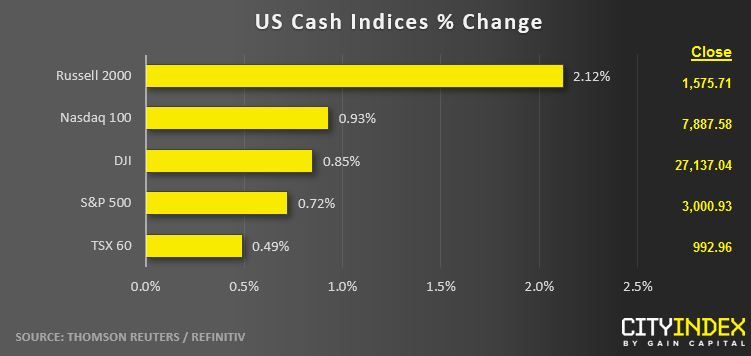
- US indices traded higher across the board, with the tech-heavy Nasdaq leading the way.
- Utilities (XLU) and Materials (XLB) were the strongest major sector on the day, while REITs (XLRE) brought up the rear.
- Stocks on the move:
- A couple of retailers rallied on no company-specific news: J.C. Penney Company (JCP) tacked on 25% today, while embattled Overstock.com (OSTK) gained 7%.
- All was not well for retailers though as GameStop (GME) lost -10% after reporting worse-than-expected earnings.
- RH (RH) rallied 5% on better-than-expected earnings figures.
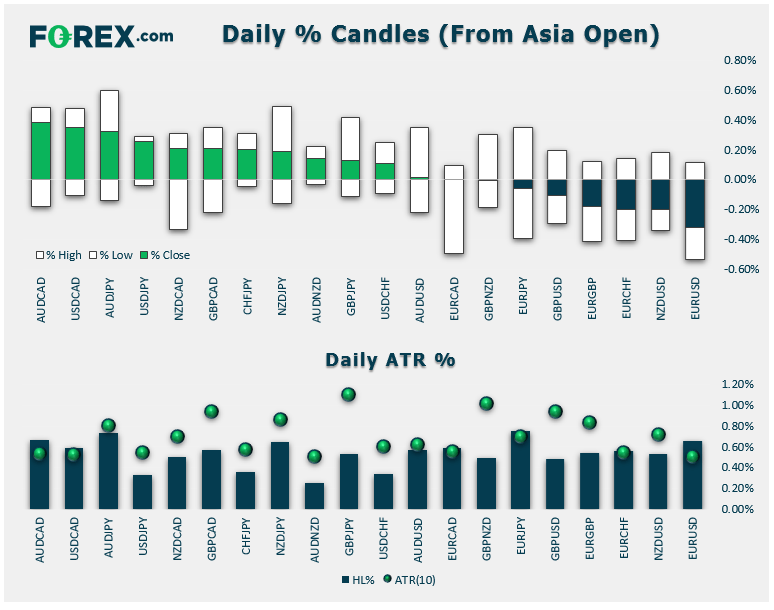
- FX: The aussie was the strongest major currency and the loonie was the weakest as PM Trudeau called for an election on October 21, introducing an element of political uncertainty into the currency. For more on today’s moves and the outlook for major currencies moving forward, today’s articles on GBP/USD and USD/CHF.
- US data: August PMI came in at +1.8% y/y, above expectations of a +1.7% reading. Continued solid inflation readings have caused traders to cut back the odds of a 50bps “double” rate cut from the Fed next week, though a 25bps cut looks like a done deal at this point.
- Separately, President Trump met with his advisors to discuss a possible capital gains tax cut.
- Tomorrow’s ECB decision will be the week’s marquee event – see our full preview here!
- Commodities: Oil fell around -2.5% on the day while gold edged higher after four straight days of selling.
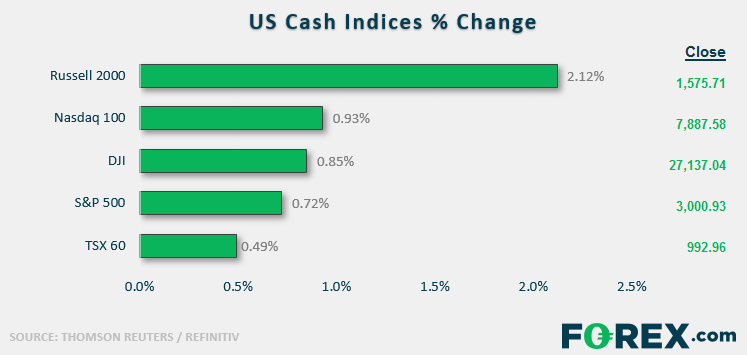
- US indices traded higher across the board, with the tech-heavy Nasdaq leading the way.
- Utilities (XLU) and Materials (XLB) were the strongest major sector on the day, while REITs (XLRE) brought up the rear.
- Stocks on the move:
- A couple of retailers rallied on no company-specific news: J.C. Penney Company (JCP) tacked on 25% today, while embattled Overstock.com (OSTK) gained 7%.
- All was not well for retailers though as GameStop (GME) lost -10% after reporting worse-than-expected earnings.
- RH (RH) rallied 5% on better-than-expected earnings figures.
Latest market news




Open an account today
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Nasdaq 100 Forecast: Anthropic Weighs on NDX Sentiment
As November approaches its end, weakening confidence around major equity benchmarks such as the Nasdaq 100 remains an important theme in financial markets. The index continues to face significant short-term weakness and, over the last two trading sessions alone, has fallen nearly 6.0%, highlighting a bearish bias that has not been this evident for several months.
US Dollar Freight Train Drives EUR/USD, GBP/USD to Fresh Lows
A hawkish Fed and growing jitters around AI have pushed a continued rally in the Greenback, and there’s not yet an end in sight.

Japanese Yen Forecast: USD/JPY Bulls Falter at Major Resistance—Critical Range Break in Focus 11 20 2026
USD/JPY’s latest retreat puts the September recovery under scrutiny, with nearby support offering bulls their next opportunity to respond.

From time to time, StoneX Financial Pty Ltd (“we”, “our”) website may contain links to other sites and/or resources provided by third parties. These links and/or resources are provided for your information only and we have no control over the contents of those materials, and in no way endorse their content. Any analysis, opinion, commentary or research-based material on our website is for information and educational purposes only and is not, in any circumstances, intended to be an offer, recommendation or solicitation to buy or sell. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. No representation or warranty is made, express or implied, that the materials on our website are complete or accurate. We are not under any obligation to update any such material.
As such, we (and/or our associated companies) will not be responsible or liable for any loss or damage incurred by you or any third party arising out of, or in connection with, any use of the information on our website (other than with regards to any duty or liability that we are unable to limit or exclude by law or under the applicable regulatory system) and any such liability is hereby expressly disclaimed.