



USD/JPY Forecast: Currency Pair of the Week | December 1, 2025
The yen has staged an assertive bid at the start of this week, fuelled by further gains in Japanese bond yields amid a hawkish repricing of interest rates in Japan. Among the yen pairs, the USD/JPY was down over 100 pips by the late afternoon London trade, with the pair also weighed down by the general softness observed in US dollar.
Share this:
Yen rallies as Japanese yields surge
The yen has staged an assertive bid at the start of this week, fuelled by further gains in Japanese bond yields amid a hawkish repricing of interest rates in Japan. Among the yen pairs, the USD/JPY was down over 100 pips by the late afternoon London trade, with the pair also weighed down by the general softness observed in US dollar. The mood was quite bearish in the crypto space with stocks also under pressure, amid concerns that the long-running yen-funded carry trade was being unwound. The USD/JPY forecast now looks to be tilted towards the downside as the market finally wakes up to the idea that the era of the one-way yen carry may be running out of steam.
BoJ December hike appears more likely now
Giving the bond markets a jolt was Bank of Japan Governor Kazuo Ueda, who delivered unexpectedly hawkish remarks, sending market pricing for a December hike from less than 15 basis points to 21 bp in a matter of hours. Investors were caught leaning the wrong way, assuming new Prime Minister Sanae Takaichi would act as the palace guard for dovish policy. Ueda decisively dispelled that idea, signalling no meaningful political resistance to higher rates and warning that delaying tightening could risk an uncomfortable spike in inflation. As the new filtered through, the Japanese bond market sell-off gathered pace, and that helped to lift both the yen and concerns about the unwinding of the carry trade.
Markets hits by unwind the carry trade fears
With Japanese Government Bond (JGB) yields lurching higher in recent days, this has effectively been pressing the brakes on cheap-yen funding many traders have used to leverage their positions. In other words, we are seeing a bit of a reverse-carry reaction which has rippled across risk assets today, pressuring speculative corners of the market as global investors unwind leveraged bets previously buoyed by rock-bottom Japanese yields.
Ueda laid out the BOJ’s framework with plain intent, stressing that upcoming wage data will be pivotal for December’s policy decision. He argued that a combination of proactive fiscal measures from Tokyo and a recalibration of monetary support from the BOJ should help steer Japan towards sustainable growth. This is a clear pushback against the narrative that Japan would remain parked indefinitely at zero rates.
The market’s response has been notable: USD/JPY traded roughly 0.7% lower as the Nikkei futures and JGBs broke down. But it is clear that the pair remains structurally overvalued at these levels. If the reverse-carry trade truly reawakens amid conviction that the BOJ could actually be taken seriously this time, then we could see the USD/JPY tumble back towards the low 150s again in short order.
What about the US dollar?
The Fed’s two most decisive data inputs — CPI and non-farm payrolls — won’t arrive until after the December rate decision next week. That drastically dilutes this week’s ability to spring any material surprises in as far as rate cut expectations are concerned.
ISM Manufacturing PMI remains in contraction as we just found out today with a print of 48.2, down from 49.0 the month before. On Wednesday, analysts anticipate flat ADP payrolls growth with risks tilting negative. Thursday’s Challenger job cuts could reintroduce softer employment signals, while Friday’s core PCE inflation is expected around 0.2% month-on-month — mild enough to keep rate-cut conversations alive without much fuss.
Meanwhile, a new Fed Chair appointment could land in the coming days, with market chatter pointing toward Kevin Hassett, whose dovish inclinations may add an additional layer of pressure on the greenback if confirmed.
Where does this all the USD/JPY forecast?
What matters moving forward the most is the evolving rate differential, and risk appetite, more than anything else. Japan is inching towards tightening, while the US remains anchored to easing expectations. This dynamic normally points towards a downward force on the USD/JPY forecast.
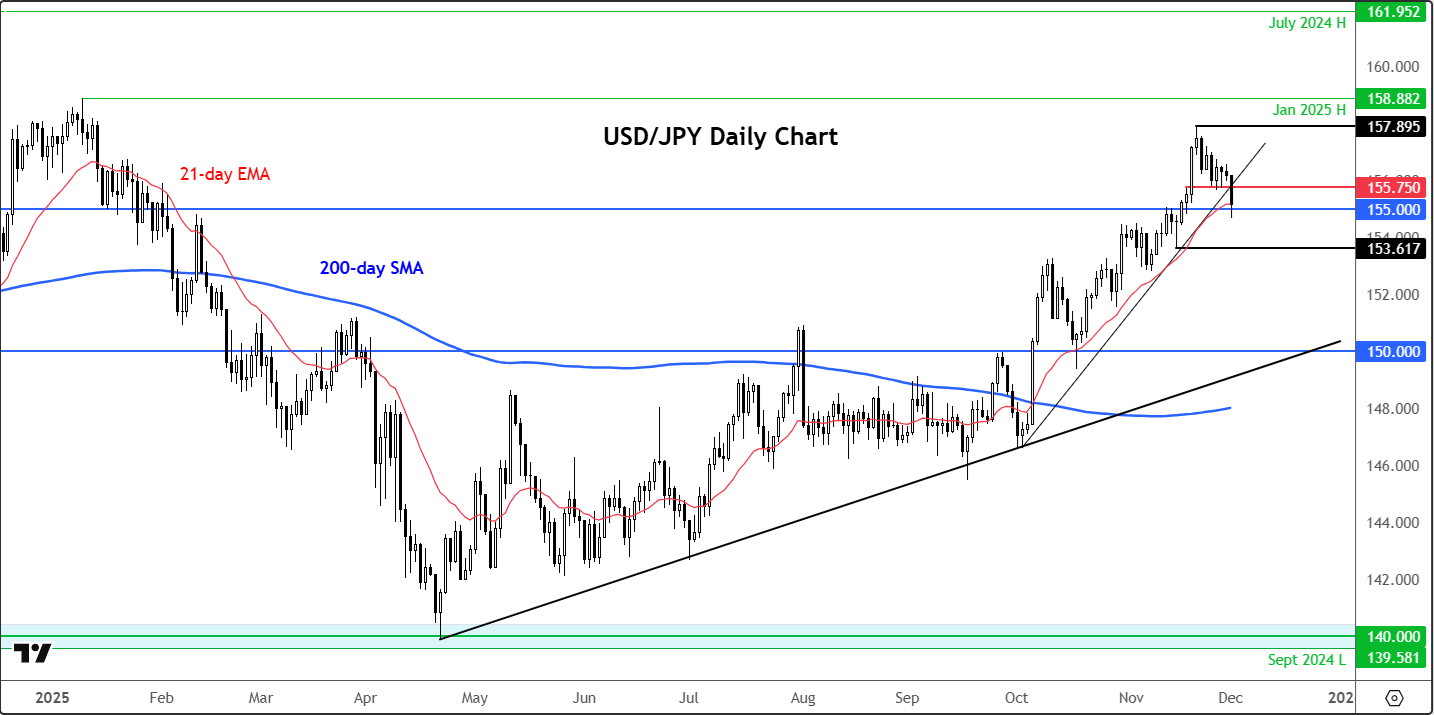
If the USD/JPY chart holds below the now broken 155.75 level, this should keep the bears in charge of price action in the short-term. And in the coming days if the pair closes decisively below 155.00 then this should further fuel the selling pressure, as this will effectively confirm the break of the trend line. However, if 155.75 level is reclaimed, then the bearish idea would become less compelling.

-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R
Latest market news



Open an account today
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/JPY Weekly Outlook: Yen Carry Unwind Risks Flash Red
A historic Nasdaq 100 selloff has revived fears of a disorderly yen carry trade unwind. Yet futures positioning, options pricing and Thanksgiving seasonality suggest the biggest threat to USD/JPY could come from the Fed itself.


US Dollar Freight Train Drives EUR/USD, GBP/USD to Fresh Lows
A hawkish Fed and growing jitters around AI have pushed a continued rally in the Greenback, and there’s not yet an end in sight.

Japanese Yen Forecast: USD/JPY Bulls Falter at Major Resistance—Critical Range Break in Focus 11 20 2026
USD/JPY’s latest retreat puts the September recovery under scrutiny, with nearby support offering bulls their next opportunity to respond.

From time to time, StoneX Financial Pty Ltd (“we”, “our”) website may contain links to other sites and/or resources provided by third parties. These links and/or resources are provided for your information only and we have no control over the contents of those materials, and in no way endorse their content. Any analysis, opinion, commentary or research-based material on our website is for information and educational purposes only and is not, in any circumstances, intended to be an offer, recommendation or solicitation to buy or sell. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. No representation or warranty is made, express or implied, that the materials on our website are complete or accurate. We are not under any obligation to update any such material.
As such, we (and/or our associated companies) will not be responsible or liable for any loss or damage incurred by you or any third party arising out of, or in connection with, any use of the information on our website (other than with regards to any duty or liability that we are unable to limit or exclude by law or under the applicable regulatory system) and any such liability is hereby expressly disclaimed.