



Asia Morning August 20
Federal Reserve officials expect the economy to require "additional accommodation" for recovering from the coronavirus pandemic...
Share this:
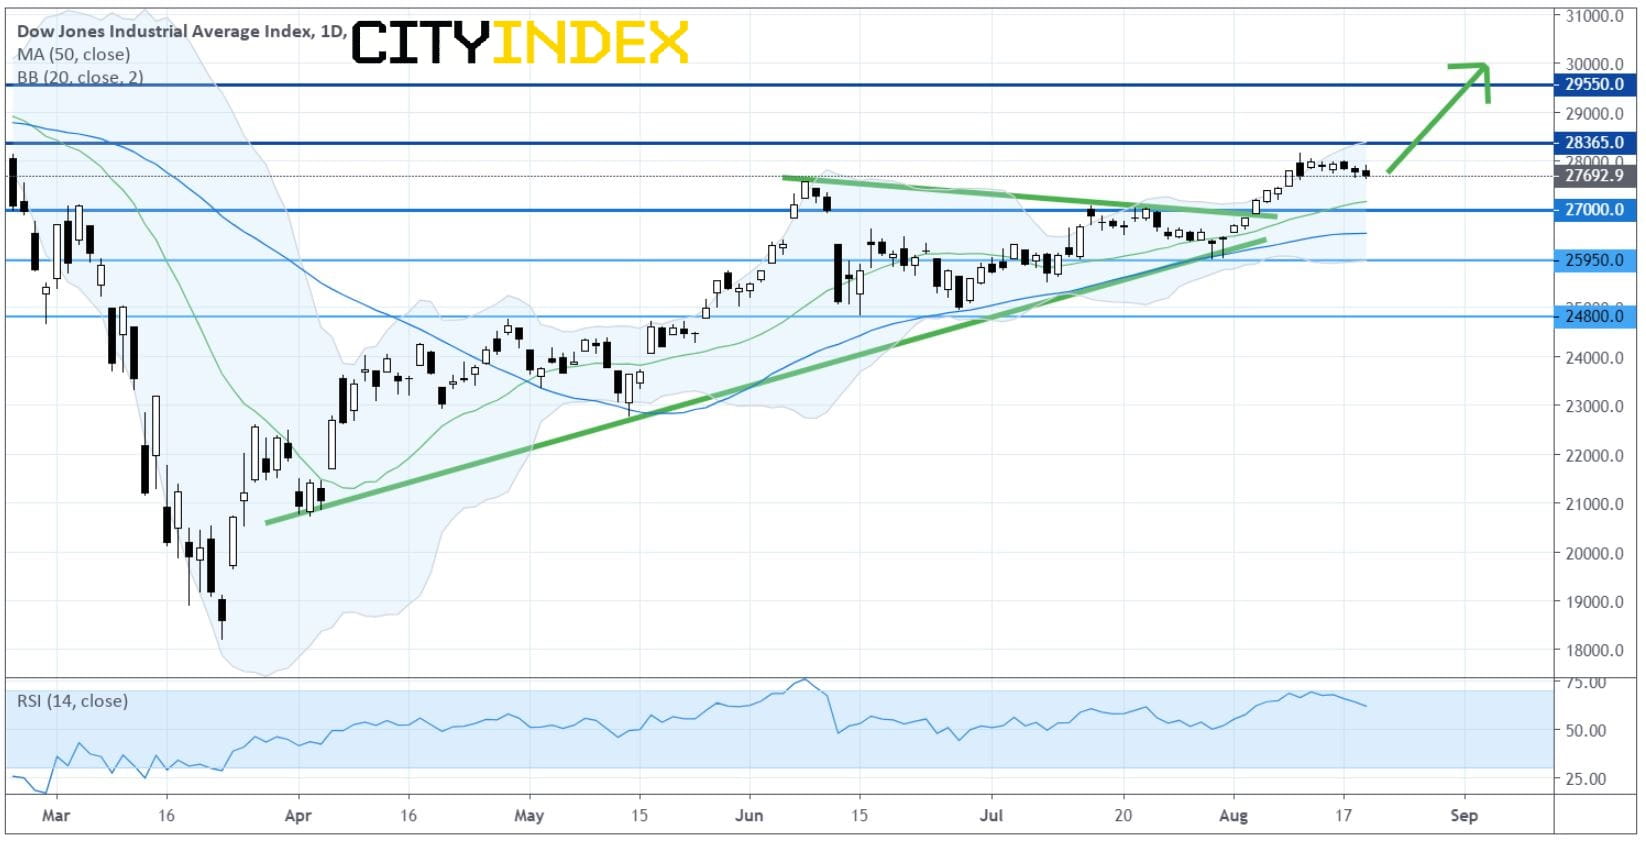
On Wednesday, U.S. stocks ended in the red. The Dow Jones Industrial Average fell 85 points (-0.31%) to 27692, the S&P 500 dropped 14 points (-0.44%) to 3374, and the Nasdaq 100 was down 80 points (-0.71%) to 11318.
Dow Jones Industrial Average: Daily Chart
Sources: GAIN Capital, TradingView
Real Estate (-2.02%), Automobiles & Components (-1.44%) and Energy (-1.16%) sectors lost the most. Target (TGT +12.65%) gapped up to an all-time high after reporting upbeat second-quarter results. Meanwhile, Jack Henry & Associates (JKHY -12.87%), TJX Companies (TJX -5.38%) and Gilead Sciences (GILD -4.87%) were top losers.
Shares of Momenta Pharmaceuticals (MNTA +69.17%) soared after Johnson & Johnson (JNJ +0.20%) agreed to acquire the company for $6.50 billion or $52.50 per share.
Approximately 60.8% (61.0% in the prior session) of stocks in the S&P 500 Index were trading above their 200-day moving average and 71.3% (76.4% in the prior session) were trading above their 20-day moving average.
Minutes from the U.S. Federal Reserve's latest meeting showed that officials expected the economy to require "additional accommodation" for recovering from the coronavirus pandemic.
Later today, investors will watch closely numbers of Initial Jobless Claims (a decline to 920,000 expected) and Continuing Claims (a fall to 15.00 million expected). The Conference Board Leading Index will also be released (+1.1% on month in July expected).
European stocks rebounded. The Stoxx Europe 600 Index rose 0.65%. Germany's DAX 30 increased 0.74%, France's CAC 40 gained 0.79%, and the U.K.'s FTSE 100 added 0.58%.
U.S. government bond prices eased, as the benchmark 10-year Treasury yield climbed to 0.685% from 0.662% Tuesday.
Spot gold lost again the key level of $2,000 an ounce, as it slumped $73.00 (-3.67%) to $1,929 an ounce. Spot silver shed 3.52% to $26.70 an ounce.
U.S. WTI crude oil futures (September) edged up 0.1% to $42.93 a barrel.
On the forex front, the ICE U.S. Dollar Index rebounded 0.9% on day to 93.00, halting a five-day decline, as the latest Federal Reserve's FOMC meeting minutes showed little guidance to future monetary policy path.
EUR/USD retreated 0.7% to 1.1847, following a five-day rally.
GBP/USD slid 0.9% to 1.3110. Official data showed that U.K. CPI grew 1.0% on year in July (+0.6% expected).
USD/JPY bounced 0.6% to 106.04.
USD/CAD climbed 0.4% to 1.3213. Government data showed that Canada's CPI grew 0.1% on year in July (+0.5% expected).
Other commodity-linked currencies were broadly lower against the greenback. AUD/USD dropped 0.8% to 0.7186 and NZD/USD was down 0.6% to 0.6562.
Dow Jones Industrial Average: Daily Chart
Sources: GAIN Capital, TradingView
Real Estate (-2.02%), Automobiles & Components (-1.44%) and Energy (-1.16%) sectors lost the most. Target (TGT +12.65%) gapped up to an all-time high after reporting upbeat second-quarter results. Meanwhile, Jack Henry & Associates (JKHY -12.87%), TJX Companies (TJX -5.38%) and Gilead Sciences (GILD -4.87%) were top losers.
Shares of Momenta Pharmaceuticals (MNTA +69.17%) soared after Johnson & Johnson (JNJ +0.20%) agreed to acquire the company for $6.50 billion or $52.50 per share.
Approximately 60.8% (61.0% in the prior session) of stocks in the S&P 500 Index were trading above their 200-day moving average and 71.3% (76.4% in the prior session) were trading above their 20-day moving average.
Minutes from the U.S. Federal Reserve's latest meeting showed that officials expected the economy to require "additional accommodation" for recovering from the coronavirus pandemic.
Later today, investors will watch closely numbers of Initial Jobless Claims (a decline to 920,000 expected) and Continuing Claims (a fall to 15.00 million expected). The Conference Board Leading Index will also be released (+1.1% on month in July expected).
European stocks rebounded. The Stoxx Europe 600 Index rose 0.65%. Germany's DAX 30 increased 0.74%, France's CAC 40 gained 0.79%, and the U.K.'s FTSE 100 added 0.58%.
U.S. government bond prices eased, as the benchmark 10-year Treasury yield climbed to 0.685% from 0.662% Tuesday.
Spot gold lost again the key level of $2,000 an ounce, as it slumped $73.00 (-3.67%) to $1,929 an ounce. Spot silver shed 3.52% to $26.70 an ounce.
U.S. WTI crude oil futures (September) edged up 0.1% to $42.93 a barrel.
On the forex front, the ICE U.S. Dollar Index rebounded 0.9% on day to 93.00, halting a five-day decline, as the latest Federal Reserve's FOMC meeting minutes showed little guidance to future monetary policy path.
EUR/USD retreated 0.7% to 1.1847, following a five-day rally.
GBP/USD slid 0.9% to 1.3110. Official data showed that U.K. CPI grew 1.0% on year in July (+0.6% expected).
USD/JPY bounced 0.6% to 106.04.
USD/CAD climbed 0.4% to 1.3213. Government data showed that Canada's CPI grew 0.1% on year in July (+0.5% expected).
Other commodity-linked currencies were broadly lower against the greenback. AUD/USD dropped 0.8% to 0.7186 and NZD/USD was down 0.6% to 0.6562.
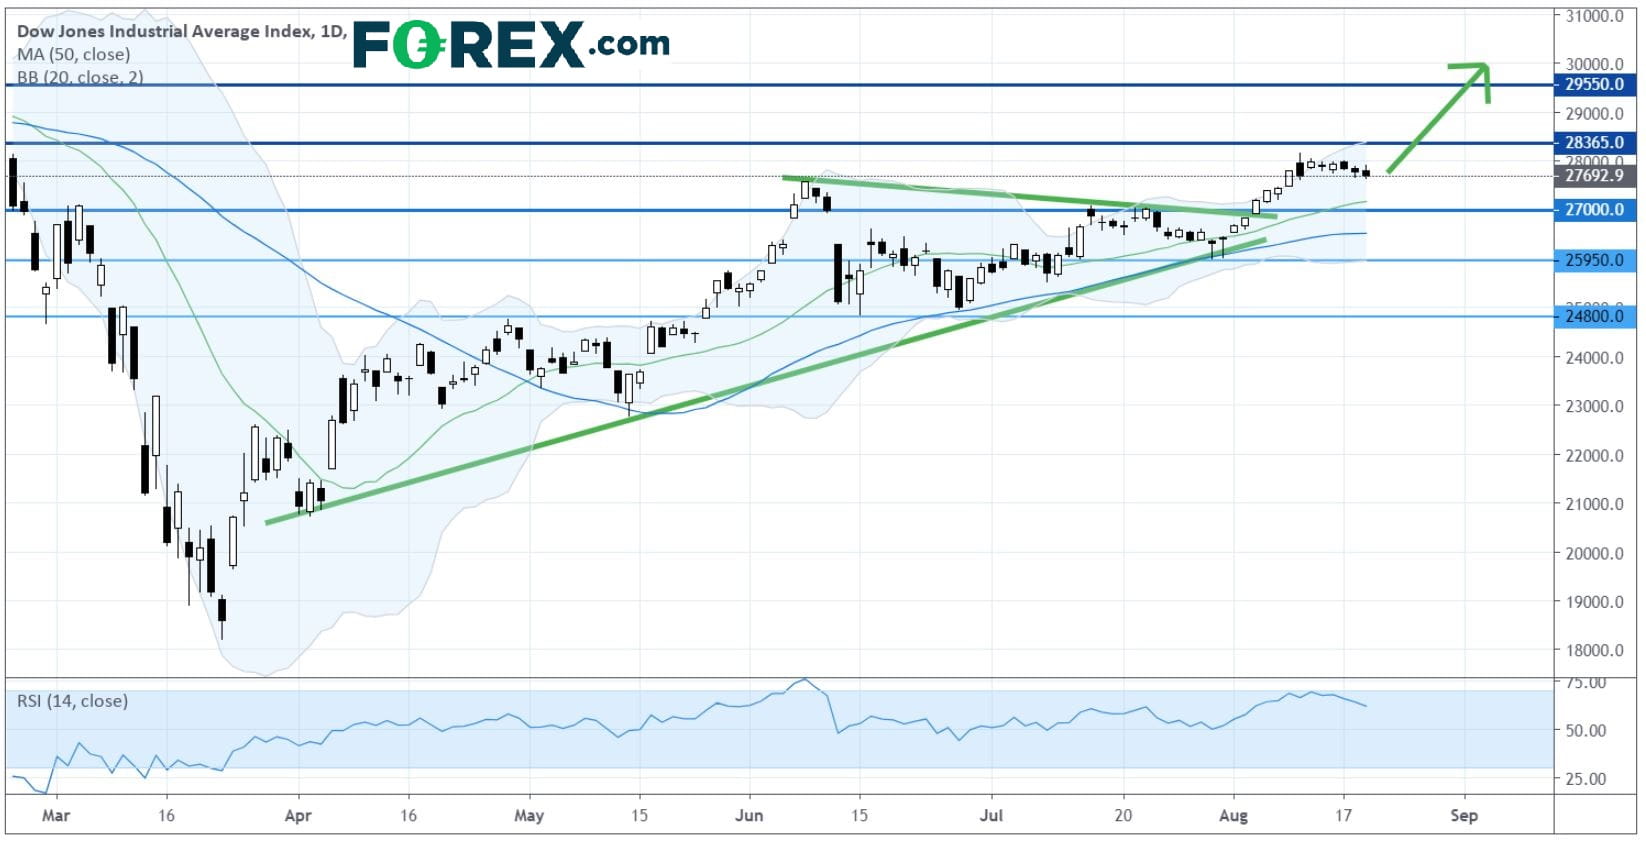
On Wednesday, U.S. stocks ended in the red. The Dow Jones Industrial Average fell 85 points (-0.31%) to 27692, the S&P 500 dropped 14 points (-0.44%) to 3374, and the Nasdaq 100 was down 80 points (-0.71%) to 11318.
Dow Jones Industrial Average: Daily Chart
Sources: GAIN Capital, TradingView
Real Estate (-2.02%), Automobiles & Components (-1.44%) and Energy (-1.16%) sectors lost the most. Target (TGT +12.65%) gapped up to an all-time high after reporting upbeat second-quarter results. Meanwhile, Jack Henry & Associates (JKHY -12.87%), TJX Companies (TJX -5.38%) and Gilead Sciences (GILD -4.87%) were top losers.
Shares of Momenta Pharmaceuticals (MNTA +69.17%) soared after Johnson & Johnson (JNJ +0.20%) agreed to acquire the company for $6.50 billion or $52.50 per share.
Approximately 60.8% (61.0% in the prior session) of stocks in the S&P 500 Index were trading above their 200-day moving average and 71.3% (76.4% in the prior session) were trading above their 20-day moving average.
Minutes from the U.S. Federal Reserve's latest meeting showed that officials expected the economy to require "additional accommodation" for recovering from the coronavirus pandemic.
Later today, investors will watch closely numbers of Initial Jobless Claims (a decline to 920,000 expected) and Continuing Claims (a fall to 15.00 million expected). The Conference Board Leading Index will also be released (+1.1% on month in July expected).
European stocks rebounded. The Stoxx Europe 600 Index rose 0.65%. Germany's DAX 30 increased 0.74%, France's CAC 40 gained 0.79%, and the U.K.'s FTSE 100 added 0.58%.
U.S. government bond prices eased, as the benchmark 10-year Treasury yield climbed to 0.685% from 0.662% Tuesday.
Spot gold lost again the key level of $2,000 an ounce, as it slumped $73.00 (-3.67%) to $1,929 an ounce. Spot silver shed 3.52% to $26.70 an ounce.
U.S. WTI crude oil futures (September) edged up 0.1% to $42.93 a barrel.
On the forex front, the ICE U.S. Dollar Index rebounded 0.9% on day to 93.00, halting a five-day decline, as the latest Federal Reserve's FOMC meeting minutes showed little guidance to future monetary policy path.
EUR/USD retreated 0.7% to 1.1847, following a five-day rally.
GBP/USD slid 0.9% to 1.3110. Official data showed that U.K. CPI grew 1.0% on year in July (+0.6% expected).
USD/JPY bounced 0.6% to 106.04.
USD/CAD climbed 0.4% to 1.3213. Government data showed that Canada's CPI grew 0.1% on year in July (+0.5% expected).
Other commodity-linked currencies were broadly lower against the greenback. AUD/USD dropped 0.8% to 0.7186 and NZD/USD was down 0.6% to 0.6562.
Dow Jones Industrial Average: Daily Chart
Sources: GAIN Capital, TradingView
Real Estate (-2.02%), Automobiles & Components (-1.44%) and Energy (-1.16%) sectors lost the most. Target (TGT +12.65%) gapped up to an all-time high after reporting upbeat second-quarter results. Meanwhile, Jack Henry & Associates (JKHY -12.87%), TJX Companies (TJX -5.38%) and Gilead Sciences (GILD -4.87%) were top losers.
Shares of Momenta Pharmaceuticals (MNTA +69.17%) soared after Johnson & Johnson (JNJ +0.20%) agreed to acquire the company for $6.50 billion or $52.50 per share.
Approximately 60.8% (61.0% in the prior session) of stocks in the S&P 500 Index were trading above their 200-day moving average and 71.3% (76.4% in the prior session) were trading above their 20-day moving average.
Minutes from the U.S. Federal Reserve's latest meeting showed that officials expected the economy to require "additional accommodation" for recovering from the coronavirus pandemic.
Later today, investors will watch closely numbers of Initial Jobless Claims (a decline to 920,000 expected) and Continuing Claims (a fall to 15.00 million expected). The Conference Board Leading Index will also be released (+1.1% on month in July expected).
European stocks rebounded. The Stoxx Europe 600 Index rose 0.65%. Germany's DAX 30 increased 0.74%, France's CAC 40 gained 0.79%, and the U.K.'s FTSE 100 added 0.58%.
U.S. government bond prices eased, as the benchmark 10-year Treasury yield climbed to 0.685% from 0.662% Tuesday.
Spot gold lost again the key level of $2,000 an ounce, as it slumped $73.00 (-3.67%) to $1,929 an ounce. Spot silver shed 3.52% to $26.70 an ounce.
U.S. WTI crude oil futures (September) edged up 0.1% to $42.93 a barrel.
On the forex front, the ICE U.S. Dollar Index rebounded 0.9% on day to 93.00, halting a five-day decline, as the latest Federal Reserve's FOMC meeting minutes showed little guidance to future monetary policy path.
EUR/USD retreated 0.7% to 1.1847, following a five-day rally.
GBP/USD slid 0.9% to 1.3110. Official data showed that U.K. CPI grew 1.0% on year in July (+0.6% expected).
USD/JPY bounced 0.6% to 106.04.
USD/CAD climbed 0.4% to 1.3213. Government data showed that Canada's CPI grew 0.1% on year in July (+0.5% expected).
Other commodity-linked currencies were broadly lower against the greenback. AUD/USD dropped 0.8% to 0.7186 and NZD/USD was down 0.6% to 0.6562.
Related tags:


Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/MXN Forecast: Peso Loses Momentum Ahead of Banxico Decision
Over recent trading sessions, the Mexican peso has started to show signs of losing strength against the U.S. dollar. This can be seen in the performance of USD/MXN, which has gained more than 1.7% over the last three sessions, highlighting the dollar's renewed strength against the peso.

Euro Short-term Outlook: EUR/USD Selloff Nears Critical Yearly Support 9 23 2026
Euro has fallen seven of the past nine sessions, with stretched momentum raising the stakes as EUR/USD closes in on a major inflection zone.


GBP/USD forecast: US dollar surges as bonds implode
The US dollar continued to press higher deep into the European session, supported by the slump in the bond markets as yields broke out across the curve. Following the recent hawkish Fed rate hike, yield spreads between the US and the rest of the world has continually increased, and that motion continued today, helped in part by some forecast-beating US macro data and hawkish Fed commentary.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.