



Bulls back in charge on better inflation data
Financial markets are tending towards risk-on ahead of tomorrow’s Fed meeting, with no worse than expected inflation data pointing to no immediate rate increases. Traders believe that the bull market has resumed, looking forward to declining rates in the second half of the year. Bottom line – risk-on.
Share this:

Financial markets are tending towards risk-on ahead of tomorrow’s Fed meeting, with no worse than expected inflation data pointing to no immediate rate increases. Traders believe that the bull market has resumed, looking forward to declining rates in the second half of the year.
Bottom line – risk-on.
TODAY’S MAJOR MARKETS
Equity markets
- The Nasdaq 100 and S&P 500 indexes were both up 0.7%, while the more broadly based Russell 2000 was up 1.3%. Smaller more cyclical and tech stocks continue to lead in the US
- Abroad, the Nikkei, DAX and the FTSE 100 indexes rose 1.8%, 0.7%, and 0.3%, respectively. Japan and emerging markets are leading
- The VIX, Wall Street’s fear index, rose 3% to 14.6 after a long period in decline, but readings don’t give cause for concern
Currencies and Bonds
- The dollar index was slightly weaker this morning, at 103.3, down 0.3%. Still no sign of the dollar breaking out of its narrow trading range
- Euro and sterling x-rates versus the dollar were up 0.3% and 0.7%
- Yields on 2- and 10-year Treasuries rose to 4.69% and 3.82%. Bond yields should decline if inflation and rates head lower
Commodities
- Gold prices fell back 0.7% to $1,956 per ounce, failing to hold the psychologically important 2K mark
- Crude oil prices rebounded, up 3.8% to $67.3 per barrel, with supply-side bulls gaining the upper hand on anticipated OPEC+ output reductions
- Grain and oilseed markets were mostly higher, supported by weaker crop ratings in the Midwest, a weaker dollar, and specific news about government support for ethanol fuel
DISCUSSION
Improved inflation data boosts ‘pause’ storyline
Better-than-expected consumer price index (CPI) inflation data released this morning spurred belief that the Fed will pause interest rate hikes at tomorrow’s meeting. Core inflation remains sticky, but declining energy prices helped drive the headline number lower. We are scheduled to get producer price index (PPI) inflation data tomorrow, but it’s unlikely to sway views.
Wall Street adopted a cautious "risk-on" sentiment today, choosing to see the proverbial glass as "half full”, also justifying the resumed bull market in equities. The Fed has been focused on the core numbers that show the stickiness of inflation that cannot be brought down to the 2% mandate without the continuation of hawkish policy. That’s especially true for a Fed that has repeatedly stated that it would rather error on the side of higher for longer on rates.
Fed fund futures continues to price in expectations of a pause in June, and a 25-basis point increase in the Fed's benchmark rate in July, followed by rate cuts by the end of the year – although recent data and comments by Fed members suggest that the pause may be much longer than the market anticipates before cuts begin.
CPI Data by the numbers
- Headline CPI was up 4.0% year-on-year in May, below an expected 4.1%, down from 4.9% in April
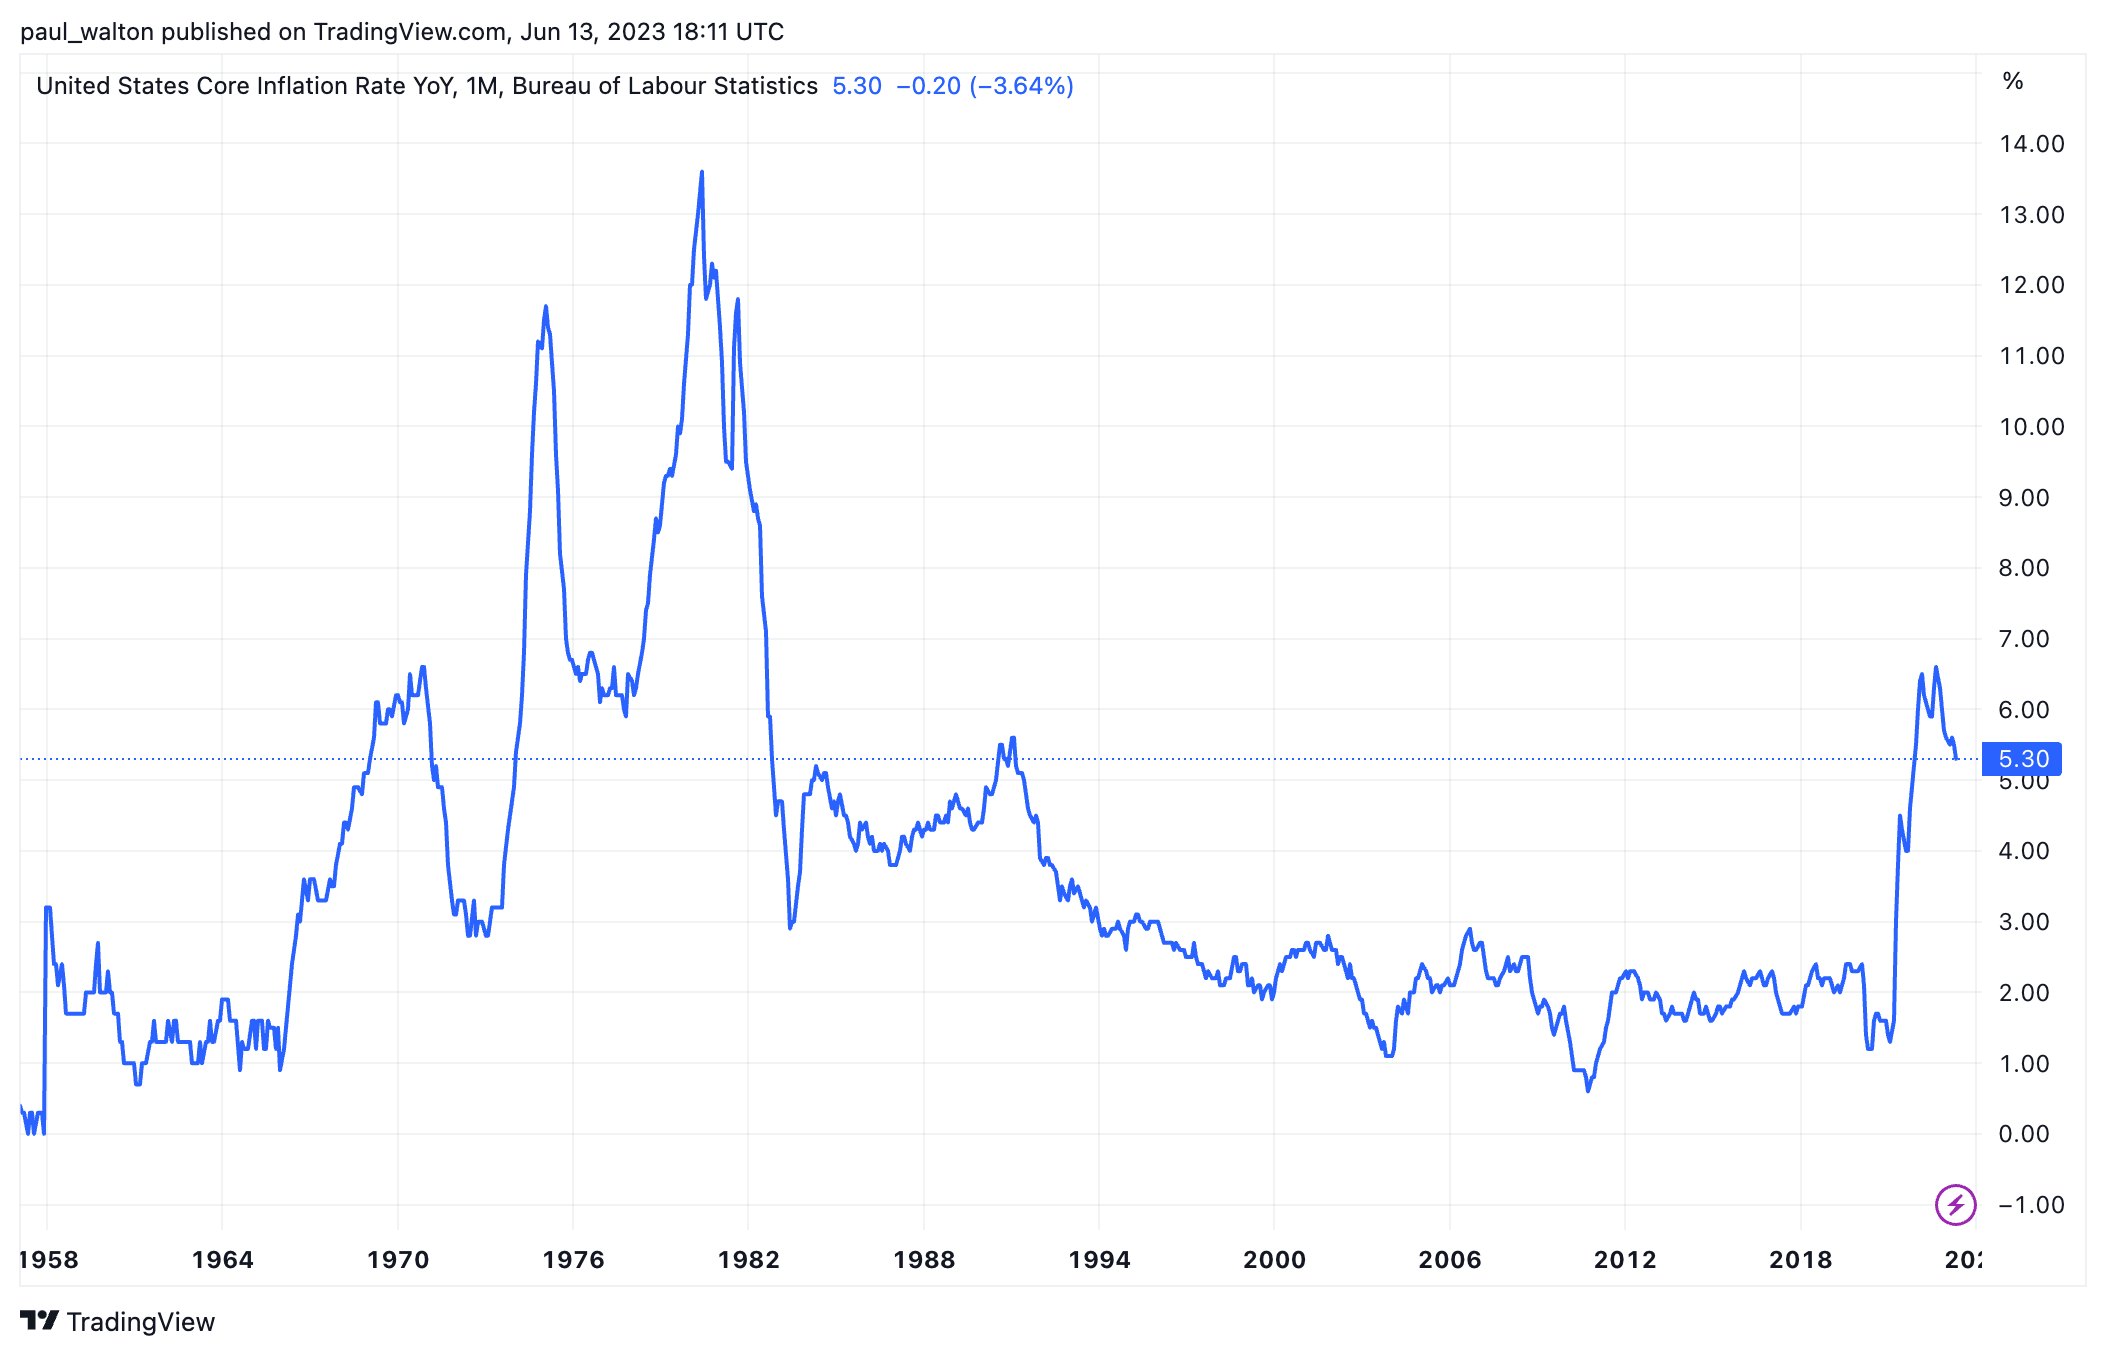
- Core CPI, excluding the more volatile food and energy sectors, was up 5.3% year-on-year in May, matching expectations, down from 5.5% in April
- The Cleveland Fed’s “now-casting” inflation indicator had predicted the headline CPI to be up 4.13% year-on-year, and the core CPI to be up 5.34% year-on-year. So, actual numbers came in slightly below those expectations
US Core CPI, YoY % change
- Breaking down the numbers, the decline in energy prices was largely behind the drop in the headline numbers in May, with energy commodities down 20.4% year-on-year
- The biggest drop in that sector was in fuel oil, which fell 37.0% year-on-year
- Electricity saw a 1% month-on-month decline in May
- Core CPI held up due to a 0.6% rise in commodities less food and energy, along with a 4.4% month-on-month increase in used cars and trucks, and 0.6% month-on-month increases for medical care commodities and for shelter
China-Arab trade deals
China signed deals worth $10 billion with Arab countries during its recent two-day Arab-China business conference. The largest, $5.6 billion, between Chinese electric car maker Human Horizons and Saudi Arabia’s investment ministry, aims to help Saudi Arabia to establish an EV manufacturing industry, including automotive research, manufacturing, and eventually selling EVs in Saudi Arabia.
This allows Chinese companies to build the infrastructure, and the electric vehicles, running new energy projects in the overseas market, thus taking pressure off struggling Chinese manufactures due to weaker demand from Western countries. It’s another example of how China is using its Belt and Road initiative to diversify away from the West while making participating countries more dependent on it. This is marginally disappointing for Tesla, Ford and GM, with increasing competition in foreign growth markets.
Analysis by Arlan Suderman, Chief Commodities Economist. [email protected].
Market outlook by Paul Walton, Financial Writer. [email protected].
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD Forecast: Euro Struggles to Find Support Even After U.S. PCE Data
The euro continues to face a challenging environment in the short term. The currency has struggled to regain ground against a U.S. dollar that remains firmly supported, a dynamic reflected in EUR/USD, which has now recorded three consecutive losing sessions and a decline of roughly 0.6%.


S&P 500 Forecast: SPX rises after cooler-than-expected inflation data
U.S. stocks are rising and Treasury yields are falling after data showed that inflation increased at a cooler pace than expected, while U.S. consumer spending rose again in August.


US Core PCE Preview: Stale or Significant for the Fed
Core PCE inflation takes center stage Wednesday, with traders watching for signs of renewed price pressure and clues on whether the Fed could hike again in October.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.