


Goldman Sachs Gets Bullish On Miners
A rebound in demand for commodities and particularly metals could result in a 30% rally in miners.
Share this:

Investment bank Goldman Sachs, has thrown its weight behind the mining sector, a sector which it believes will recover more quickly than other sectors in the FTSE thanks to rebounding commodity prices.
The mining sector has so far managed to avoid an extreme downturn to the levels last seen in 2008 or 2015, an encouraging sign, particularly given that some sectors in the UK index, such as the travel and tourism sector are experiencing their worst downturn ever.
Chinese metal demand ramps up
Increasing demand from China, the world’s largest consumer of metals is expected to support the sector. Recent data has revealed that the Chinese economy is starting to reignite, albeit slowly. Foreign demand remains weak; yet, as economies across the globe continue to reopen, demand is expected to start recovering.
Goldman Sachs also believe Beijing will use tried and tested measures of stimulating the Chinese economy. These measures are likely to include credit easing, in addition to boosting construction projects such as infrastructure and property, which are expected to be strong demand drivers in the second half of the year.
Metal prices jump
Goldman Sachs predicts that iron ore prices will remain elevated after reaching a fresh record high earlier in the week. Steel consumption in China is ramping up to record levels whilst concerns are growing over Brazilian supply amid the covid-19 outbreak. This is resulting in supportive supply demand fundamentals for a rising price.
Copper, which dropped sharply yestersay following the Fed’s gloomy outlook had just recovered losses for the year climbing 20% in just 3 months. Chinese demand is expected to limit any further downside. The metals are certainly in a very different position now than they were in March when the coronavirus lockdown was creating fears of a glut in the metals market.
Anglo American
The stock is up 36% in the past month, currently trading at 2250p. EBITDA has increased consistently since 2015. Costs have been successfully brought down, as have the number of mines being operated, although revenue has increased. Debt, which had been a big problem previously, is down too from $12.9 billion in 2015 to $4.4 billion
Anglo American had its price target raised by Goldman Sachs to 2300p from 2150p.
The stock continues to trade above its 50, 100 & 200 sma on bullish chart, despite 4% selloff yesterday.
BHP Billiton
Iron ore and copper are BHP Billiton’s biggest earners. In the 9 months to 31st March BHP Billiton had hit record production in iron ore. Copper is also a good earner of Billiton although less influential.
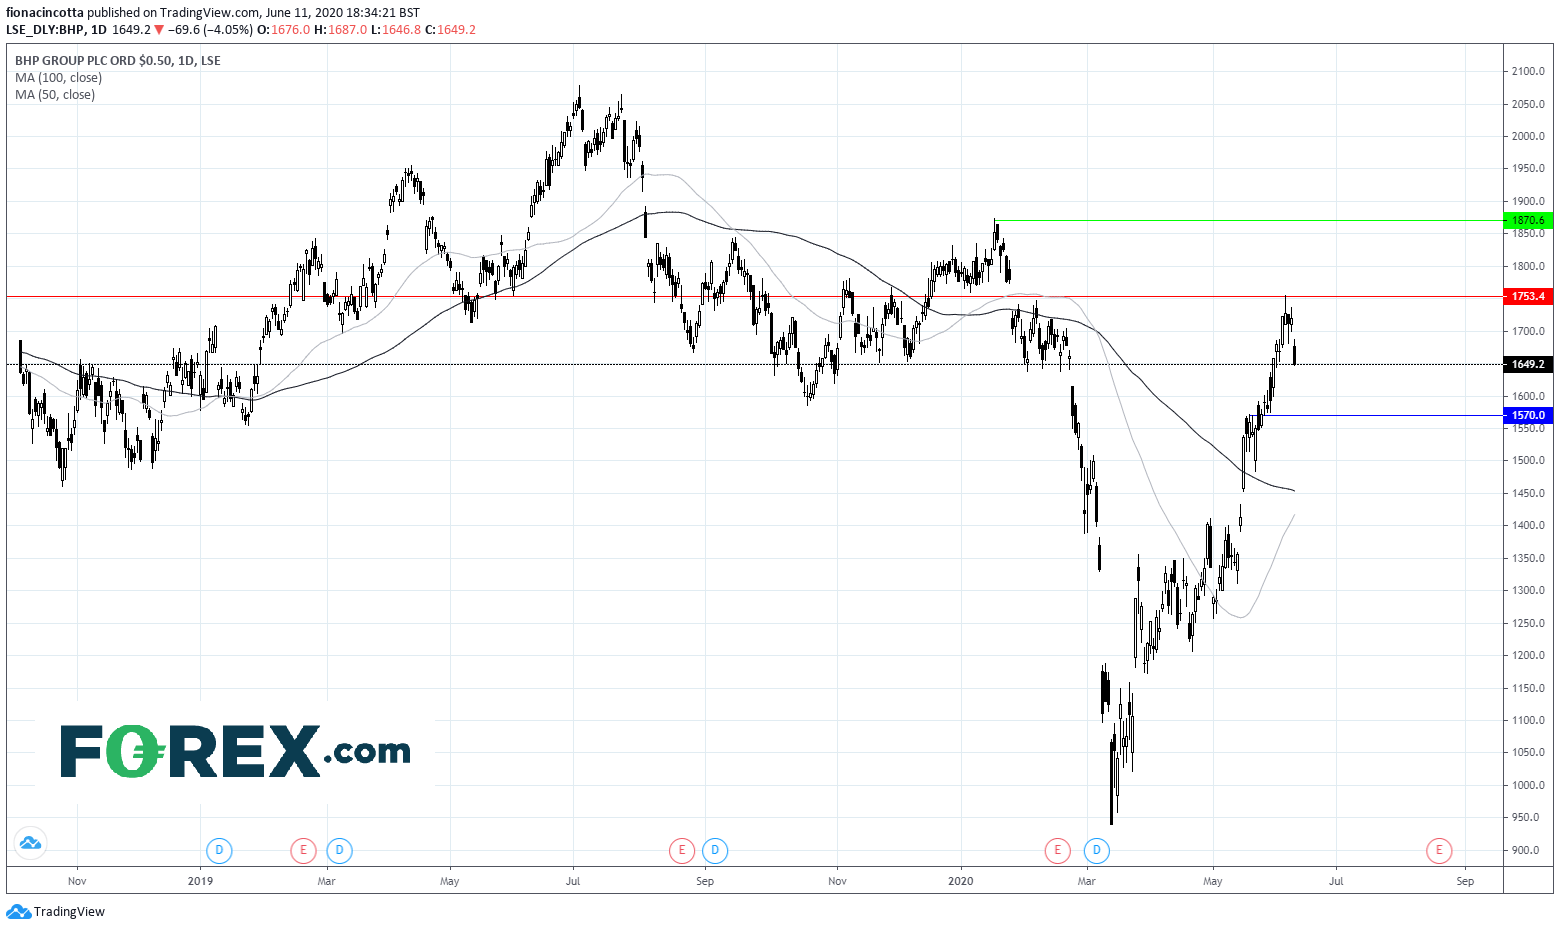
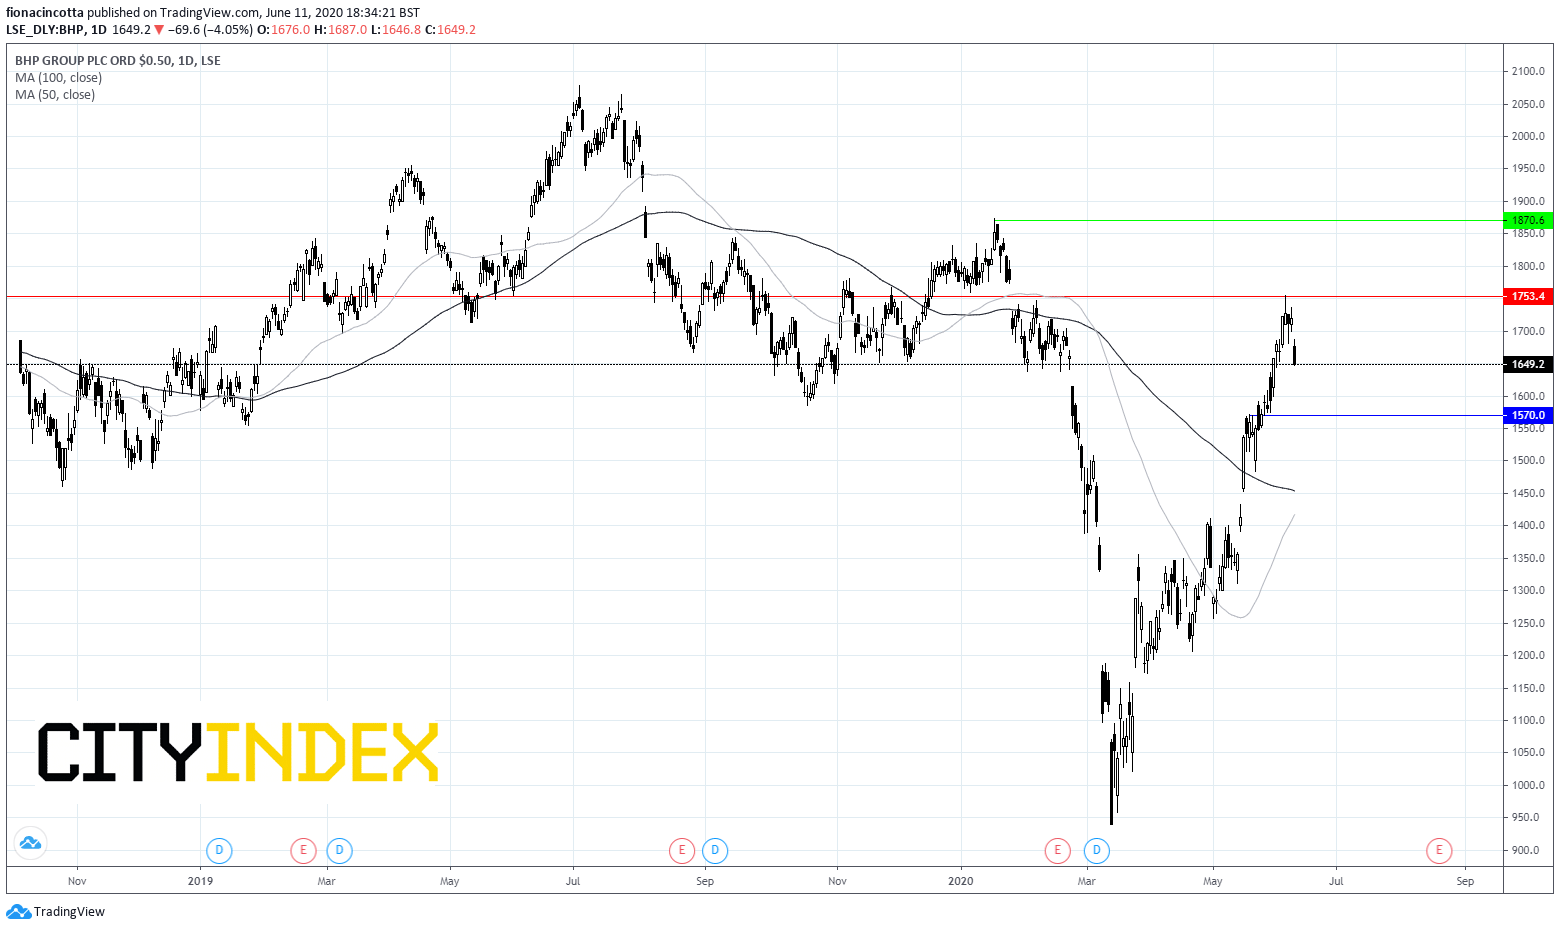
BHP Billiton’s rebound has been nothing short of impressive. The stock trades back close to levels last seen pre-covid-19. The stocks remains above its 50, 100 and 200 sma.
BHP Billiton’s price target was increased to 1750p from 1450p
Related tags:




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.