


Trump and China PMIs Overshadow US Riots
A softer tone from Trump combined with encouraging PMIs from China have resulted in rising risk sentiment at the start of the new week.
Share this:
Whilst riots and demonstrations in the US dominated the weekend headlines, the markets were more focused on President Trump’s speech on Friday. A softer tone from Trump combined with encouraging PMI’s from China have resulted in rising risk sentiment at the start of the new week. Traders are buying into riskier assets whilst rotating out of the safe haven US Dollar. Asian stocks pushed firmly higher overnight and European markets are set to follow suit.
It was more what Trump didn’t say in his speech on China that has boosted the mood this morning. Whilst Trump removed Hong Kong’s special trade status, as expected, he didn’t withdraw from the trade deal agreed in January and he didn’t apply any sanctions to Chinese officials or persons connected to the regime. Traders are breathing a sigh of relief.
China’s recovery in focus
Chinese Caixin manufacturing and non-manufacturing PMI’s have also been a source of optimism. Activity in the Chinese manufacturing sector jumped back into expansion territory in May, at 50.6. This was a tick below expectations of 50.7. Non-manufacturing PMI surprised to the upside, printing at 53.6 indicating the domestic demand continues to pick up after the coronvirus lockdown.
PMI data will remain firmly in focus with releases from UK, Europe and the US expected. The UK is expected to see the May reading is expected to remain close to the preliminary print of 40.6, at 40.7 still firmly in contraction. France and Germany are closed in observance of Whit Monday.
FTSE higher as lockdown measures eased further
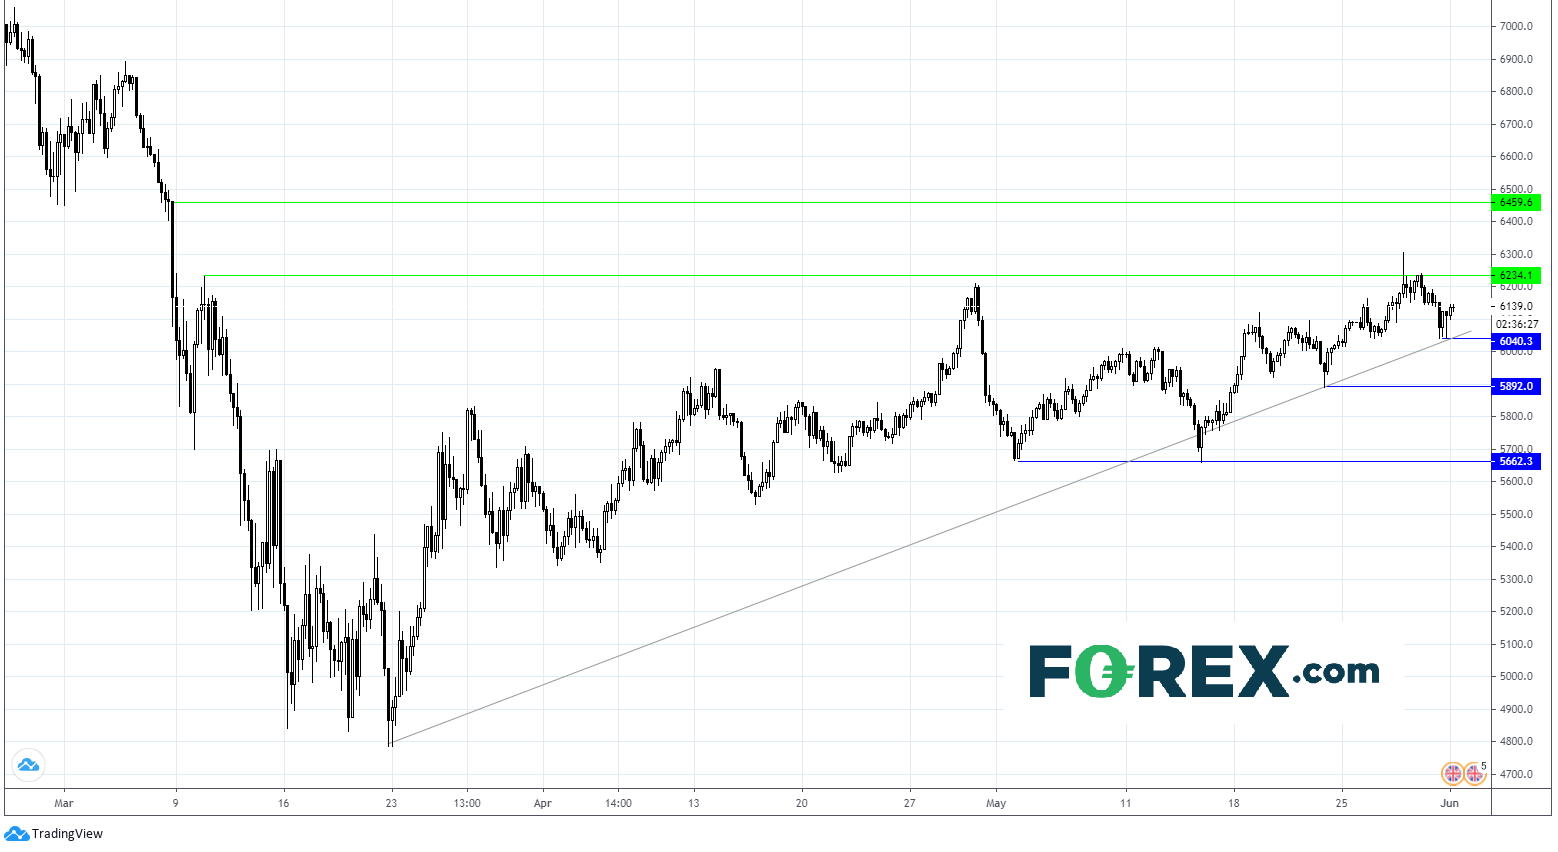
Optimum surrounding the reopening of economies continues to drive trading. Asian stock markets hit a three-month high as the post coronavirus recovery continues. Here in the UK, lower covid-19 infection rates and death rates have led Boris Johnson to ease lockdown restrictions further. Primary schools reopen today, people can meet in groups of 6 observing social distancing rules and some outside trading is also allowed to occur. Slowly the UK economy is reopening. Travel and tourism stocks, retailers, property and transport could once again find themselves the centre of bull’s attention.
Oil to target $40?
Oil is holding slipping mild lower on Monday after surging over 6.5% overnight in Asia. 10 weeks after the start of the coronavirus crisis, and a month after prices went negative, oil finally appears to by tracking a recovery, above $37.00. Demand is slowly increasing as fuel needs pick up with reopening economies. Supply is also supporting the pick-up in process as US rigs are being mothballed with an unprecedented urgency and as OPEC dropped production in May to the lowest level in two decades. The focus is now on OPEC and its next meeting, possibly as soon as this week to decide whether to extend the most recent cuts for another three months. Agreement to do so could see oil push above $40 per barrel.
FTSE Chart
Whilst riots and demonstrations in the US dominated the weekend headlines, the markets were more focused on President Trump’s speech on Friday. A softer tone from Trump combined with encouraging PMI’s from China have resulted in rising risk sentiment at the start of the new week. Traders are buying into riskier assets whilst rotating out of the safe haven US Dollar. Asian stocks pushed firmly higher overnight and European markets are set to follow suit.
It was more what Trump didn’t say in his speech on China that has boosted the mood this morning. Whilst Trump removed Hong Kong’s special trade status, as expected, he didn’t withdraw from the trade deal agreed in January and he didn’t apply any sanctions to Chinese officials or persons connected to the regime. Traders are breathing a sigh of relief.
China’s recovery in focus
Chinese Caixin manufacturing and non-manufacturing PMI’s have also been a source of optimism. Activity in the Chinese manufacturing sector jumped back into expansion territory in May, at 50.6. This was a tick below expectations of 50.7. Non-manufacturing PMI surprised to the upside, printing at 53.6 indicating the domestic demand continues to pick up after the coronvirus lockdown.
PMI data will remain firmly in focus with releases from UK, Europe and the US expected. The UK is expected to see the May reading is expected to remain close to the preliminary print of 40.6, at 40.7 still firmly in contraction. France and Germany are closed in observance of Whit Monday.
FTSE higher as lockdown measures eased further
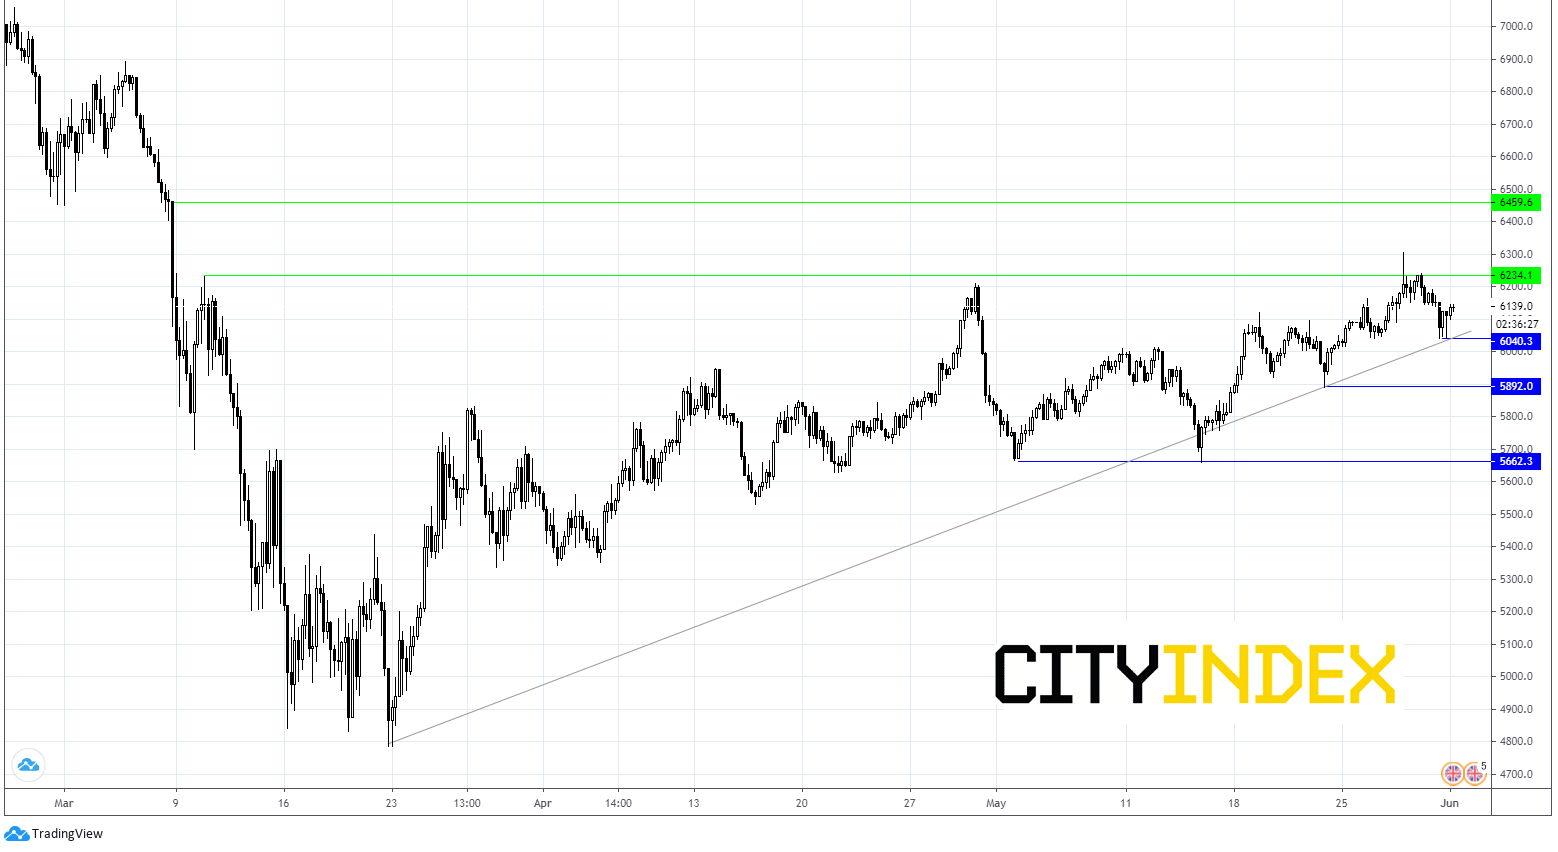
Optimum surrounding the reopening of economies continues to drive trading. Asian stock markets hit a three-month high as the post coronavirus recovery continues. Here in the UK, lower covid-19 infection rates and death rates have led Boris Johnson to ease lockdown restrictions further. Primary schools reopen today, people can meet in groups of 6 observing social distancing rules and some outside trading is also allowed to occur. Slowly the UK economy is reopening. Travel and tourism stocks, retailers, property and transport could once again find themselves the centre of bull’s attention.
Oil to target $40?
Oil is holding slipping mild lower on Monday after surging over 6.5% overnight in Asia. 10 weeks after the start of the coronavirus crisis, and a month after prices went negative, oil finally appears to by tracking a recovery, above $37.00. Demand is slowly increasing as fuel needs pick up with reopening economies. Supply is also supporting the pick-up in process as US rigs are being mothballed with an unprecedented urgency and as OPEC dropped production in May to the lowest level in two decades. The focus is now on OPEC and its next meeting, possibly as soon as this week to decide whether to extend the most recent cuts for another three months. Agreement to do so could see oil push above $40 per barrel.
FTSE Chart



Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
ASX 200 Rebound Stalls Despite Wall Street Surge
The ASX 200 rebound is struggling for traction despite a powerful Wall Street rally, leaving 8800 resistance and downside risks in focus.


Nikkei threatens breakout as tech rebound broadens
Breakouts across the SOX and Nasdaq are being matched by rebounds across Asia, with the Nikkei now threatening to join the move.


Nasdaq 100 Forecast: Confidence Returns as the Index Challenges Record Highs
The trading week is getting underway with renewed bullish momentum across Nasdaq. This is reflected in today's session, where the index has gained more than 2.5%, highlighting a buying bias that has not been observed with this level of strength in several weeks.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.