





DAX, FTSE Forecast: Two trades to watch
DAX falls as inflation rises & SAP drops. FTSE falls after disappointing China trade data.
Share this:

DAX falls as inflation rises & SAP drops
- German inflation rises to 2.2% YoY in November
- SAP falls on read-across from Oracle’s weakness
- DAX hovers around its all-time high
The DAX, along with its European peers, is heading lower following weaker-than-forecast Chinese import and export data and as investors weigh up German inflation data and a fall in SAP.
Shares in the German software company ASAP are trading lower following a read from Pier Oracle. The US-based Oracle's Q2 revenues grew less than expected, sending its showers shares over some cents lower in extended trade on Monday. SAP has gained 72% year to date and is at the bottom of the DAX I early trade.
Meanwhile, German inflation data confirmed the 2.2% reading in November, which is in line with the preliminary reading and up slightly from October's 2%. German core inflation was at 3% in November from 2.9% in the previous month.
The data comes ahead of US inflation figures tomorrow and ahead of the ECB interest rate decision on Thursday. The central bank is expected to cut rates by 25 basis points and could make .2 further rate cuts, given the deteriorating economic outlook for the region.
Despite that deteriorating economic outlook and ongoing political uncertainty, the DAX has pushed to record highs thanks to optimism surrounding ECB rate cuts.
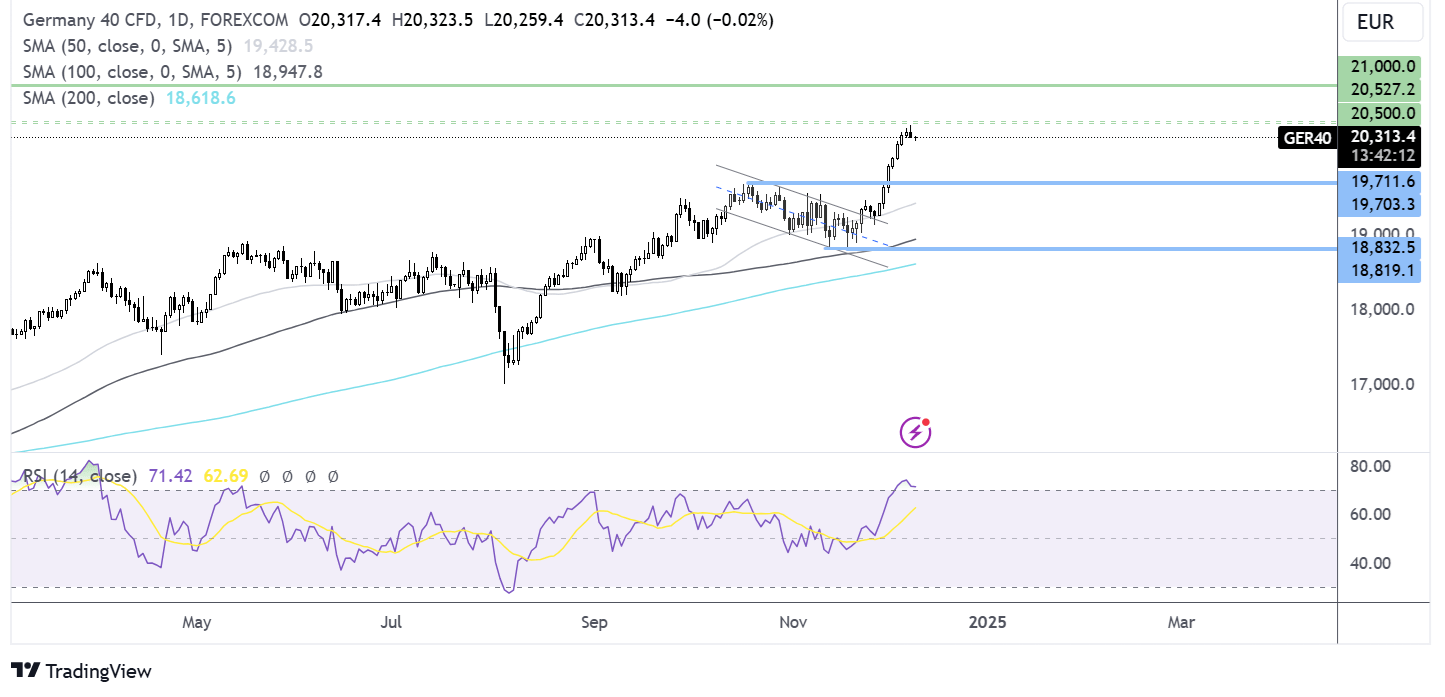
DAX forecast – technical analysis
After breaking out of its bull flag pattern, the DAX surged to record high of 20,474. The price has corrected slightly lower to current levels around 20,300, helping to lower the RSI, which was deep in overbought territory.
Buyers will look to extend gains above 20,474 towards 21k and fresh all-time highs.
There is little support until 20k, the psychological level of 19,670, the October high. A break below here negates the near-term uptrend.
FTSE falls after disappointing China trade data
- Miners fall as China imports fall -3.9% YoY
- Tesco rises after gaining market share
- FTSE tests upper band of channel at 8325
The Footsie has opened lower, with miners under pressure, and Chinese trade data disappointed. Figures from China show that exports grew 6.7% year on year to 312.3 billion, down sharply from October's 12.7% expansion and missing expectations of 8.5%.
On the import side, the picture was significantly more negative, with imports falling -3.9%, marking the steepest decline since September 2023 and missing expectations of a slight increase of 0.3%.
The data points to cooling demand for Chinese goods abroad as companies attempt to wean off their dependence on China ahead of any potential trade tariffs from incoming President Trump. Meanwhile, the import data points to weaker domestic demand despite stimulus measures to support the economy.
The data weighs heavily weighted resource stocks in the FTSE, with miners leading the index lower. It comes a day after the Chinese Political Bureau offered clear signals that more stimulus support is on the way. The China Central Economic Work Conference begins tomorrow and could provide more clues on what stimulus measures may be coming.
On a more positive not, Tesco is performing well. The UK supermarket saw sales in the 12 weeks to December 1 rise 5.2%, while increasing its market share to 28.1%, its highest since December 2017.
Meanwhile, data from Cantor also showed that grocery inflation rose to 2.6% in the four weeks to December 1, up from 2.3% in the previous four weeks.
UK supermarkets have warned that tax rises under the New Labour government along with the rising minimum wage will be inflationary.
FTSE forecast – technical analysis
The FTSE has traded range-bound since May, capped on the upside by 8325 and on the lower side by 8150. The price is attempting to break out of range testing the upper band, with a rise above here opening the door to 8400 and 8480 and fresh record highs.
Failure to rise above 8325 on a meaningful way could see the price head lower towards the 50 SMA at 8245 and 8150.
Related tags:




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

GBP/USD, Oil Forecast: Two trades to watch 300926
GBP/USD: Can Stronger UK Growth Offset the Dollar’s Advantage? Oil: Supply Recovery Challenges the Geopolitical Premium.

Oil, Gold Forecast: Two trades to watch 280926
Oil Rises as U.S.-Iran Peace Hopes Fade. Gold Breaks Down on Hawkish Fed Expectations as Treasury Yields and USD Rise.
Oil, USD/JPY Forecast: Two trades to watch
Oil recovers above $90 amid a lack of progress in US-Iran diplomacy. USD/JPY rises to 158 on widening Fed-BoJ policy outlook.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.