



Nasdaq 100 awaits the Magnificent Seven
The Nasdaq 100 is searching for its next catalyst. With Magnificent Seven earnings about to begin, attention now turns to whether results and guidance can justify the rally.
Share this:
- Key Magnificent Seven earnings dates to watch
- AI leadership faces its biggest earnings test
- History favours gains, but volatility remains
- Triangle pattern points to looming breakout
The Nasdaq 100 staged a breakneck rally from the lows struck in late March, leaving it sitting just beneath record highs. Since then, the price action has consolidated into what looks to be a symmetrical triangle. The question now is whether earnings season will provide the catalyst for a definitive breakout, and if so, in which direction.
With many of the index's largest constituents due to report over the coming weeks, investors will be watching not only the results themselves but, more importantly, whether guidance justifies the optimism priced into markets.
The countdown is on
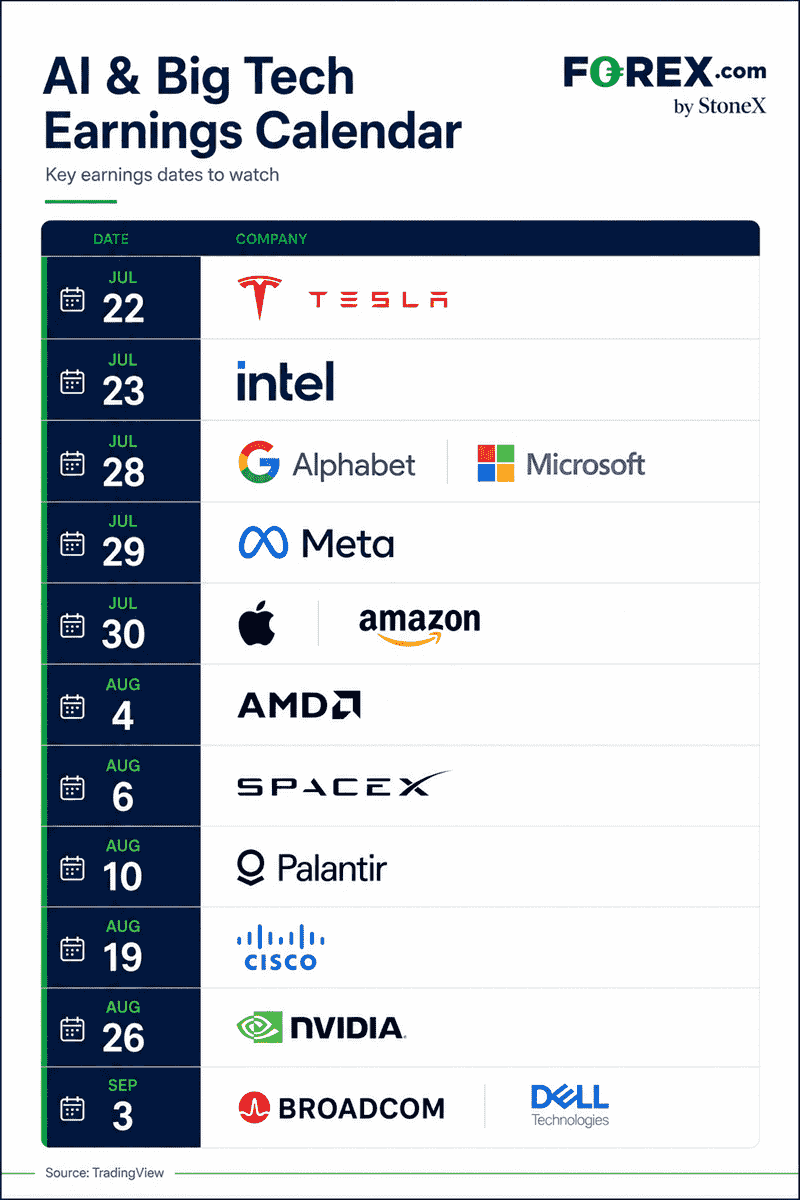
Reporting season for the Magnificent Seven gets underway with Tesla on July 22, before attention quickly shifts to the companies at the heart of the AI investment buildout. Alphabet and Microsoft report on July 28, followed by Meta a day later and Apple and Amazon on July 30. Semiconductor heavyweights AMD, Nvidia, Broadcom and Dell then round out the reporting season through early September.
Source: FOREX.com
AI leadership under the microscope
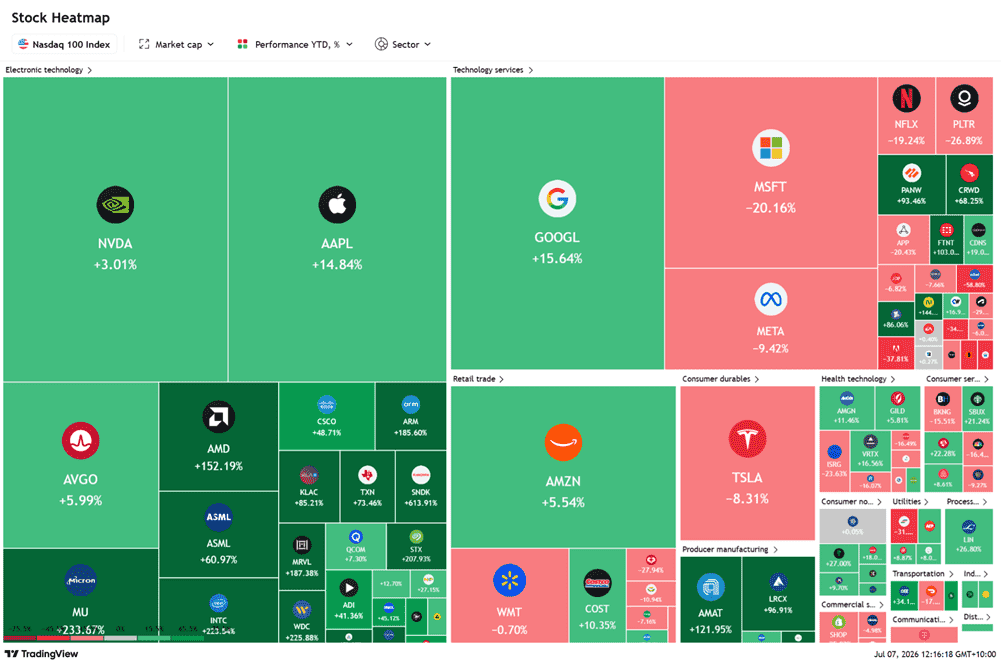
A glance at year-to-date performance of individual constituents highlights an interesting divergence. Companies supplying the AI ecosystem have comfortably outperformed the hyperscalers, reflecting rampant demand for chips, networking and data centre infrastructure. However, despite lagging, it will still be the Magnificent Seven that dictate directional risk for the Nasdaq 100. Their sheer size means their earnings and, more importantly, their guidance will carry far greater weight at the index level than almost any other group of companies.
Source: TradingView
The divergence also highlights one of the biggest questions surrounding earnings season. AI infrastructure suppliers may have outperformed, but as investment continues to accelerate, are they laying the foundations for future oversupply and margin pressure? If so, traders should be alert to the risk that hyperscalers may be preparing to moderate the pace of AI-related capital expenditure. That would mark a meaningful shift for a market that has been built on ever-increasing AI investment.
The odds favour the bulls
History suggests the period from mid-July through to the end of August has generally been bullish. Over the past decade, the index has posted an average gain of 2.49% during the period, with a median return of 2.48%. It finished higher in seven of the past 10 years.
However, context is important. The sample spans vastly different market regimes, including the pandemic, the subsequent surge in inflation and one of the most aggressive Federal Reserve tightening cycles in decades. Of note, two of the three negative years came when the Fed was either tightening policy or maintaining a restrictive stance. While the funds rate is lower today, the broader policy backdrop isn't entirely dissimilar. The Fed has dropped its easing bias, inflation remains above target and traders are pricing more than one full rate hike by the middle of next year. And that's before considering how hard the index has run into earnings.
It should also be remembered that earnings season is as much about expectations as it is results. While most companies exceed analyst forecasts, the bar for investors is often set far higher. When earnings fail to impress, the subsequent reaction can be carnage, helping explain the average maximum drawdown of 3.40% during the period. But when companies continue to clear the bar without any major negative earnings surprises, the index has also proved capable of delivering powerful gains, reflected in the average maximum rally of just over 5%.
Coiled beneath the highs
Source: TradingView
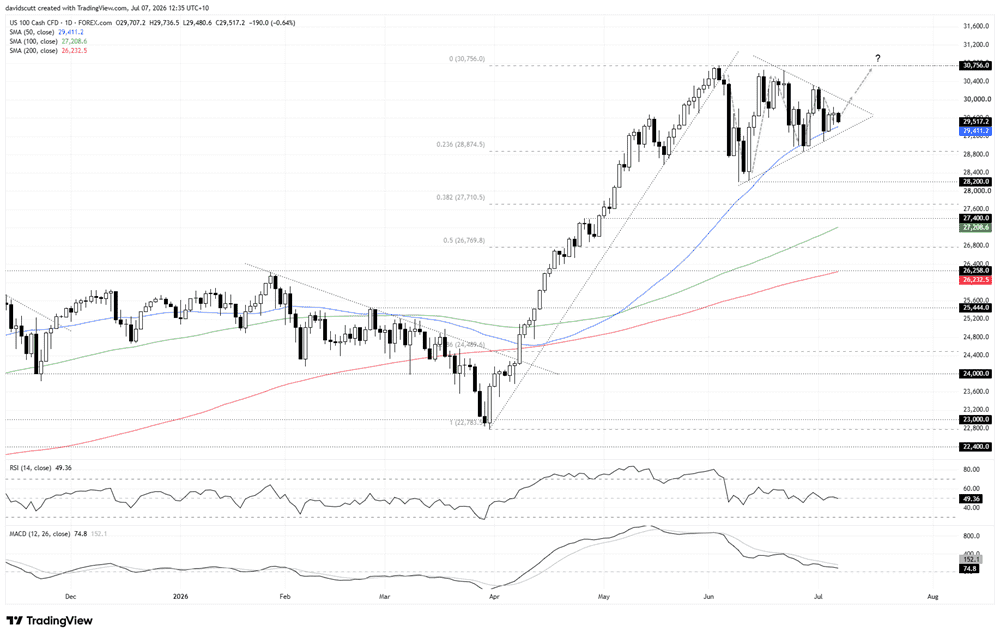
From a technical perspective, the price has spent the past month consolidating within what resembles a symmetrical triangle, leaving the price coiled just beneath record highs.
Momentum has shifted back to neutral, with RSI (14) drifting towards 50 while MACD sits beneath its signal line, albeit still in positive territory.
While symmetrical triangles imply two-way directional risk, the preceding trend provides important context. It follows a powerful rally that lifted the pric above its key medium and long-term moving averages, all of which continue to slope higher. More recently, every test of the rising 50-day moving average has been bought.
I suspect this is a consolidation of the earlier bull move that will ultimately give way to an upside breakout. If so, a sustained break above triangle resistance may pave the way for a retest of the record high at 30,756, and potentially fresh highs beyond.
For now, patience is warranted. I'd rather see price confirm that view with a sustained break of triangle resistance than try to anticipate the move beforehand.
Should my bias prove incorrect, the 23.6% Fibonacci retracement of the March-June bull move looms as the first downside level of note. Below that, the lower boundary of the triangle near 28,200 is the next area to watch.


The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Nasdaq 100 Forecast: NDX falls as oil jumps and Treasury yields rise
U.S. stocks are pointing to a weaker open on Monday after President Trump rejected an Iranian ceasefire, sending oil prices higher and fuelling inflationary concerns and pushing Treasury yields higher.

Gold Dips Below Three-Month Uptrend, Bitcoin Pulls Back from Nine-Month High
Gold has dipped below its three-month uptrend, while Bitcoin has pulled back from a nine-month high as U.S. bond yields test levels last seen in 2004 and 2007. Risks build as Fed rate-hike expectations remain above 70%, while the Dollar Index holds near yearly highs.


Crude Oil Q4 2026 Outlook: Will a New Energy-Security Regime Emerge?
Crude Oil Q4 2026 Outlook: The U.S.-Iran conflict has done more than disrupt oil flows. It has challenged many of the assumptions underpinning the global energy security system established after the 1973 oil embargo.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.