




Nasdaq 100 Forecast: QQQ muted on tariff relief optimism & weak data
US stocks are set to open mixed amid hopes for tariff negotiations and as investors look ahead to the ISM services PMI data. ADP payrolls were weaker than expected. Concerns over the outlook for the US economy are rising. Comments from US Commerce Secretary raised hopes that the trade tariffs could still be walked back and used as a negotiating tool by Trump.
Share this:
US futures
Dow future -0.12% at 42470
S&P futures -0.05% at 5773
Nasdaq futures 0.05% at 20357
In Europe
FTSE 0.33% at 8780
Dax 3.19% at 23030
- Hopes for tariff negotiations rise
- ISM services PMI data is due shortly
- ADP payrolls fall to 77k vs 140k forecast
- Oil falls to a 4-month low
Stocks mixed on trade tariff optimism & after weak ADP payrolls
US stocks are set to open mixed amid hopes for tariff negotiations and as investors look ahead to the ISM services PMI data.
Comments by US commerce secretary Howard Lutnick in a Fox Business interview suggested President Trump is still willing to negotiate regarding the newly imposed tariffs. Such a move could alleviate trade tensions, which escalated following the enforcement of 25% tariffs on imports from Canada and Mexico and an increase to 20% tariffs on Chinese goods.
However, it's worth pointing out that in his speech to Congress, Trump didn't appear to be adopting a softer position.
Attention will turn to services PMI data as recent economic figures have indicated a weakness in consumer sentiment, which could impact the all-important US services sector. The ISM services PMI is expected to show tick lower to 52.6 in February, down from 52.8. The date comes after the S&P Global Services PMI fell into contraction.
Meanwhile, US ADP payrolls dropped sharply in February to 77,000 jobs. This was below the 140,000 forecast and well down from the 180,000 in January. The data comes ahead of Friday's non-farm payroll report, which investors will watch closely for signs of economic cooling.
Corporate news
CrowdStrike is falling 7% pre-market after it guided Q1 revenue slightly below estimates amid weak spending on its products. CrowdStrike expects Q1 revenue between $1.10 billion and $1.11 billion, the midpoint of which is slightly below analysts' estimates of $1.11 billion. Revenues for 2026 are expected to be between $4.74 billion and $4.81 billion in line with estimates.
Campbell Soup is set to open over 5% lower after the food company lowered its annual sales and profit forecasts, indicating weak demand for snacks amid intense competition.
Automakers such as Ford, General Motors and Tesla are rising after logging sharp losses in the previous session. The rise comes on optimism that tariffs on Mexico and Canada could still be halted.
Nasdaq 100 forecast – technical analysis.
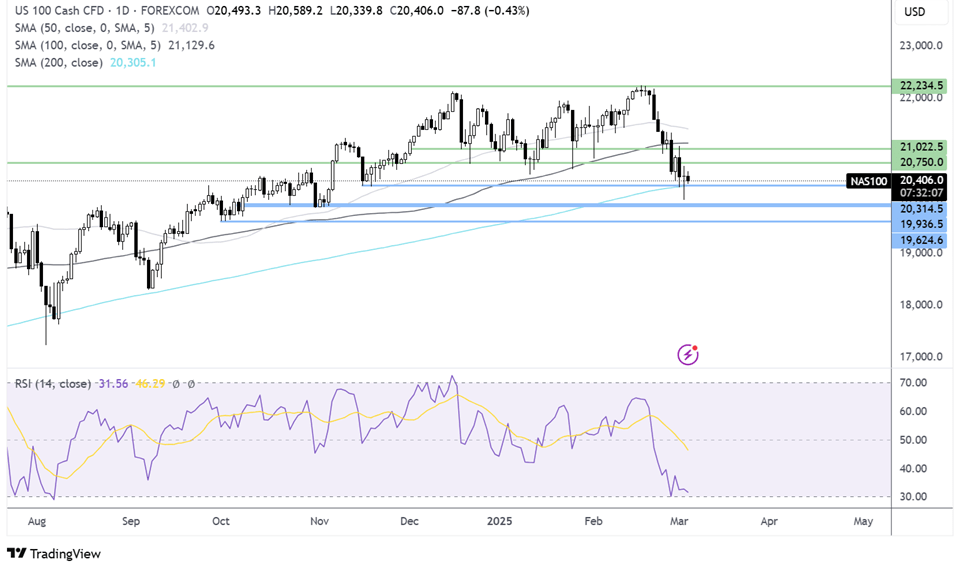
The Nasdaq continues to hold above its 200 SMA at 20,300 after a brief spike below it yesterday to around 20k. Sellers will need to close below the 200 SMA at to extend the bearish trend towards 20k. A break below here creates a lower low and could spark a deeper selloff towards 19625. Should the 200 SMA hold, buyers will look to rise above resistance at 20,750 to bring the price action back to a more neutral range.
FX markets – USD falls, EUR/USD rises
The USD is falling further amid rising concerns over the outlook for the economy. ADP payrolls are weaker than expected, and fears rise that trade tariffs and reciprocal tariffs could cause a downturn in the US economy.
EUR/USD has risen above 1.07 amid a weaker USD and a significant shift in German politics and policies. The next Chancellor, Friedrich Merz announced an agreement to change the constitutional fiscal debt brake to allow for higher defence spending. The reform to create a $500 billion infrastructure fund and eiden borrowing to increase defence spending will likely be inflatioinary.
GBP/USD has risen above 1.28, boosted by a weaker USD and ahead of BoE governor Andrew Bailey testimony before the Treasury Select Committee at 14:30 GMT. The central bank cut rates by 25 bps in February but warned that inflation could rise to 3.7% in Q3.
Oil falls to a 4-month low
Oil prices are falling for a fourth straight day as traders fretted over OPEC+ plans to release more supply into the market and Trump’s trade tariffs on Canada, Mexico, and China.
Oil has fallen to a multi-month low as OPEC+ is set to increase oil production next month. The steep selloff in the oil price suggests that the market was expecting the oil cartel to push back output increases again. The market would have expected a postponement because prices were already low and given the uncertainty surrounding the economic outlook and, therefore, the demand outlook in light of Trump’s trade tariffs.
Concerns are rising that the tariffs could cause a downturn in the US economy, lowering the demand outlook.




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Nasdaq 100 Forecast: NDX rises as oil eases and tech gains
U.S. stocks are heading higher on Tuesday, helped by a pullback in oil prices and after details about Anthropic's IPO boosted sentiment towards tech stocks.

Nasdaq 100 Forecast: NDX falls as oil jumps and Treasury yields rise
U.S. stocks are pointing to a weaker open on Monday after President Trump rejected an Iranian ceasefire, sending oil prices higher and fuelling inflationary concerns and pushing Treasury yields higher.

S&P 500, Nasdaq, Dow Forecast: Wall Street Split Widens Into Month-End 9 26 2026
Nasdaq strength contrasts with mounting Dow pressure as rising Treasury yields raise the stakes for stocks heading into the monthly close.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.