



Pattern Play Kinross Gold
Kinross Gold has broken out to the upside of a falling wedge pattern.
Share this:
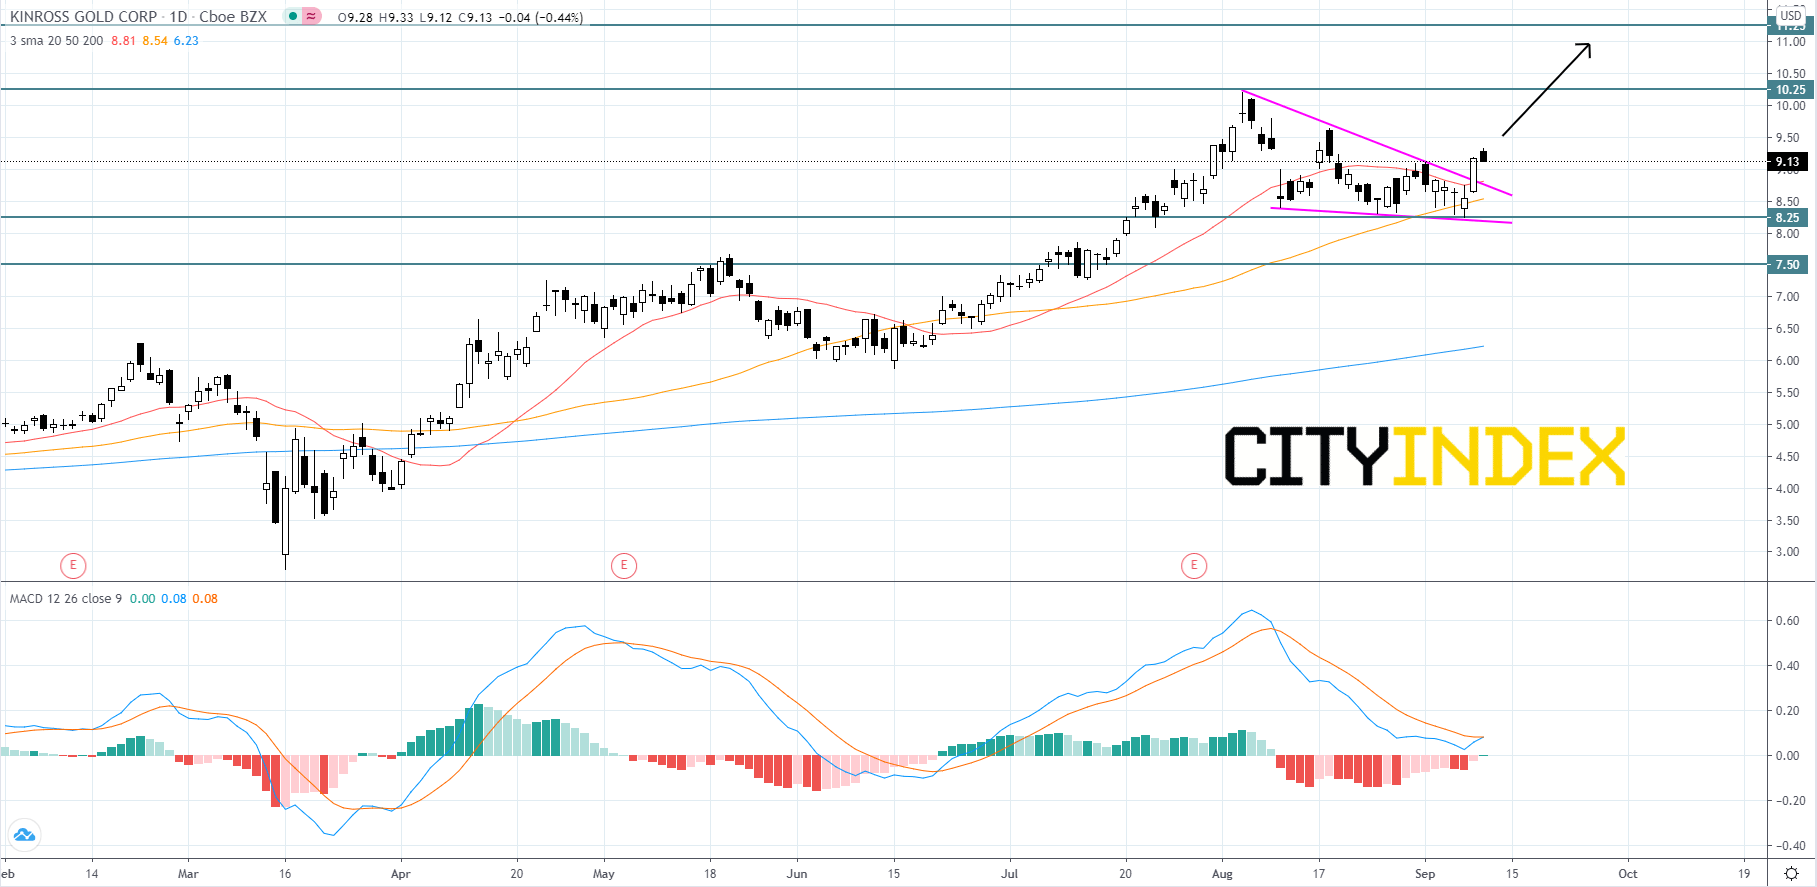
Kinross Gold (KGC), a Canadian based senior gold producer, broke out to the upside of a falling wedge pattern on Wednesday, September 9th. The breakout was confirmed after price closed above the upper trendline. The MACD line is beginning to turn up and appears to be on the verge of crossing above the signal line, a bullish indication. As a gold producer, Kinross's performance is intimately tied to the price of Gold, and Gold has an inverse relationship with the US Dollar Currency Index (DXY). On Wednesday, September 9th, the US Dollar Currency Index had its first red day after a 6 day rally. On Thursday, September 10th, the US Dollar Currency Index broke to the downside of a short-term bullish trendline that the Index was holding above.
Kinross's stock price has been in a long-term uptrend and a falling wedge is considered to be a continuation pattern. Price will likely resume its uptrend and advance to its 2020 high of roughly 10.25. If price can breakout above the 10.25 resistance level, then it should continue to rise to 11.25, a level last reached in 2012. As long as price holds above the upper trendline the bias should remain bullish. If price closes below the upper trendline of the falling wedge pattern then price may drop to the 8.25 support level, where it could possibly bounce. If price breaks below the 8.25 level, it would be a bearish signal and price could continue to fall to 7.50.
Source: GAIN Capital, TradingView
Kinross's stock price has been in a long-term uptrend and a falling wedge is considered to be a continuation pattern. Price will likely resume its uptrend and advance to its 2020 high of roughly 10.25. If price can breakout above the 10.25 resistance level, then it should continue to rise to 11.25, a level last reached in 2012. As long as price holds above the upper trendline the bias should remain bullish. If price closes below the upper trendline of the falling wedge pattern then price may drop to the 8.25 support level, where it could possibly bounce. If price breaks below the 8.25 level, it would be a bearish signal and price could continue to fall to 7.50.
Source: GAIN Capital, TradingView
Kinross Gold (KGC), a Canadian based senior gold producer, broke out to the upside of a falling wedge pattern on Wednesday, September 9th. The breakout was confirmed after price closed above the upper trendline. The MACD line is beginning to turn up and appears to be on the verge of crossing above the signal line, a bullish indication. As a gold producer, Kinross's performance is intimately tied to the price of Gold, and Gold has an inverse relationship with the US Dollar Currency Index (DXY). On Wednesday, September 9th, the US Dollar Currency Index had its first red day after a 6 day rally. On Thursday, September 10th, the US Dollar Currency Index broke to the downside of a short-term bullish trendline that the Index was holding above.
Kinross's stock price has been in a long-term uptrend and a falling wedge is considered to be a continuation pattern. Price will likely resume its uptrend and advance to its 2020 high of roughly 10.25. If price can breakout above the 10.25 resistance level, then it should continue to rise to 11.25, a level last reached in 2012. As long as price holds above the upper trendline the bias should remain bullish. If price closes below the upper trendline of the falling wedge pattern then price may drop to the 8.25 support level, where it could possibly bounce. If price breaks below the 8.25 level, it would be a bearish signal and price could continue to fall to 7.50.

Source: GAIN Capital, TradingView
Kinross's stock price has been in a long-term uptrend and a falling wedge is considered to be a continuation pattern. Price will likely resume its uptrend and advance to its 2020 high of roughly 10.25. If price can breakout above the 10.25 resistance level, then it should continue to rise to 11.25, a level last reached in 2012. As long as price holds above the upper trendline the bias should remain bullish. If price closes below the upper trendline of the falling wedge pattern then price may drop to the 8.25 support level, where it could possibly bounce. If price breaks below the 8.25 level, it would be a bearish signal and price could continue to fall to 7.50.
Source: GAIN Capital, TradingView
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Gold Q4 2026 outlook: Resilience in the face of rallying dollar and yields
As we headed towards the latter stages of Q3 and into Q4, the Fed had just hiked rates in a hawkish FOMC meeting, while the likes of the ECB and BoJ had also tightened their respective policies. Oil prices remained elevated amid the prolonged US-Iran conflict. Meanwhile, bond yields were breaking out, and the dollar was higher across the board. Yet, remarkably, gold was still holding in the positive territory for the third quarter, even if it had weakened somewhat in September.

Gold forecast: XAU/USD could take a larger dive after the big rise in yields
Gold prices have been falling in the last few days after last week’s post-FOMC pop faded amid rising interest rate expectations, higher oil prices and a strengthening US dollar. As before, I wasn’t convinced gold would thrive in the current macro backdrop.

Gold, silver slammed as hawkish Fed repricing reignites dollar upside
Gold and silver had held up surprisingly well against surging US yields. Wednesday’s DXY breakout may have changed that equation.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.