




The Fragile recovery continues PMIs in focus
PMIs to set the risk tone
Share this:
European markets opened higher as they continue the recovery from Monday’s sharp sell off. The risk tone in the market is showing some signs of improving, although pressure remains.
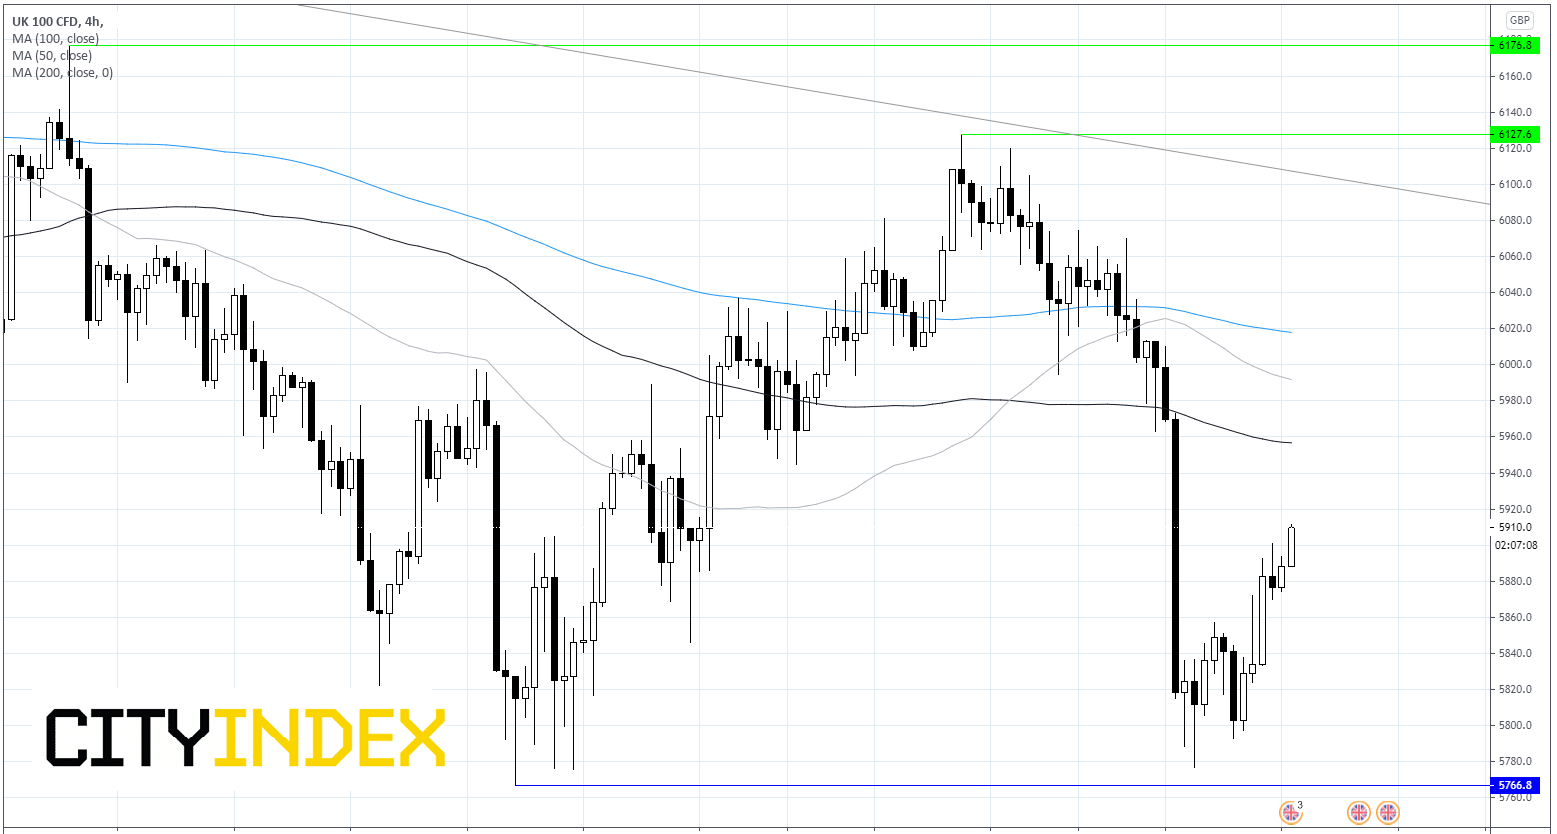
Stocks on the FTSE have reacted surprisingly well to Boris Johnson increased restrictions to stem the spread of coronavirus. The UK index closed yesterday on the front foot and is trading higher out of the blocks on Wednesday. The measures weren’t as drastic as some had feared which has offered some support to stock, particularly in the retail and hospitality sector.
Attention will now turn to September’s preliminary PMI readings for both the service and manufacturing sectors, for further clues over the health of the economic recovery in the UK. Expectations are for both sectors to show a slight slowing in expansion this month after solid performances in August.
The manufacturing PMI is forecast to dip to 54.3 in September, down from 55.2 in August. Meanwhile, the service sector is expected to tick lower to 56, down from 58.8. The level 50 separates expansion from contraction. A strong reading could help cement the so far fragile recovery in stocks. However, signs of weakness could damage an already vulnerable recovery.
The manufacturing PMI is forecast to dip to 54.3 in September, down from 55.2 in August. Meanwhile, the service sector is expected to tick lower to 56, down from 58.8. The level 50 separates expansion from contraction. A strong reading could help cement the so far fragile recovery in stocks. However, signs of weakness could damage an already vulnerable recovery.
Dollar hits 2 month high
The US Dollar is trading at 2 month highs, following surprisingly optimistic comments from Fed policy makers overnight. Fed Chair Jerome Powell said that the US economy stood resilient throughout the coronavir7is crisis whilst Fed official Charles Evans said that the US economy had returned to 90% of pre-pandemic levels, adding that the Fed could raise interest rates before the 2% average inflation target is reached.
The US Dollar is trading at 2 month highs, following surprisingly optimistic comments from Fed policy makers overnight. Fed Chair Jerome Powell said that the US economy stood resilient throughout the coronavir7is crisis whilst Fed official Charles Evans said that the US economy had returned to 90% of pre-pandemic levels, adding that the Fed could raise interest rates before the 2% average inflation target is reached.
USD drags on gold
The stronger US Dollar is pilling pressure on gold. The precious metal is trading lower for the third straight session, as it homes in on the weekly low of $1882. The next move for the precious metal depends largely on the PMI readings and how they impact the risk tone in the market.
The stronger US Dollar is pilling pressure on gold. The precious metal is trading lower for the third straight session, as it homes in on the weekly low of $1882. The next move for the precious metal depends largely on the PMI readings and how they impact the risk tone in the market.
Oil under pressure ahead of EIA data
Oil is also trading on the back foot, paring gains from the previous session. Both oil contracts experienced a 4% sell off at the start of the week. With coronavirus cases rising, particularly sharply in Europe and increasing restrictions in the UK the demand outlook for oil is souring; and it is doing so just as more supply is set to come into the market from Libya. Crude inventories rise by 691,000 barrels in the week ending 18th September, compared to a drop of 2.3 million forecast by analysts. EIA data is due later today and could take on greater importance than usual. Should we see another surprise jump in inventories this could be enough to spark another leg lower for crude.
FTSE Chart
European markets opened higher as they continue the recovery from Monday’s sharp sell off. The risk tone in the market is showing some signs of improving, although pressure remains.
Stocks on the FTSE have reacted surprisingly well to Boris Johnson increased restrictions to stem the spread of coronavirus. The UK index closed yesterday on the front foot and is trading higher out of the blocks on Wednesday. The measures weren’t as drastic as some had feared which has offered some support to stock, particularly in the retail and hospitality sector.
Attention will now turn to September’s preliminary PMI readings for both the service and manufacturing sectors, for further clues over the health of the economic recovery in the UK. Expectations are for both sectors to show a slight slowing in expansion this month after solid performances in August.
The manufacturing PMI is forecast to dip to 54.3 in September, down from 55.2 in August. Meanwhile, the service sector is expected to tick lower to 56, down from 58.8. The level 50 separates expansion from contraction. A strong reading could help cement the so far fragile recovery in stocks. However, signs of weakness could damage an already vulnerable recovery.
The manufacturing PMI is forecast to dip to 54.3 in September, down from 55.2 in August. Meanwhile, the service sector is expected to tick lower to 56, down from 58.8. The level 50 separates expansion from contraction. A strong reading could help cement the so far fragile recovery in stocks. However, signs of weakness could damage an already vulnerable recovery.
Dollar hits 2 month high
The US Dollar is trading at 2 month highs, following surprisingly optimistic comments from Fed policy makers overnight. Fed Chair Jerome Powell said that the US economy stood resilient throughout the coronavir7is crisis whilst Fed official Charles Evans said that the US economy had returned to 90% of pre-pandemic levels, adding that the Fed could raise interest rates before the 2% average inflation target is reached.
The US Dollar is trading at 2 month highs, following surprisingly optimistic comments from Fed policy makers overnight. Fed Chair Jerome Powell said that the US economy stood resilient throughout the coronavir7is crisis whilst Fed official Charles Evans said that the US economy had returned to 90% of pre-pandemic levels, adding that the Fed could raise interest rates before the 2% average inflation target is reached.
USD drags on gold
The stronger US Dollar is pilling pressure on gold. The precious metal is trading lower for the third straight session, as it homes in on the weekly low of $1882. The next move for the precious metal depends largely on the PMI readings and how they impact the risk tone in the market.
The stronger US Dollar is pilling pressure on gold. The precious metal is trading lower for the third straight session, as it homes in on the weekly low of $1882. The next move for the precious metal depends largely on the PMI readings and how they impact the risk tone in the market.
Oil under pressure ahead of EIA data
Oil is also trading on the back foot, paring gains from the previous session. Both oil contracts experienced a 4% sell off at the start of the week. With coronavirus cases rising, particularly sharply in Europe and increasing restrictions in the UK the demand outlook for oil is souring; and it is doing so just as more supply is set to come into the market from Libya. Crude inventories rise by 691,000 barrels in the week ending 18th September, compared to a drop of 2.3 million forecast by analysts. EIA data is due later today and could take on greater importance than usual. Should we see another surprise jump in inventories this could be enough to spark another leg lower for crude.
FTSE Chart
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.