



US open: Stocks point modestly lower after a Powell inspired rally
Stocks edge lower after strong gains yesterday's following Fed Powell's not as hawkish as feared speech. Disney earnings are due later and more Fed speakers are on tap.
Share this:

US futures
Dow futures -0.33% at 34050
S&P futures -0.41% at 41147
Nasdaq futures -0.26% at 12706
In Europe
FTSE +0.71% at 7918
Dax +0.75% at 15413
Biden’s State of the Union address
US stocks are edging lower, correcting modestly after a Powell-inspired rally in the previous session.
The Nasdaq closed almost 2% higher on Tuesday after Powell decided against upping the hawkish rhetoric following Friday’s blowout jobs report. The Fed Chair acknowledged that interest rates would need to keep climbing if data kept coming in ahead of forecasts. However, he also said that 2023 is expected to see a significant fall in inflation.
Biden’s State of the Union speech covered ground politically, but there was little in there for the markets. A proposal for quadrupling the 1% tax on stock buybacks is likely to garner some interest as well as a pledge to take a strong line against China less than a week after the spy balloon incident.
Attention will shift towards comments from more Federal Reserve policymakers with speeches from New York fed president John Williams Atlanta fed president Bostic and Minneapolis Fed president Neal Kashkari. Investors will be watching closely for clues over whether the US central bank is getting close to pausing its rate hikes cycle.
Company earnings will again be in focus more than half of the SNP 500 companies have reported quarterly earnings with over 69% beating expectations.
Corporate news
Uber jumps pre-market after a blowout end to 2022 and with the promise of delivering a profit this year. Uber revenue rose 49% to $8.61 in Q4 besting estimates of $8.49 billion. Rideshare revenue surged 82%. Net loss was $0.29c per share compared to $0.44c a year earlier.
Disney is due to report after the close. These will be the first earnings after the return of Bog Iger and Wall Street is expecting a rebound in earnings of $0.80c per share after a sharp decline to $0.30 in the three months to September. Ongoing recoveries in the theme park and entertainment businesses are expected.
Where next for the Dow Jones?
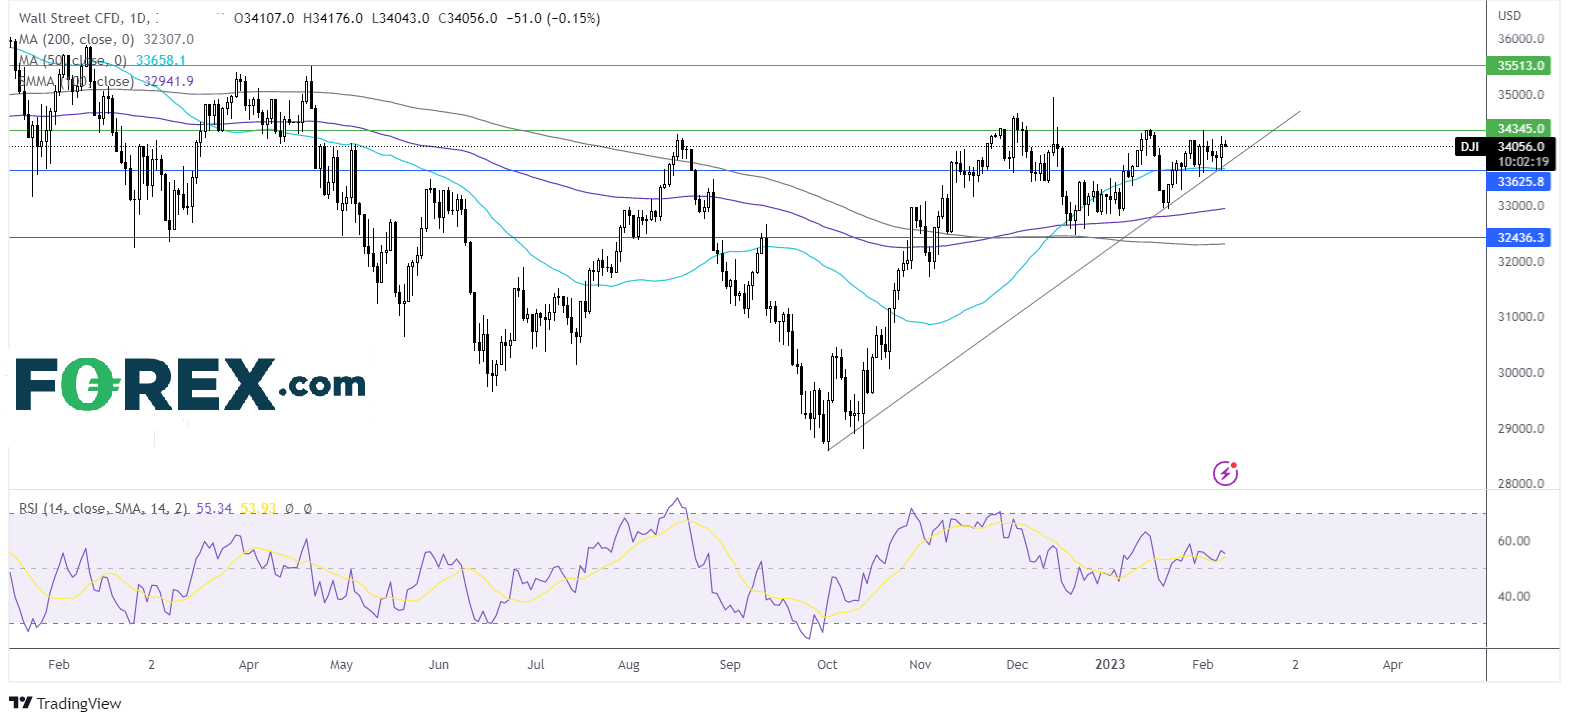
Dow Jones continues to trade above its multi-month rising trendline, however, it has failed to push over resistance at 34350. The resultant ascending triangle is a bullish formation, which, together with the RSI above 50 keeps buyers hopeful of further upside. A rise above 34350 could see buyers look to 34650 the November high, ahead of 34950 the December high. On the flipside, a break below 33650 the 50 sma, yesterday’s low and the rising trendline support exposes the 100 sma just below 33000.
FX markets – USD falls, GBP rises
The USD is falling, extending losses from yesterday after a less hawkish-than-feared speech from Fed Chairman Jerome Powell.
GBP/USD is 121 after think tank NIESR forecast that Britain was now likely to avoid a technical recession of two consecutive quarters of negative growth. Easing recession fears have boosted the pound, which had fallen over 2.8% last week.
EUR/USD is edging higher, snapping a four-day losing run and capitalising on the weaker U.S. dollar. The eurozone economic calendar is quiet today. Investors will look ahead to German inflation data due tomorrow.
GBP/USD +0.4% at 1.2093
EUR/USD +0.15% at 1.0737
Oil rises as recession fears ease
Oil prices are rising for a fourth straight session, helped higher by easing recession fears, a weaker U.S. dollar, and a surprise draw in API oil inventory data.
Comments from Federal Reserve chair Jeremy Powell on Tuesday were considered less hawkish than feared, boosting risk appetite and pulling the dollar lower. A weaker dollar means that oil is cheaper for buyers with other currencies.
less aggressive US rate hikes expected means there is growing optimism that the world’s largest consumer of oil can avoid a recession.
Meanwhile, API data stockpiles fell by 2.2 million barrels in the week ending February 3rd. Investors will now look ahead to the EIA oil inventory data which is expected to show a 2.45 million barrel build.
WTI crude trades +1.0% at $78.07
Brent trades at +0.8% at $84.23
Looking ahead
N/A
US futures
Dow futures -0.33% at 34050
S&P futures -0.41% at 41147
Nasdaq futures -0.26% at 12706
In Europe
FTSE +0.71% at 7918
Dax +0.75% at 15413
Learn more about trading indices
Biden’s State of the Union address
US stocks are edging lower, correcting modestly after a Powell-inspired rally in the previous session.
The Nasdaq closed almost 2% higher on Tuesday after Powell decided against upping the hawkish rhetoric following Friday’s blowout jobs report. The Fed Chair acknowledged that interest rates would need to keep climbing if data kept coming in ahead of forecasts. However, he also said that 2023 is expected to see a significant fall in inflation.
Biden’s State of the Union speech covered ground politically, but there was little in there for the markets. A proposal for quadrupling the 1% tax on stock buybacks is likely to garner some interest as well as a pledge to take a strong line against China less than a week after the spy balloon incident.
Attention will shift towards comments from more Federal Reserve policymakers with speeches from New York fed president John Williams Atlanta fed president Bostic and Minneapolis Fed president Neal Kashkari. Investors will be watching closely for clues over whether the US central bank is getting close to pausing its rate hikes cycle.
Company earnings will again be in focus more than half of the SNP 500 companies have reported quarterly earnings with over 69% beating expectations.
Corporate news
Uber jumps pre-market after a blowout end to 2022 and with the promise of delivering a profit this year. Uber revenue rose 49% to $8.61 in Q4 besting estimates of $8.49 billion. Rideshare revenue surged 82%. Net loss was $0.29c per share compared to $0.44c a year earlier.
Disney is due to report after the close. These will be the first earnings after the return of Bog Iger and Wall Street is expecting a rebound in earnings of $0.80c per share after a sharp decline to $0.30 in the three months to September. Ongoing recoveries in the theme park and entertainment businesses are expected.
Where next for the Dow Jones?
Dow Jones continues to trade above its multi-month rising trendline, however, it has failed to push over resistance at 34350. The resultant ascending triangle is a bullish formation, which, together with the RSI above 50 keeps buyers hopeful of further upside. A rise above 34350 could see buyers look to 34650 the November high, ahead of 34950 the December high. On the flipside, a break below 33650 the 50 sma, yesterday’s low and the rising trendline support exposes the 100 sma just below 33000.

FX markets – USD falls, GBP rises
The USD is falling, extending losses from yesterday after a less hawkish-than-feared speech from Fed Chairman Jerome Powell.
GBP/USD is 121 after think tank NIESR forecast that Britain was now likely to avoid a technical recession of two consecutive quarters of negative growth. Easing recession fears have boosted the pound, which had fallen over 2.8% last week.
EUR/USD is edging higher, snapping a four-day losing run and capitalising on the weaker U.S. dollar. The eurozone economic calendar is quiet today. Investors will look ahead to German inflation data due tomorrow.
GBP/USD +0.4% at 1.2093
EUR/USD +0.15% at 1.0737
Oil rises as recession fears ease
Oil prices are rising for a fourth straight session, helped higher by easing recession fears, a weaker U.S. dollar, and a surprise draw in API oil inventory data.
Comments from Federal Reserve chair Jeremy Powell on Tuesday were considered less hawkish than feared, boosting risk appetite and pulling the dollar lower. A weaker dollar means that oil is cheaper for buyers with other currencies.
less aggressive US rate hikes expected means there is growing optimism that the world’s largest consumer of oil can avoid a recession.
Meanwhile, API data stockpiles fell by 2.2 million barrels in the week ending February 3rd. Investors will now look ahead to the EIA oil inventory data which is expected to show a 2.45 million barrel build.
WTI crude trades +1.0% at $78.07
Brent trades at +0.8% at $84.23
Learn more about trading oil here.
Looking ahead
N/A
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Equity Indices Q4, 2026 Outlook: Cracks Begin to Show
There's still an open door for a melt-up in the S&P 500 and Nasdaq but the Dow and Russell 2000 are looking more vulnerable, and until calm hits the Treasuries market there's a higher probability for volatility. The big question is whether that's a next quarter theme or not.


GBP/USD, DJIA Outlook: Support Levels Meet Oversold Risks
GBP/USD and the Dow test key support levels as rising Treasury yields, Fed rate-hike expectations and oversold momentum increase reversal risks.

Dow Jones Forecast: DJIA jumps despite a hawkish Fed hike
U.S. stocks have opened higher, following a two-day slide, as lower oil prices and falling Treasury yields have brought some relief after the Federal Reserve's interest rate decision.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.