


Antipodean double header next test for AUDNZD
With the dust still settling on last night’s red-hot U.S inflation data, attention locally will turn to an Antipodean doubleheader tomorrow in the shape of Q2 NZ GDP and the Australian August labour force report.
Share this:
With the dust still settling on last night’s red-hot U.S inflation data, attention locally will turn to an Antipodean doubleheader tomorrow in the shape of Q2 NZ GDP and the Australian August labour force report.
While neither of the data points is likely to cause the magnitude of reaction seen today, both have a role to play in the narrative around the speed of policy tightening by the RBNZ and RBA.
As well as having a say on whether AUDNZD currently trading at almost five-year highs can continue higher.
Q2 New Zealand GDP data is due to drop at 8.45 am Sydney time. Following a 0.2% contraction in Q1 as Omicron ripped through the country, the reopening of international borders that has seen the resumption of overseas tourists and students is expected to see a 1.6% rise in Q2.
Despite the rapid cooling in the housing market, high inflation is expected to see the RBNZ continue to hike rates from 3% to 3.75% by November.
The Australian labour force report for August, due at 11.30 am Sydney time tomorrow, is expected to see a 50k rise in employment and for the unemployment rate to hold at a record low of 3.4%, and the participation rate to rise to 66.7%.
The strong jobs market was likely behind a lift in consumer confidence yesterday and supported by lower petrol prices and the shock value of aggressive RBA rate hikes wearing off.
In this case, there is no reason for the RBA not to continue tightening further into the restrictive territory into yearend to tame spiralling inflation and to cool a tight labour market. The market sees the cash rate ending the year near 3.35%.
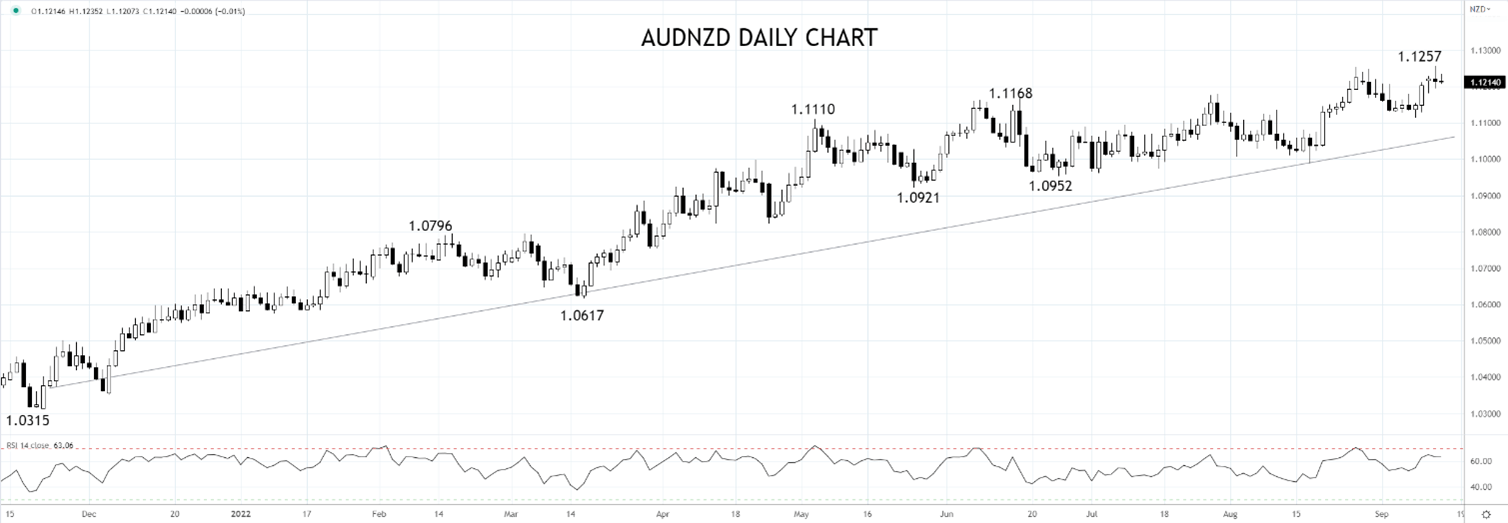
Turning to the cross rate, AUDNZD is currently eyeing the 1.1290 high of 2017, supported by buoyant energy and commodity prices, which have kept Australia’s Terms of Trade at record highs despite the slow down in China.
While the rally does look a little overbought in the short term, should AUDNZD see a sustained break of 1.1290, look for the rally to extend towards the August 2015 1.1472 high.
Source Tradingview. The figures stated are as of September 14th, 2022. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
With the dust still settling on last night’s red-hot U.S inflation data, attention locally will turn to an Antipodean doubleheader tomorrow in the shape of Q2 NZ GDP and the Australian August labour force report.
While neither of the data points is likely to cause the magnitude of reaction seen today, both have a role to play in the narrative around the speed of policy tightening by the RBNZ and RBA.
As well as having a say on whether AUDNZD currently trading at almost five-year highs can continue higher.
Q2 New Zealand GDP data is due to drop at 8.45 am Sydney time. Following a 0.2% contraction in Q1 as Omicron ripped through the country, the reopening of international borders that has seen the resumption of overseas tourists and students is expected to see a 1.6% rise in Q2.
Despite the rapid cooling in the housing market, high inflation is expected to see the RBNZ continue to hike rates from 3% to 3.75% by November.
The Australian labour force report for August, due at 11.30 am Sydney time tomorrow, is expected to see a 50k rise in employment and for the unemployment rate to hold at a record low of 3.4%, and the participation rate to rise to 66.7%.
The strong jobs market was likely behind a lift in consumer confidence yesterday and supported by lower petrol prices and the shock value of aggressive RBA rate hikes wearing off.
In this case, there is no reason for the RBA not to continue tightening further into the restrictive territory into yearend to tame spiralling inflation and to cool a tight labour market. The market sees the cash rate ending the year near 3.35%.
Turning to the cross rate, AUDNZD is currently eyeing the 1.1290 high of 2017, supported by buoyant energy and commodity prices, which have kept Australia’s Terms of Trade at record highs despite the slow down in China.
While the rally does look a little overbought in the short term, should AUDNZD see a sustained break of 1.1290, look for the rally to extend towards the August 2015 1.1472 high.
Related tags:
Latest market news




Open an account today
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
British Pound Short-term Outlook: GBP/USD 3% Plunge Hits 12-Month Low—Key Support in Focus 11 19 2026
Sterling’s October rebound has unraveled, leaving GBP/USD bears in control—but stretched momentum raises the stakes for the weekly close

Nasdaq 100 forecast: Markets turn jittery as Anthropic debuts at 34% above IPO
Nasdaq futures were up some 2% earlier, but shortly after the Anthropic debut, the index slumped to session lows, down more than 1.5%, before bouncing back from the lows at the time of writing. Much of the selling for the Nasdaq was driven by AMD which slumped nearly 10% after a Hunterbrook Media report raised fresh questions about the company’s exposure to US export controls on China.


Australian Dollar Technical Outlook: AUD/USD 6% Plunge Tests Make-or-Break Support at Yearly Low 11 19 2026
AUD/USD’s four-week decline is testing critical support, with a decisive break below this threshold needed to fuel the next major leg lower.
From time to time, StoneX Financial Pty Ltd (“we”, “our”) website may contain links to other sites and/or resources provided by third parties. These links and/or resources are provided for your information only and we have no control over the contents of those materials, and in no way endorse their content. Any analysis, opinion, commentary or research-based material on our website is for information and educational purposes only and is not, in any circumstances, intended to be an offer, recommendation or solicitation to buy or sell. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. No representation or warranty is made, express or implied, that the materials on our website are complete or accurate. We are not under any obligation to update any such material.
As such, we (and/or our associated companies) will not be responsible or liable for any loss or damage incurred by you or any third party arising out of, or in connection with, any use of the information on our website (other than with regards to any duty or liability that we are unable to limit or exclude by law or under the applicable regulatory system) and any such liability is hereby expressly disclaimed.