Market Overview
The Nasdaq 100 and S&P 500 ended yesterday's hectic session up, but the Dow Jones and Russell 2000 are still down. The DAX closed down in yesterday's trading session, but opened up with a current gain of 0.35%.
We also had the expected presidential debate, which took place overnight for us here in Europe. Many opinions were expressed by traders on the outcome, but Kamala Harris and Donald Trump remained unchanged at the top of the race.
The most important event this week is today's US inflation report, the CPI, which will show us how much the economy is being slowed down. This is the last inflation report before the FED's interest rate decision next week. In this respect, this report could have the opportunity to influence the extent to which the FED will lower interest rates next week.
I have written more about this in this article: (https://www.forex.com/ie/news-and-analysis/us-cpi-countdown-how-septembers-report-could-shape-economic-policy/)
Monthly price increases are expected to remain moderate and continue to slow year-on-year. UK GDP did not rise by 0.2% in July as expected, but remained at 0.0%.
Corporate news
To avert a possible strike, Boeing has offered unionised employees additional benefits and a 25 per cent wage increase.
With new AI features, Apple introduced its iPhone 16 range; however, after previous losses, shares closed almost unchanged. In addition, Apple was ordered by the EU to refund 13 billion euros in overdue taxes.
Oracle's first-quarter revenue of $13.31 billion exceeded expectations of 8% year-on-year, leading to a 9% rise in shares.
Ahead of its Tuesday launch, Huawei said it had 3 million pre-orders for its new triple-foldable smartphone, posing a threat to Apple in China.
Brian Niccol, the new CEO of Starbucks, started his first day on the job.
The US government is targeting Google over its Google Ads division, which accounted for around 78% of the company's revenue in 2023. Google's Ads division could be split off if the Department of Justice gets its way again, which would have a significant impact on the company's profits.
Among the S&P 500, Palantir and Dell are two newcomers to the index. American Airlines and Etsy have left the S&P 500.
On the agenda for Wednesday 11 September – London Time
13:30 USD core CPI (MoM) (Aug)
13:30 USD core CPI (YoY) (Aug)
13:30 USD CPI (YoY) (Aug)
13:30 USD CPI (MoM) (Aug)
15:30 USD Crude Oil Inventories
DAX- Technical Analysis
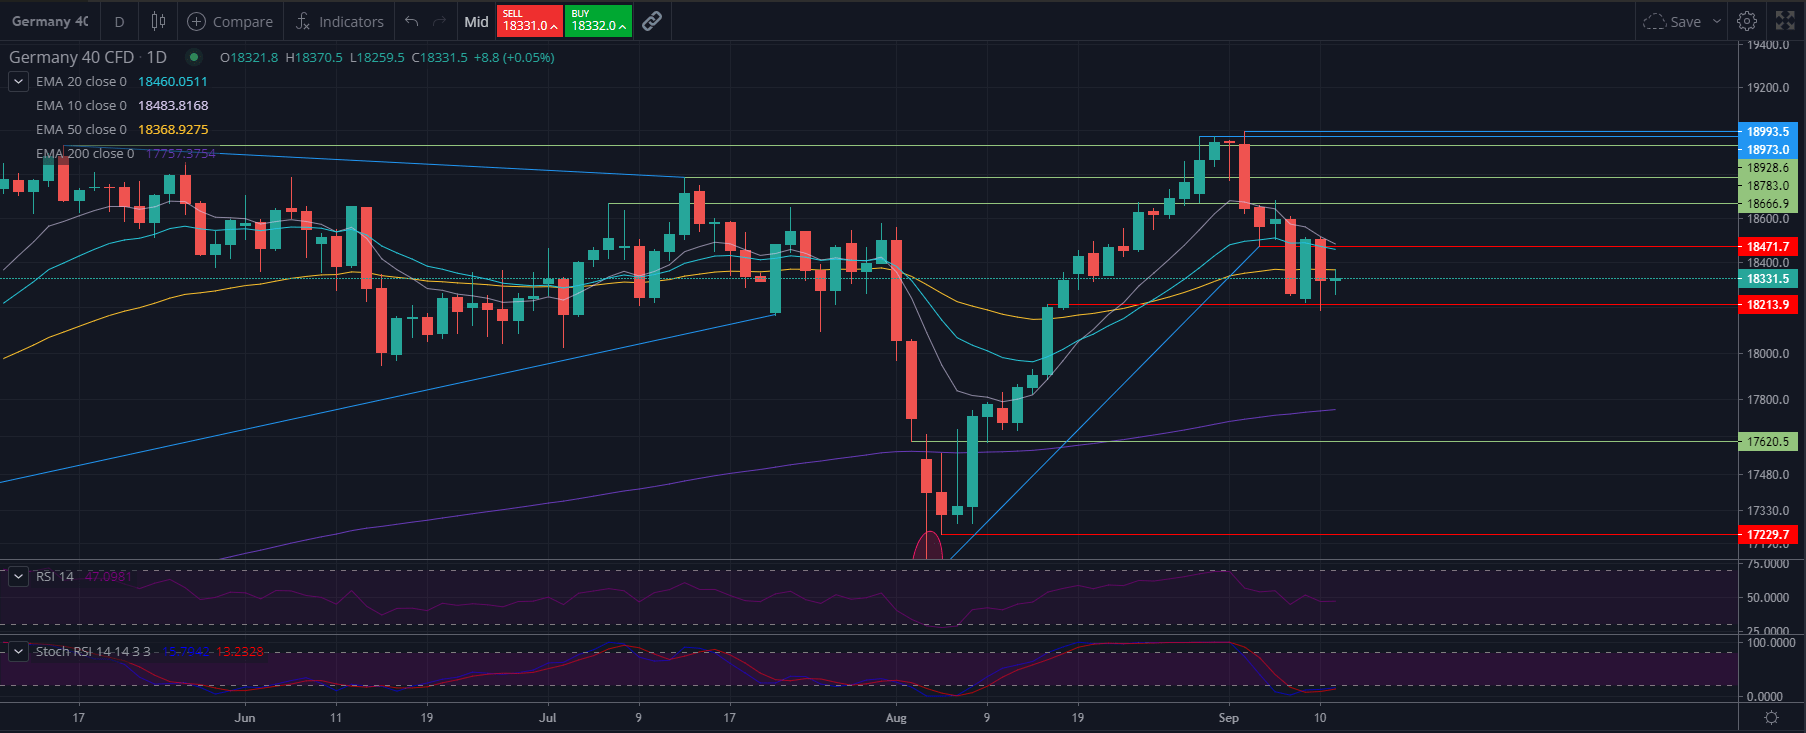
After last week's NFP scare, the price dropped to -1.77%. However, in Monday's trading session, the price was able to recover at least +1.33%. In yesterday's trading session, the price was in the range of Monday's highs and lows and did not deviate too much from the norm.
Currently, we are moving within the range of 18472 and 18213, which appear to be strong levels as they are previous highs and lows, and thus levels that must be broken through in order to advance.
On the daily chart, the price is currently trying to break the 50EMA as it is slightly below this level, but the candle is green and possibly forming a bottom tweezers formation. However, it is still early in the day, and given today's CPI and tomorrow's ECB interest rate decision, the market seems to remain cautious.
At tomorrow's ECB meeting, the ECB is expected to cut rates by 25 basis points, or 0.25%, which could support stock markets.
Other technical indicators such as the RSI are hovering around the neutral level of 50, while the stochastic RSI is currently oversold and a potential crossover is forming, which could indicate an increasing bullish momentum.
With high impact releases scheduled for today and tomorrow, traders seem to be cautious overall, and perhaps rightly so.
I will be back with more,
Kind regards,
Philip Papageorgiou
Follow me on X for daily insights: @Philipforexcom