



ASX 200 Slides Further as Tech, Discretionary and Real Estate Crack
ASX 200 weakness deepens as Tech, Discretionary and Real Estate lead the selloff, with rising RBA hike risks adding further pressure.
Share this:
The wheels are coming off the ASX 200 as its bearish move gathers pace. Regular readers will know I’ve held a negative view on the Australian share market in recent weeks, driven by price action clues among key ASX sectors.
View related analysis:
View related analysis:
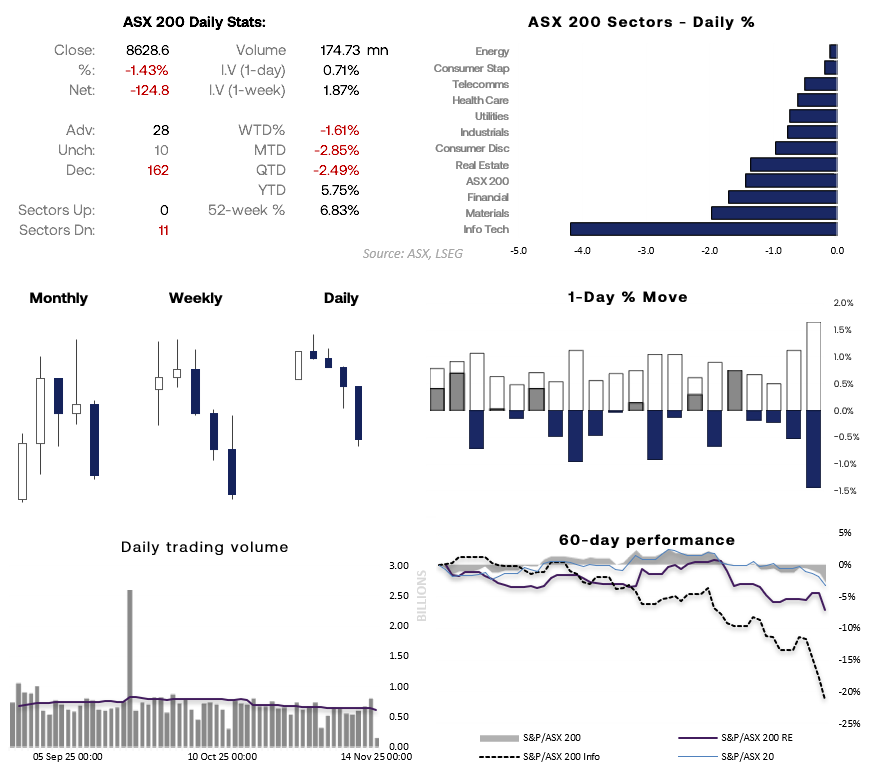
Chart analysis by Matt Simpson - data source: ASX, LSEG
Information Technology (XIJ) has been trending lower since its September peak after forming a double top above 3,000. Frothy tech valuations have become a growing concern on Wall Street, with heavy Nasdaq selling dragging the ASX tech sector with it. Consumer Discretionary (XDJ) has also been sliding for several weeks, with downside momentum accelerating through late October after topping out in August. This is a classic risk-off rotation as investors move away from cyclicals and into defensives such as Utilities. But even Utilities (XUJ) have turned lower following Wall Street’s selloff and rising risks that the RBA may hike rates next year.
In recent weeks, markets have had to absorb a hawkish RBA hold, rising inflation, a record jump in home loans, and now lower unemployment alongside firm job creation. These are hallmarks of an economy that’s heating up — and the prospect of an RBA hike wasn’t even on the ASX’s radar until this week.
If Australian economic data continues to heat up and raise expectations of hawkish talk from the RBA, it could weigh further on sectors such as Real Estate (XRE).


ASX 200 Real Estate (XEJ) Under Pressure as Goodman Group (GMG) Leads Megacaps Lower
The ASX 200 Real Estate sector (XEJ) peaked in August at a record high and has fallen roughly 10% over the past 14 days since its October high. A bear flag formed last week, and bearish momentum has clearly re-asserted itself. The XEJ/ASX ratio also shows the sector underperforming the broader market, despite the wider index facing selling pressure of its own. Thursday delivered the sector’s worst session in seven months, sliding -2.7%.
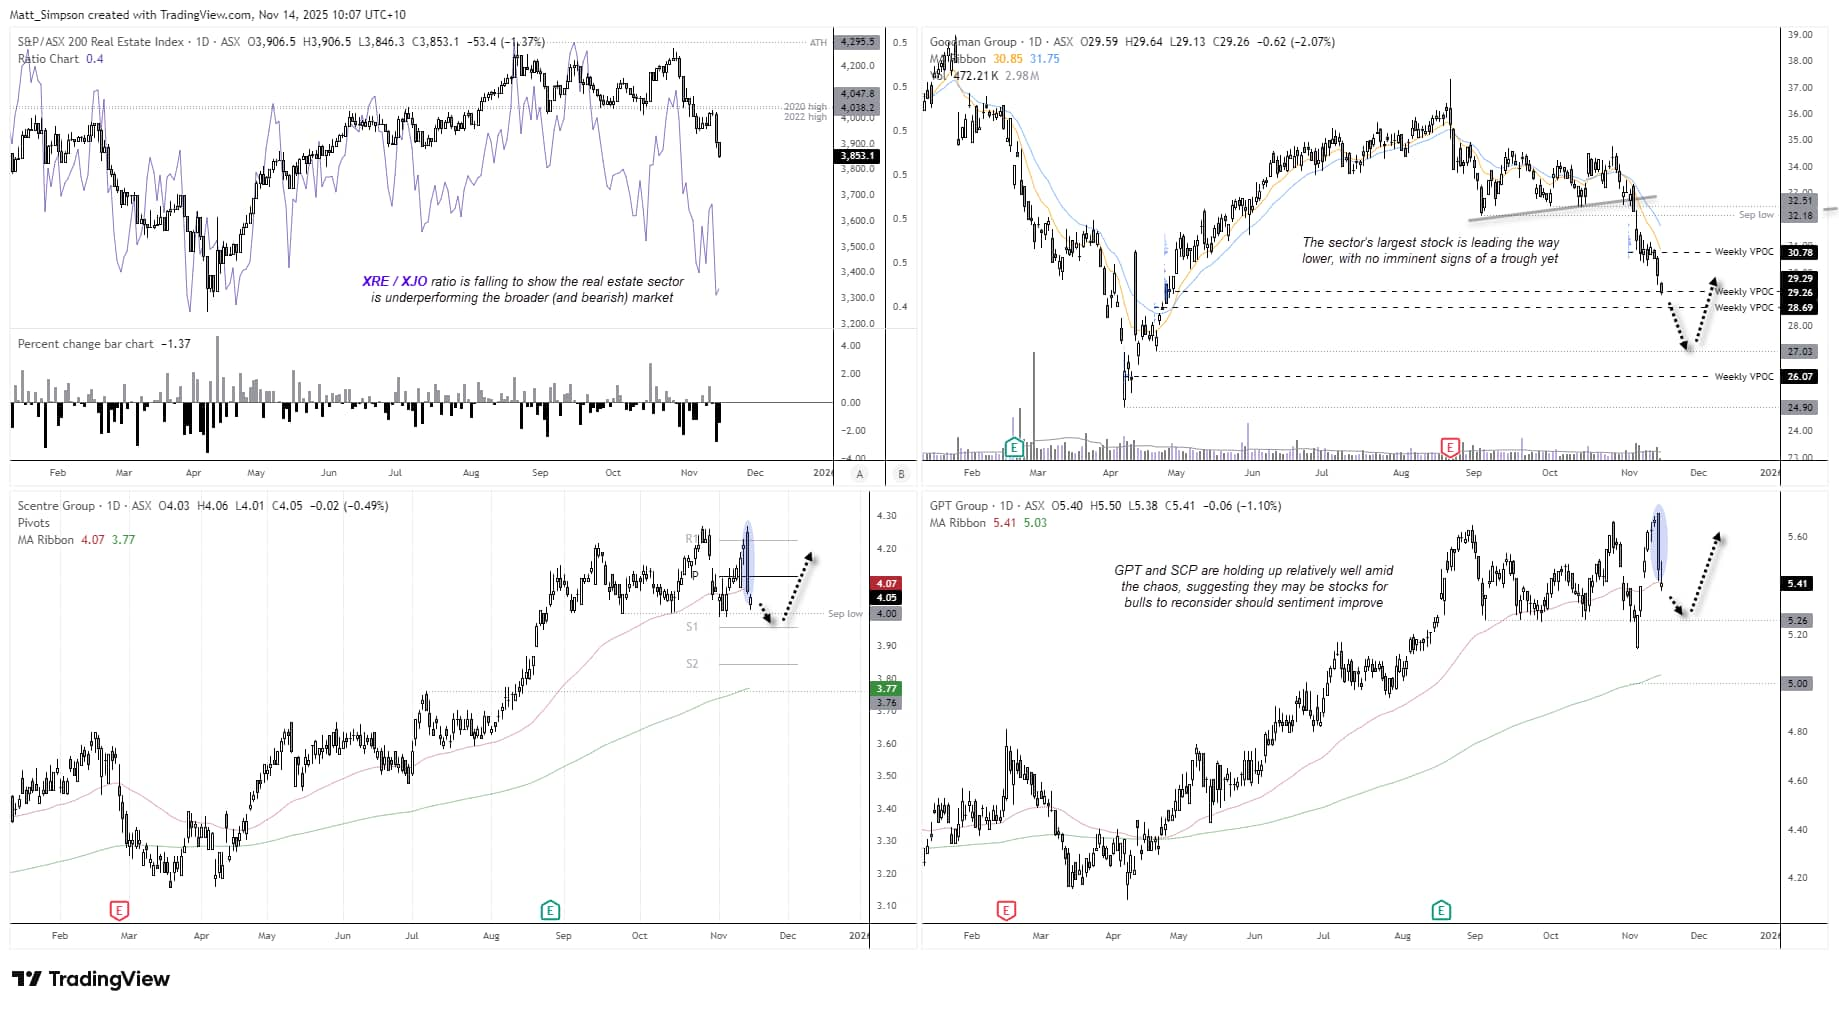
Chart analysis by Matt Simpson - data source: TradingView, ASX
Goodman Group (GMG)
The sector heavyweight is under strain, with Goodman Group (GMG) dropping to a seven-month low. GMG has now entered a technical bear market after falling more than 20% from its August high. Prices are trying to hold above a weekly VPOC at 29.29, but with no signs of a base forming, further downside towards the 28.69 VPOC remains possible. A break under 27 would expose the next VPOC at 26.07.
Scentre Group (SCG)
SCG is holding up relatively well despite the broader sector selloff. While an extended bearish engulfing candle formed on Thursday, prices are attempting to hold above the September low. With the $4 handle and monthly S1 pivot at 3.95 nearby, this may be one for bulls to consider if sentiment turns. For now, my bias remains neutral.
GPT Group (GPT)
GPT is showing a similar pattern to SCG: the stock is under pressure due to the risk-off tone, but it is holding up better than both the ASX 200 and the XRE sector. GPT is outperforming SCG, trading around its 50-day EMA and well above its September low. If sentiment improves, this is another stock bulls may look to.


REA Group (REA) Caught Between Technology and Real Estate Selloff
While REA sits within the ASX Communication Services Index (XTJ), its revenue is heavily tied to property activity. If rising interest rates slow housing turnover, earnings expectations for REA typically fall — which explains why the stock often trades more like a real-estate proxy than a pure media company.
This is reflected in its current behaviour: REA’s 20-day correlation with the XRE real estate sector sits at a strong 0.92 and is still rising. The price action also suggests REA is leading the XRE sector (purple) lower, and its relationship with XRE is notably stronger than with its official sector, XTJ (green).
The weekly chart shows a lower high forming in August, beneath the record peak set in February. The current decline may be part of a simple ABC pullback within the longer-term uptrend, or the early stages of a 5-wave bearish sequence.
The 100% projection of wave A from wave B falls around 190 — a level REA needs to hold to maintain the ABC correction scenario. A decisive break below 190 would open the door to a deeper selloff. The 50% retracement aligns with the 180 handle, while the 138.2% extension and 61.8% retracement cluster around 160, creating a notable downside zone for bears if 190 gives way.
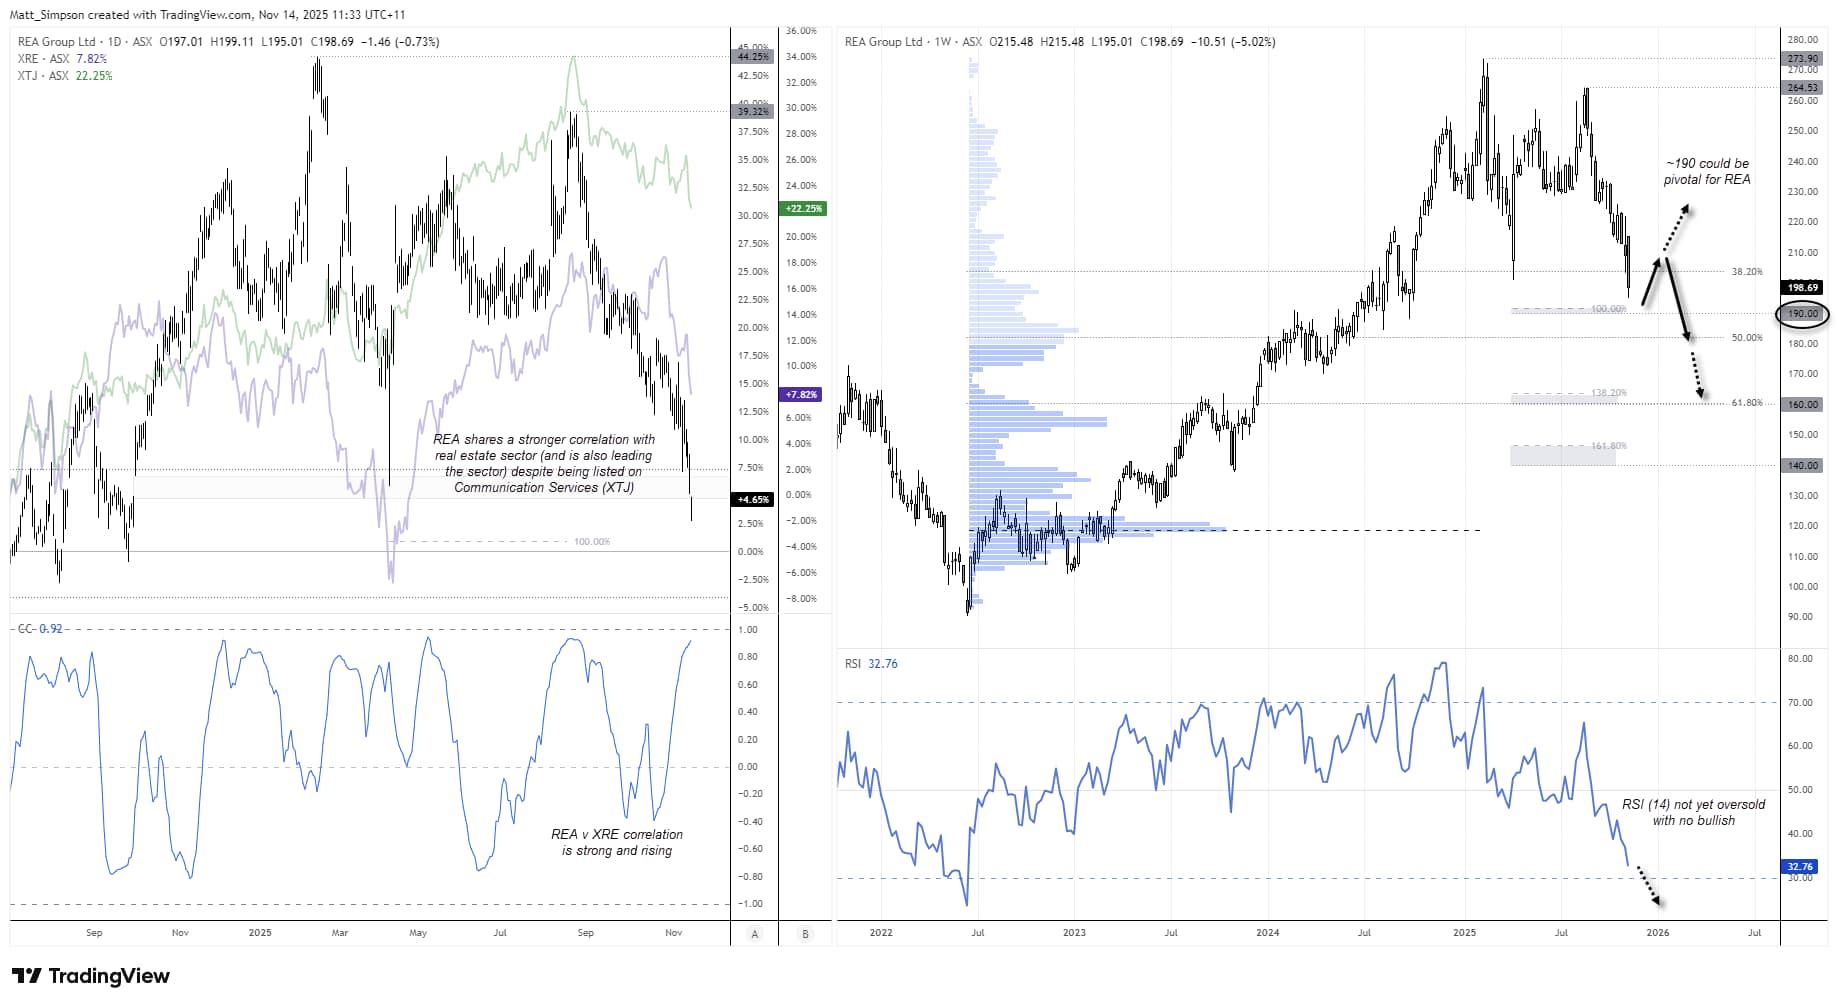
Chart analysis by Matt Simpson - data source: TradingView, ASX
View the full economic calendar
View the full economic calendar
-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade


Open an account today
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

silver-crash-2026-vs-2011-collapse
Silver has collapsed some 65% from its January peak, drawing uncomfortable comparisons with the 2011 crash. The parallels are striking, but a bigger bubble, a hawkish Federal Reserve and years of supply deficits make this episode different.


Nasdaq 100, SOX: Tech rout may be a symptom of something far larger
The financial tide is going out, and some of the market's biggest winners are being hammered. Our research suggests there's more to the tech rout than the AI headlines.


USD/JPY Outlook: Yen Strength Builds as Carry Trades Come Under Threat
Rising equity volatility threatens yen carry trades as USD/JPY struggles at 160 resistance and AUD/JPY leads a broader recovery in the Japanese yen.
From time to time, StoneX Financial Pty Ltd (“we”, “our”) website may contain links to other sites and/or resources provided by third parties. These links and/or resources are provided for your information only and we have no control over the contents of those materials, and in no way endorse their content. Any analysis, opinion, commentary or research-based material on our website is for information and educational purposes only and is not, in any circumstances, intended to be an offer, recommendation or solicitation to buy or sell. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. No representation or warranty is made, express or implied, that the materials on our website are complete or accurate. We are not under any obligation to update any such material.
As such, we (and/or our associated companies) will not be responsible or liable for any loss or damage incurred by you or any third party arising out of, or in connection with, any use of the information on our website (other than with regards to any duty or liability that we are unable to limit or exclude by law or under the applicable regulatory system) and any such liability is hereby expressly disclaimed.