



AUD/JPY Rattled at 35-Year High, Gold Probes 5000 as Volatility Spikes
Global markets swung sharply as war headlines fuelled volatility. AUD/JPY hit a 35-year high, gold probed 5,000 and equity indices suffered heavy losses.
Share this:
Volatility remained elevated on Tuesday as a wave of Middle East headlines rattled global markets. Equity indices and precious metals both closed lower, while currency markets endured wide intraday swings. Gold briefly probed the 5,000 level and AUD/JPY reached a fresh 35-year high, highlighting the extreme cross-asset volatility dominating trading conditions.
View related analysis:
View related analysis:


AUD/JPY Hits 35-Year High While Gold Tests 5,000 Amid Market Volatility
Volatility remained elevated on Tuesday amid a flurry of Middle East headlines, though the tone leaned bearish, with stock indices and precious metals both closing lower.
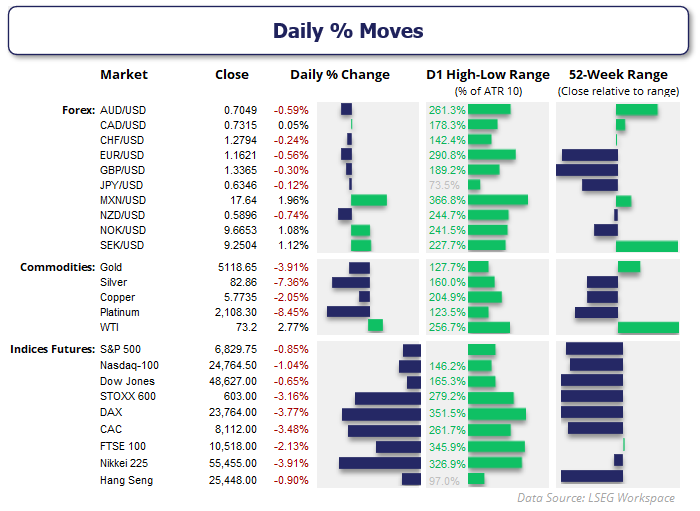
While Monday’s volatility was largely confined to the opening minutes of the week as traders priced in weekend news, Tuesday proved to be a more drawn-out affair. Most major markets endured daily ranges of two to three times their usual ATRs (average true ranges).
Gold falling alongside equities suggests it was a genuine risk-off session, as traders were likely forced to liquidate holdings to cover losses in equity markets or simply chose to move to cash and flatten positions for the day.
Source: LSEG
Markets Swing as Volatility Surges Across FX, Indices and Commodities
- European indices stood out for their volatility, with the DAX and FTSE 100 posting daily ranges of around 350% of their 10-day ATR, closing -3.2% and -2.1% respectively.
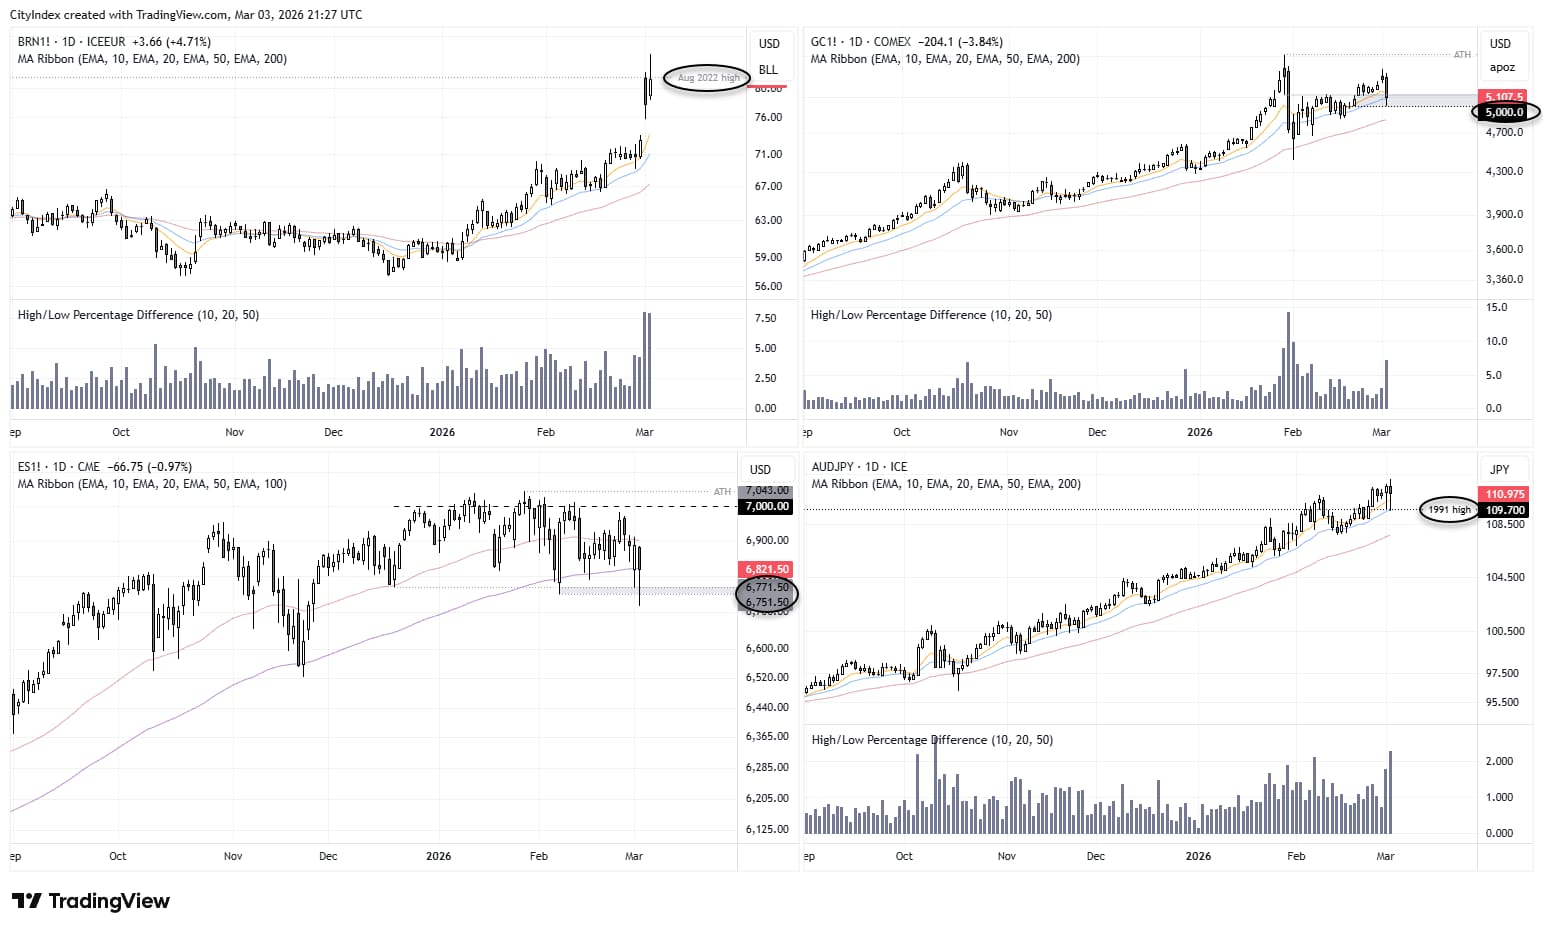
- Nasdaq 100 futures led the S&P 500 and Dow Jones lower, though all managed to recoup around half of the day’s losses and close back above key support levels, denying bears a clean breakout.
- SPI 200 (ASX 200 futures) fell as much as -3.4% overnight and closed down -1.4%, suggesting a notable gap lower for the ASX cash market today.
- NZD/USD and AUD/USD were the weakest FX majors, though their declines of -0.7% and -0.6% respectively mask the true volatility of the session, with ranges of around 250% of their ATRs.
- AUD/JPY formed an elongated hanging man candle despite reaching a 35-year high following hawkish comments from RBA Governor Bullock, with the 1991 high clearly acting as a pivotal level for traders.
- Crude oil rose 4.7% by the daily close, though it had earlier surged as much as 7.7% intraday before finishing just beneath Monday’s open and the August 2022 high.
- Gold fell in line with my near-term bearish bias, though it overshot my downside target of 5,200 and probed 5,000 — likely a pivotal level for traders this week.
Source: ICE, COMEX, CME, TradingView
FX Volatility Surges but Widespread Wicks Signal Indecision
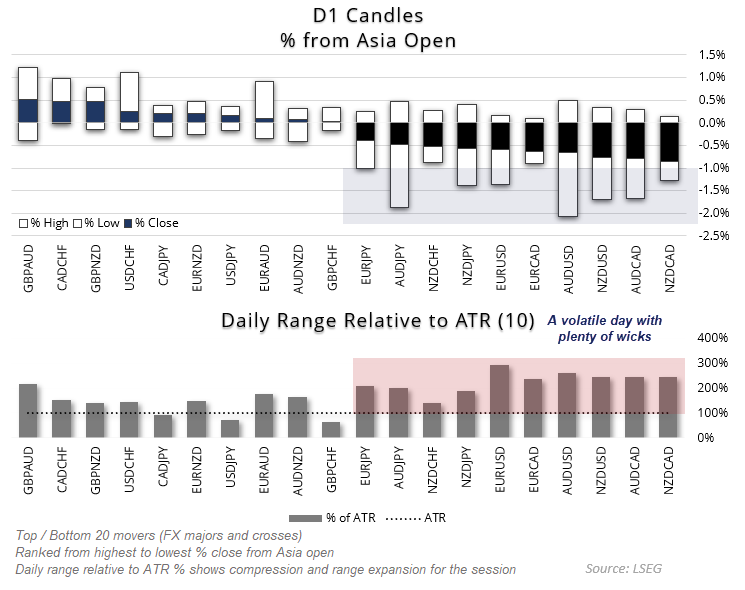
Currency markets, in particular, reflected a day of volatile indecision. Daily ranges clearly expanded, with several euro pairs pushing beyond 200% of their 10-day ATR and EUR/USD approaching 300%, yet forex pairs were also littered with large upper and lower wicks. This shows reversals occurred near the session’s extremes, with many pairs retracing at least two-thirds of the prior move before the close.
Source: LSEG
A true risk-off session would typically see markets open near their highs and close near their lows. Instead, volatility was accompanied by indecision. That does little to simplify today’s directional outlook, but it should keep traders alert.
My base case for now is that currency markets could trade largely within Tuesday’s ranges — somewhere within the dominant wick structure and around Tuesday’s closing levels.
Much will depend on incoming headlines. Volatility could easily flare again during the European or US sessions, potentially forcing markets to choose a direction depending on whether geopolitical tensions escalate (risk-off) or ease (risk-on).


Economic Events in Focus (AEDT / GMT+11)
It is debatable how important today’s economic calendar will prove, despite being regionally packed. Traders clearly have the fog of war on their radar, alongside concerns that rising energy prices could fuel inflation while weighing on growth. In such an environment, strong economic data may simply reinforce expectations for tighter policy even as petrol prices climb.
Ultimately, traders — like any warm-blooded human — would prefer to see a swift resolution to the conflict in Iran.
That said, the RBA will be keeping a close eye on today’s Australian GDP figures, which may have scope to surprise higher given relatively low expectations. Final PMI readings are also due, which rarely move markets materially but still provide a useful temperature check on growth momentum and inflation trends.
That latter point makes the ISM non-manufacturing (services) PMI particularly important, especially after the sharp rise in prices paid seen in this week’s ISM manufacturing survey.
- 08:45 — NZD Terms of Trade, Export Prices, Import Prices, Export Volumes, Terms of Trade Index (Q4) (NZD/USD, AUD/NZD, NZD/JPY)
- 09:00 — AUD AiG Construction Index, AiG Manufacturing Index, S&P Global Manufacturing & Services PMI (Feb) (AUD/USD, AUD/JPY, AUD/NZD)
- 11:30 — AUD GDP, GDP Final Consumption, GDP Chain Price Index, GDP Capital Expenditure (Q4) (AUD/USD, AUD/JPY, AUD/NZD)
- 11:30 — JPY S&P Global Services PMI, Composite PMI (Feb) (USD/JPY, EUR/JPY, AUD/JPY)
- 12:30 — CNY Manufacturing PMI, Non-Manufacturing PMI, Composite PMI (Feb) (AUD/USD, AUD/CNH, USD/CNH)
- 12:45 — CNY Caixin Manufacturing PMI, Caixin Services PMI (Feb) (AUD/USD, AUD/CNH, USD/CNH)
- 16:00 — JPY Household Confidence (Feb) (USD/JPY, EUR/JPY, AUD/JPY)
- 18:30 — CHF CPI (Feb) (USD/CHF, EUR/CHF, GBP/CHF)
- 19:55 — EUR Germany Services PMI, Germany Composite PMI (Feb) (EUR/USD, EUR/GBP, EUR/JPY)
- 20:30 — GBP S&P Global Services PMI, Composite PMI (Feb) (GBP/USD, EUR/GBP, GBP/JPY)
- Thursday, March 5
- 00:15 — USD ADP Nonfarm Employment Change (Feb) (EUR/USD, USD/JPY, GBP/USD)
- 01:30 — CAD S&P Global Services PMI (Feb) (USD/CAD, CAD/JPY, EUR/CAD)
- 01:45 — USD S&P Global Services PMI, Composite PMI (Feb) (EUR/USD, USD/JPY, GBP/USD)
- 02:00 — USD ISM Non-Manufacturing PMI, Prices, Employment, New Orders, Business Activity (Feb) (EUR/USD, USD/JPY, GBP/USD)
View the full economic calendar
View the full economic calendar
-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:
Latest market news




Open an account today
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Rates Shock, Metals Rout Leave Aussie Dollar Under the Pump
The global environment is becoming increasingly hostile for the Aussie. With AUD/USD breaking major support and AUD/JPY threatening further downside, today's jobs report faces an uphill battle to change the picture.


Gold's Rout Accelerates as FOMC Minutes Bolster the US Doller
Gold extends its selloff as hawkish FOMC minutes reinforce Fed rate hike expectations, lifting the US dollar and pressuring gold prices across major currencies.

GBP/USD, GBP/JPY, GBP/AUD: Sterling Eyes UK Inflation Catalyst
Sterling faces a pivotal UK inflation test as traders weigh BoE tightening, Fed minutes and Australian employment data across GBP/USD, GBP/JPY and GBP/AUD.
From time to time, StoneX Financial Pty Ltd (“we”, “our”) website may contain links to other sites and/or resources provided by third parties. These links and/or resources are provided for your information only and we have no control over the contents of those materials, and in no way endorse their content. Any analysis, opinion, commentary or research-based material on our website is for information and educational purposes only and is not, in any circumstances, intended to be an offer, recommendation or solicitation to buy or sell. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. No representation or warranty is made, express or implied, that the materials on our website are complete or accurate. We are not under any obligation to update any such material.
As such, we (and/or our associated companies) will not be responsible or liable for any loss or damage incurred by you or any third party arising out of, or in connection with, any use of the information on our website (other than with regards to any duty or liability that we are unable to limit or exclude by law or under the applicable regulatory system) and any such liability is hereby expressly disclaimed.