

Australian Dollar Outlook: AUD/USD Surges as Risk Appetite Returns Ahead of AU CPI
AUD/USD rallies sharply as risk sentiment improves and markets refocus on RBA hike risk ahead of Australia’s crucial Q4 CPI report.
Share this:

The Australian dollar has been the standout performer in FX this past week, rallying sharply against all major peers. Gains versus the Japanese yen and US dollar have been particularly strong, with neither AUD/USD nor AUD/JPY showing any meaningful signs of a bearish reversal so far. Improving risk sentiment and renewed focus on domestic inflation risks have combined to put the Aussie firmly back on traders’ radar.
View related analysis:
View related analysis:
Why AUD/USD Is Rallying as Risk Appetite Improves and RBA Hike Bets Return
Improving risk sentiment — helped by easing geopolitical and tariff concerns tied to recent US–Greenland headlines — has allowed traders to refocus on domestic fundamentals and the potential for further policy tightening by the Reserve Bank of Australia. A rally in base metals is reinforcing expectations of a pickup in global growth, adding another tailwind for the Australian dollar. Crucially, the Aussie’s broad-based strength shows this is not simply a US dollar story, suggesting underlying demand for AUD is building earlier than expected.
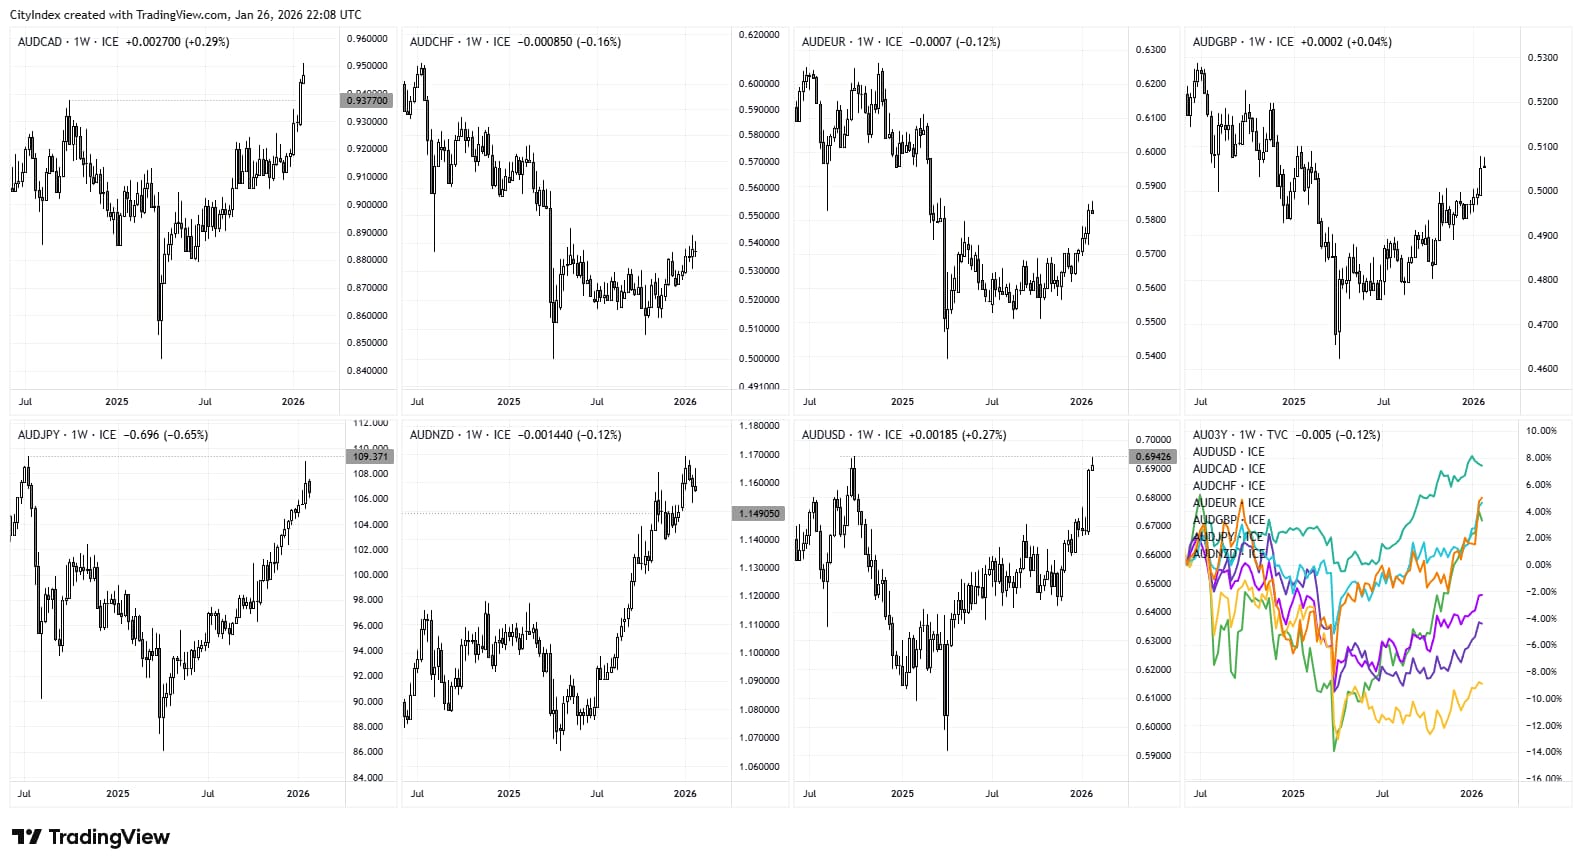
Source: TradingView
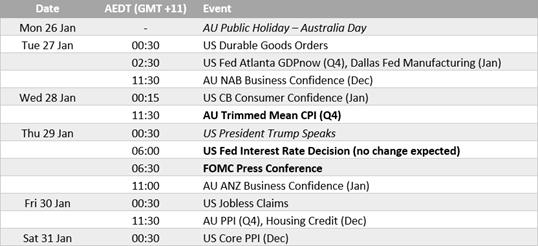
No Change Expected from the Fed
Markets have been pricing in no change from the Federal Reserve for some time, and there is little reason to expect otherwise. Despite President Trump’s persistent efforts to pressure Fed Chair Jerome Powell, US not cooling quickly enough to justify rate cuts.
As a result, the Fed is unlikely to deviate materially from its current guidance at this meeting. Updated economic projections were released in December, and incoming data since then has only reinforced expectations for policy to remain on hold.


Q4 CPI Takes Centre Stage for RBA Policy
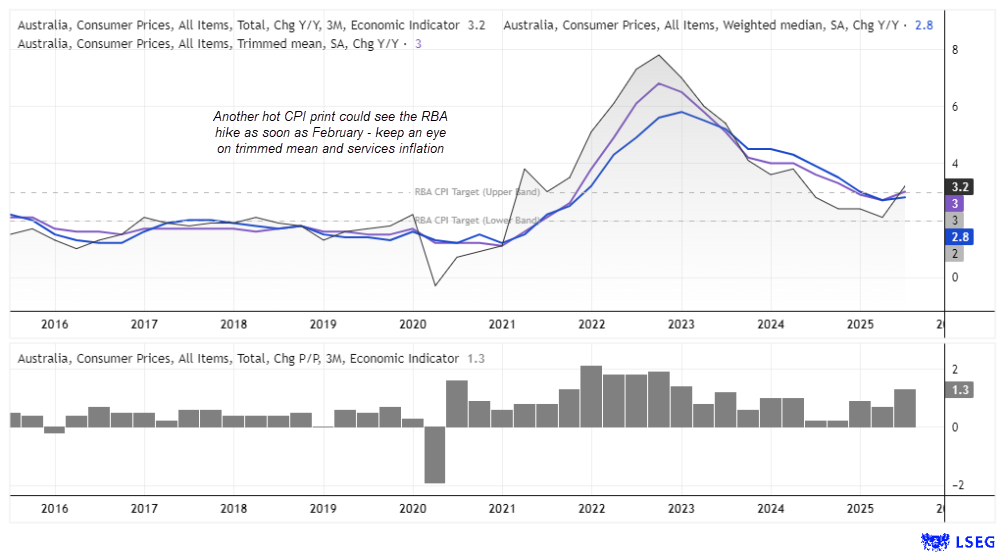
Source: ABS, LSEG
Domestically, Australia’s economic calendar needs little over-analysis, with Wednesday’s Q4 CPI report clearly the focal point. Governor Michele Bullock has made it clear that this inflation print is the key swing factor for the February policy meeting. The Bank has deliberately adopted a wait-and-see stance, and Q4 CPI represents the final major data input before a decision is made on whether policy needs to tighten again.
Following this week’s strong employment figures for December, any heat in CPI data — reflected through a firmer trimmed mean or persistently sticky services inflation — would materially lift expectations that the RBA could still deliver a rate hike as soon as February.
AUD/USD Correlations
Traditional correlations with the Australian dollar have re-emerged amid macro-driven volatility, with gold, the New Zealand dollar (NZD) and the Chinese yuan (CNH) showing a strong positive relationship, alongside a clear inverse correlation with the US dollar (USD) index.

Source: LSEG


AUD/USD Futures Positioning – COT Report
The slight decline in net-long exposure fails to capture the explosive move higher in the Australian dollar, as the report was compiled at Tuesday’s close — missing the Aussie’s 2.4% rally into Friday. With AUD/USD extending gains again on Monday, there’s a strong chance futures traders are already net-long the pair. And if asset managers aren’t there yet, they’re likely very close to flipping to a bullish net-long stance.

Source: CFTC, CME, LSEG
AUD/USD Technical Analysis
There is little need to overcomplicate the technical picture while the Australian dollar remains in the midst of a strong, fundamentally driven move. Unless global sentiment reverses sharply and expectations for an RBA hike fade, pullbacks are likely to be favoured by AUD/USD bulls. I also suspect futures traders will hold on to net-long exposure for some time once achieved — if they haven’t already reached that point.
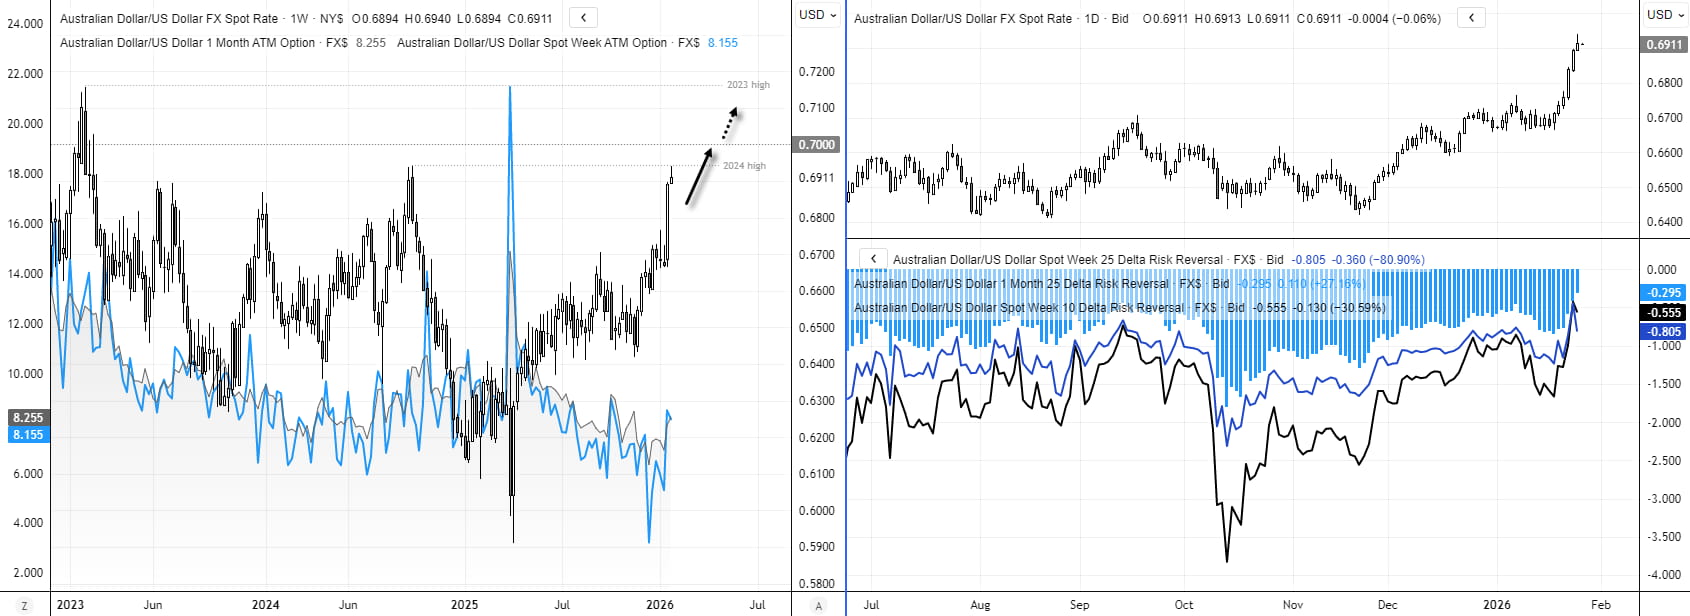
Implied volatility is lifting from depressed levels, while risk reversals are turning higher, signalling that demand for calls is rising and beginning to outpace demand for puts. That said, both the 10-delta and 25-delta risk reversals dipped slightly after AUD/USD tagged the 2024 high on Monday, warning of potential near-term exhaustion.
While AUD/USD may look stretched in the short term, meaningful pullbacks appear unlikely in the current environment. Bulls are now eyeing a move toward 0.70, a break above which would bring the 2023 high firmly into focus as the year progresses.
Source: LSEG
View the full economic calendar
View the full economic calendar
-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:
Latest market news



Open an account today
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
AUD/USD Outlook: Macro Forces Collide Ahead of US, AU Inflation
Macro forces have hammered the Australian dollar, but could sticky inflation catch AUD/USD bears off guard after a bruising week?

US Dollar Freight Train Drives EUR/USD, GBP/USD to Fresh Lows
A hawkish Fed and growing jitters around AI have pushed a continued rally in the Greenback, and there’s not yet an end in sight.


Japanese Yen Forecast: USD/JPY Bulls Falter at Major Resistance—Critical Range Break in Focus 11 20 2026
USD/JPY’s latest retreat puts the September recovery under scrutiny, with nearby support offering bulls their next opportunity to respond.

From time to time, StoneX Financial Pty Ltd (“we”, “our”) website may contain links to other sites and/or resources provided by third parties. These links and/or resources are provided for your information only and we have no control over the contents of those materials, and in no way endorse their content. Any analysis, opinion, commentary or research-based material on our website is for information and educational purposes only and is not, in any circumstances, intended to be an offer, recommendation or solicitation to buy or sell. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. No representation or warranty is made, express or implied, that the materials on our website are complete or accurate. We are not under any obligation to update any such material.
As such, we (and/or our associated companies) will not be responsible or liable for any loss or damage incurred by you or any third party arising out of, or in connection with, any use of the information on our website (other than with regards to any duty or liability that we are unable to limit or exclude by law or under the applicable regulatory system) and any such liability is hereby expressly disclaimed.