


Bond markets are imploding: Central concern for markets
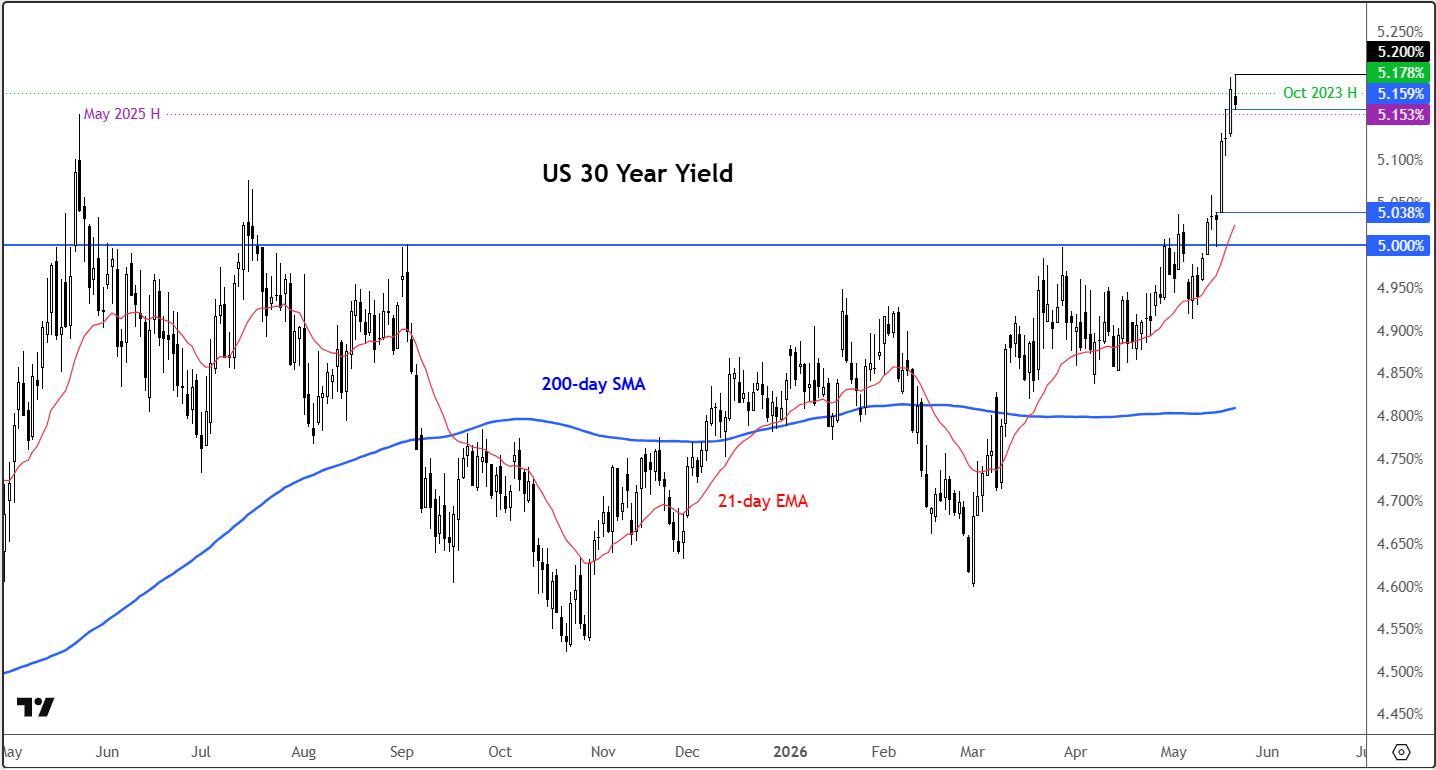
The US 30-year Treasury yield briefly climbed to 5.20% today, its highest level since 2007, before retreating modestly alongside softer oil prices. But the broader trend remains troubling. Before the escalation of the US-Iran war, markets had been moving steadily towards a softer inflation outlook, with markets pricing in further easing of US monetary policy. But roughly three months later, yields soared due to a substantial repricing and all to do with the closure of the Strait of Hormuz.
Share this:
The US 30-year Treasury yield briefly climbed to 5.20% today, its highest level since 2007, before retreating modestly alongside softer oil prices. But the broader trend remains troubling. Before the escalation of the US-Iran war, markets had been moving steadily towards a softer inflation outlook, with markets pricing in further easing of US monetary policy. But roughly three months later, yields soared due to a substantial repricing and all to do with the closure of the Strait of Hormuz. Even so, US technology stocks have surged higher, and the Nasdaq 100 has only recently pulled back from its all-time highs again. But the risk of a deeper correction is there now with yields surging. Any correction in the equity markets should provide further support to safe haven US dollar.
Iran conflict could drag on as US Senate advances measure to limit Trump's Iran war powers
Initially, investors believed the conflict would remain contained and that disruption to the Strait of Hormuz would prove temporary. Instead, shipping flows through one of the world’s most important energy corridors remain severely restricted, keeping energy markets under sustained pressure. For as long as this remains the case, the path of least resistance for yields and the dollar will remain to the upside.
The pressure is certainly growing on Trump after the Senate approved a procedural vote yesterday related to a war powers resolution. If this is adopted, the war powers resolution would severely restrict Trump’s war powers in Iran. This only increases Iran’s negotiation powers, which may mean even a longer stalemate in the situation and much higher energy prices.
Inflation pressures are feeding back into rates markets
With crude oil holding at these elevated levels for an extended period, both inflation and inflation expectations have moved sharply higher once again. Producer price inflation in the US has accelerated to 6.0%, while consumer inflation has climbed to 3.8%, both reaching their highest levels since 2023. When inflation becomes more persistent, lenders demand higher long-term yields to compensate for the erosion of purchasing power. This should mean even higher bond yields, which is bad news for risk and good for the dollar.
Inflation could accelerate further in the coming months. Jet fuel prices have surged, meaning higher plane ticket prices. Meanwhile petrol costs remain elevated too which is very bad for the US consumer reliant on private transport - that’s almost everyone. And then you have fertiliser prices soaring sharply, which will eventually work their way through food prices. So, supply chains and consumer prices alike will feel the pressure which should be bad news for everyone.
This is turn means that the fiscal backdrop in the United States continues to deteriorate. Treasury issuance is increasing rapidly at precisely the same moment investors are demanding higher compensation to hold longer-dated debt.
The combination is difficult for bond markets to absorb smoothly. Not only will mortgage rates go up for consumers, but the debt servicing costs will increase sharply for the government, which would need to be financed by issuance of even more debt at even higher yields, or by reducing budgets of other sectors of the economy.
But it is not just US bond yields rising. We have seen a big shift in global yields as a result of the Iran conflict.

It is a messy situation to say the least.
Will markets force Trump to accept a bad deal to end the conflict?
As mentioned, the bond markets are approaching uncomfortable territory. Last year, yields were rising sharply when Trump unleashed tariffs, before he paused those and eventually settled for much lower rates. Now with yields rising to similar levels and higher in the case of 30-year, this raises an increasingly important question for investors: how high can yields realistically rise before Trump TACOs? Sustained yields above 5% would place growing strain on both public and private sector finances, raising risks of stagflation and potentially downgrading of US credit ratings. The pressure is certainly building, but will Trump do anything about it just yet?

Source for all charts used in this article: TradingView.com
-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R
Latest market news




Open an account today
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Nasdaq 100 forecast: Markets turn jittery as Anthropic debuts at 34% above IPO
Nasdaq futures were up some 2% earlier, but shortly after the Anthropic debut, the index slumped to session lows, down more than 1.5%, before bouncing back from the lows at the time of writing. Much of the selling for the Nasdaq was driven by AMD which slumped nearly 10% after a Hunterbrook Media report raised fresh questions about the company’s exposure to US export controls on China.
Australian Dollar Technical Outlook: AUD/USD 6% Plunge Tests Make-or-Break Support at Yearly Low 11 19 2026
AUD/USD’s four-week decline is testing critical support, with a decisive break below this threshold needed to fuel the next major leg lower.

Gold and silver forecast: Stretched dollar leaves XAU and XAG in need of a reversal
There is still no end in sight for the selling in precious metals, with both gold and silver hitting new 2026 lows today, before bouncing back modestly amid profit-taking. The US dollar has eased a bit lower and that might encourage some dip-buying, although both metals need a key reversal pattern to emerge before any meaningful recovery can take hold, and so far, there is no sign of one.
From time to time, StoneX Financial Pty Ltd (“we”, “our”) website may contain links to other sites and/or resources provided by third parties. These links and/or resources are provided for your information only and we have no control over the contents of those materials, and in no way endorse their content. Any analysis, opinion, commentary or research-based material on our website is for information and educational purposes only and is not, in any circumstances, intended to be an offer, recommendation or solicitation to buy or sell. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. No representation or warranty is made, express or implied, that the materials on our website are complete or accurate. We are not under any obligation to update any such material.
As such, we (and/or our associated companies) will not be responsible or liable for any loss or damage incurred by you or any third party arising out of, or in connection with, any use of the information on our website (other than with regards to any duty or liability that we are unable to limit or exclude by law or under the applicable regulatory system) and any such liability is hereby expressly disclaimed.