View this week's events and trading themes which could drive markets: The Week Ahead 
 This content will only appear on Forex websites! Read our guide on how to interpret the weekly COT report


A quick glance across large speculative positioning over various timeframes shows that trades were relatively bearish on the Japanese yen (JPY/USD), WTI and the US 2-year bond bill across all time horizons measured (3 year, 1 year and 3 month). We say relatively, as percent rank looks at the current data in relation to its respective range, but that does not necessarily mean trader are net long or net short each market (as traders remain net-long WTI futures, yet net-short bonds and the yen). Net exposure can be seen in later charts.
We note that net-short exposure to the S&P 500 and Dow Jones Industrial futures contracts are diminishing, whilst bearish exposure to the 2-year note has intensified (to reflect bets of higher Fed rates). Traders remain net short JPY futures and potentially at or near a sentiment extreme, which we look at in a later chart.
Commitment of traders (forex) – as of Tuesday 13thJune 2023:
- The weekly change for net-long/short exposure to FX majors were relatively small, and all came under +/- 6.6k contracts.
- Net-long exposure to EUR/USD futures fell for a fourth week, although at a modest pace
- Large speculators trimmed net-short exposure to JPY futures, yet remain near a potential bearish extreme
This content will only appear on Forex websites! Read our guide on how to interpret the weekly COT report
Australian dollar futures (AUD/USD) – Commitment of traders (COT):
Whilst net-short exposure to AUD futures fell to a 66-week low, both gross longs and shorts were lower and open interest fell at its fastest pace in 25 weeks. This shows a slight lack of confidence from both parties despite the strong rally over the past three weeks. It’s also worth noting that ~30k long contracts have been closed over the past two weeks. But, on the other hand, stimulus from China and a strong employment report for Australia may have prompted some of those bulls to return since Tuesday’s COT data was compiled.
Euro dollar futures (EUR/USD) – Commitment of traders (COT):
Net-long exposure to EUR/USD fell for a fourth consecutive week, after prices topped out below 1.1100 back in May. We warned of a sentient extreme, and it appears there is some caution around these highs with gross-longs falling for a fifth week and accounting for much of the pullback on net exposure. And that is quite an important observation, because for a genuine turning point to occur would require strong initiation form bears, which at present is sorely lacking. So perhaps we won’t see the large pullback we envisaged, and it still allows the potential for EUR/USD to have another crack at 1.11 – even if it ultimately fails.
For now, a Small Doji formed on Friday after its strong rally on Thursday, and due to the public holiday in the US today we could find volatility on the low side. But it appears we may need some mean reversion towards 1.0900, a level which may tempt more bulls back to the table over the near-term.

Japanese yen futures (JPY/USD) - Commitment of traders (COT):
The BOJ predictably retained their ultra-dovish stance on Friday, which allowed USD/JPY to move to a fresh YTD high and marginally extend gains in today’s Asian session. Whilst net-short exposure to JPY futures was trimmed slightly last week, it remains at it most bearish level since October and at to near a potential sentiment extreme.
The chart below shows USD/JPY spot alongside net exposure to JPY/USD (flipped), to better highlight potential bullish or bearish zones for sentiment. Ad whilst the spot price is clearly within a well defined uptrend, one has to question how much upside there is for USD/JPY before the ministry of Finance become vocal about levels of volatility for the yen and cause a shakeout or correction. But perhaps the bigger threat to the current trend is if we’re to see greater discussion about the adjustment or cancellation of YCC from the BOJ. And a good place to look is this week’s BOJ monetary policy meeting minutes.

Commitment of traders (indices, bonds) – as of Tuesday 13thJune 2023:
- Large speculators reduced net-short exposure to S&P 500 futures for a second week (from a record low)
- Open interest (proxy for volume) for S&P 500 future rose to a 1-month high
- Net-short exposure to Dow Jones Industrial (DJO) futures fell at its fastest weekly pace in 14 months
- Traders remained net-long Nasdaq futures for a ninth week
- Net-short exposure to the 2-year bond bill reached a fresh record high
- Net-short exposure to the 30-day Fed Fund Futures contract declined for the first week in four
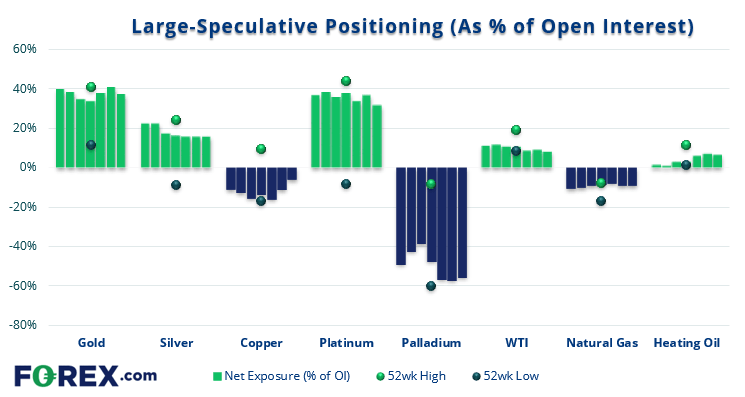
Commitment of traders (commodities) – as of Tuesday 13thJune 2023:
- Managed funds flipped to net-long exposure to copper futures
- Large speculators reduced net-short exposure to copper futures by ~50%
- Managed funds were their least bullish on gold futures in 13-weeks, and large speculators trimmed net-long exposure by -8.8%
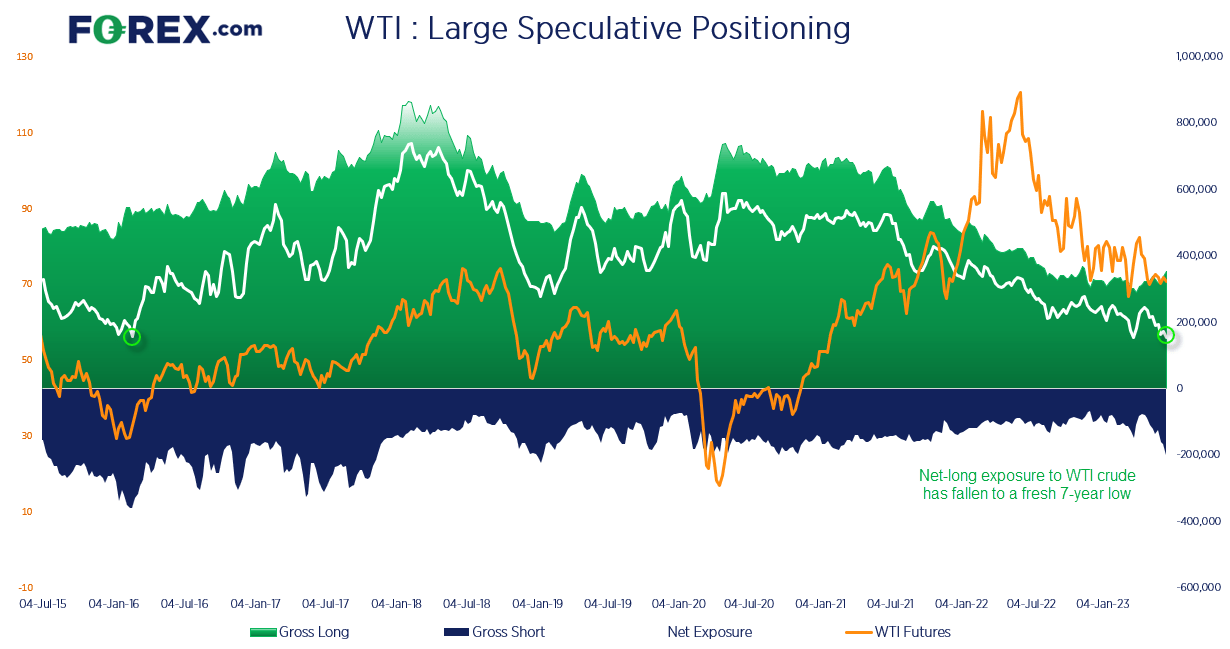
- Net-long exposure to WTI futures fallen back near its 7-year low
WTI Crude oil future (CL) - Commitment of traders (COT):
Whilst large speculators remain net long WTI crude, they are at their least bullish level in nearly even years. The recovery in China has not lived up to expectations to boost demand forecasts, and it would appear that the threat of further oil production cuts has also jot been enough to scare bears in a meaningful way. A such, gross longs are soaring higher and close to reaching 200k contracts, as bearish bets outpace bullish ones. However, bears may want to be cautions around these lows and it is difficult to see OPEC allowing oil prices to fall too hard, too fast. Furthermore, we’ve seen two prominent swing lows in March and May around the 63-34 area, and the markets has effectively moved sideways since December as the bearish move from the 123 highs has clearly lost momentum. SO unless we see a downside break, the odds could favour an upside move as bears may be forced to cover.