The forex market has been fairly quiet so far this week and we expect that theme to continue until at least the middle of the week. The US dollar forecast remains mildly bearish given rising expectations for a rate cut in September, and possibly a couple more before the year is out. We have a couple of Fed speakers before Fed Chair Powell speaks at the Jackson Hole symposium on Friday, while global PMI data on Thursday is another potential driver for volatility on Thursday.
Euro rebounds amid hopes for Ukraine-Russia ceasefire
Currency markets were fairly measured after the meeting between Zelenskyy, European leaders and Donald Trump yesterday. Washington’s openness to providing security guarantees to Kyiv – potentially nudging Ukraine towards considering Moscow’s territorial demands – has been taken as a cautious positive. The expectation now is for direct Russia-Ukraine talks in the coming weeks, perhaps with the US at the table too. That said, the lack of a concrete roadmap to a ceasefire left euro bulls underwhelmed a little bit, although the currency was up against the USD, CAD, GBP and JPY and AUD by mid-day in London.
So, while there’s a sense that the path to peace is at least slightly clearer, traders remain wary. And rightly so – the toughest conversations, namely over territory, still lie ahead.
Meanwhile, Ukraine aside, euro traders will be keeping a close eye on tomorrow’s release of Purchasing Managers' Indices (PMIs) for Germany and the Eurozone. They are leading indicator of economic health, given that businesses’ purchasing managers hold the most current and relevant insight into the company's view of the economy. What they report in these surveys tend to move markets. Activity has been flatlining in both services and manufacturing sectors of Germany and the Eurozone. Any positive changes should move the euro and undermine the dollar forecast even more.
Few drivers for dollar forecast ahead of Jackson Hole
For the US dollar forecast, it’s US data that matters more than anything else right now, it seems. Following a busy last week, this week’s macro calendar is thin until Thursday’s start of the Jackson Hole Symposium, where all eyes will be on Chair Powell who is due to speak on Friday. Markets are already positioned for a dovish tilt, with Fed funds futures pointing to a September cut, though last month’s sharp rise in PPI, as we found out last week, has muddied the waters a little.
Ahead of tomorrow’s FOMC minutes and Jackson Hole on Thursday, the dollar may struggle to find fresh support. Today’s focus is on housing data and remarks from Fed’s Michelle Bowman – usually on the dovish side – with markets keen to see if she hints at backing a total of 75bps move in the next three Fed meetings. Meanwhile July housing permits and starts are both seen falling compared to the previous month – to 1.39M from 1.40M and 1.29M from 1.32M annualised units, respectively.
Dollar Index (DXY) technical analysis
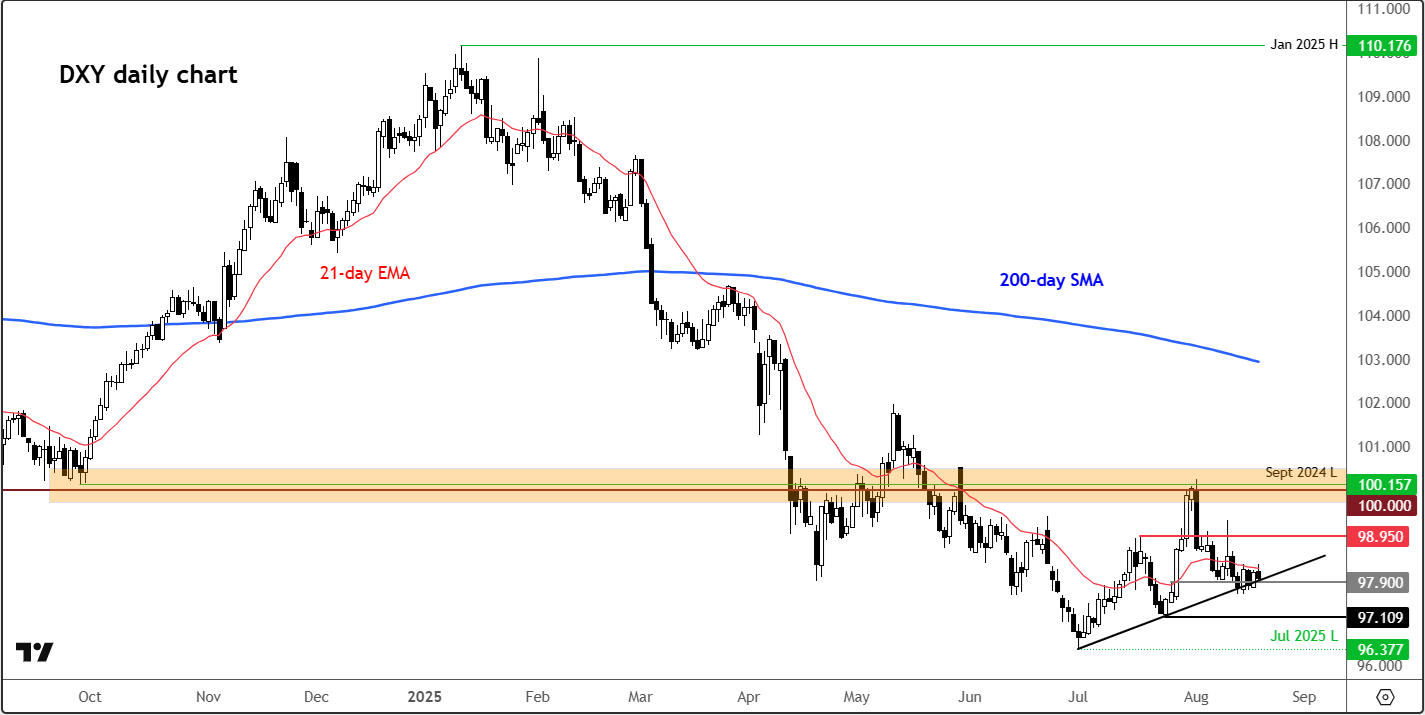
The dollar forecast from a technical analysis point of view remains bearish until the charts tell us otherwise, given the lower lows and lower highs. More recently, though, the Dollar Index (DXY) chart has managed to form a couple of higher lows above the July low of 96.37. The late July low at 97.10 is the most significant one to watch, given this marked the last low prior to the rally that took the DXY above 100.00 resistance, even if momentarily. Ahead of this, we have interim support around 97.90 to watch closely. Here, we have a short-term trend line coming into play.
Resistance is seen initially at 98.30, followed by 98.95 and then that 100.00 level.
-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R