



Dow Jones Forecast: DJIA cautious as oil jumps & earnings loom
U.S. stocks are subdued on Monday as investors weigh oil prices and geopolitical developments, while looking cautiously ahead to Q3 bank earnings and inflation data later in the week.
Share this:

US futures
Dow futures 0.26%, S&P 500 futures 0.1% & Nasdaq futures -0.29%
European futures
FTSE 0.64%, DAX 0.67%
- US stocks start the week on a cautious note
- Oil prices rise, and Treasury markets are closed
- Q3 bank earnings come this week
- Oil rises as Middle East uncertainty overshadows Russia developments
U.S. Stocks Mixed as Oil Hits 2-Week High
U.S. stocks are subdued on Monday as investors weigh oil prices and geopolitical developments, while looking cautiously ahead to Q3 bank earnings and inflation data later in the week.
Oil prices have risen above $106 a barrel, their highest level in two weeks, following a deadly strike on Riyadh's international airport over the weekend. The rise in oil prices was limited after Trump announced an energy ceasefire agreement between the U.S. and Russia.
Earnings will be a key driver this week, with Wells Fargo, Goldman Sachs, Citigroup and J.P. Morgan reporting tomorrow ahead of the open.
S&P 500 earnings are expected to rise 30.6% in Q3. Last week, major indices ended higher on optimism surrounding an AI-driven earnings season and hopes that the Fed could avoid a near-term rate hike.
Markets are pricing in just a 17% probability of a Fed rate hike in October, but still see an 86% chance of an increase before year-end.
These expectations will remain in focus ahead of Wednesday's inflation data and a speech from Federal Reserve Chair Kevin Warsh at the IMF meeting on Thursday.
Treasury yields climbed to 24-year highs earlier this month as elevated energy prices fuelled inflation concerns. The U.S. Treasury market is closed for Columbus Day on Monday.
Corporate Movers
Salesforce is rising 4% after Bank of America upgraded the stock from Underperform to Buy, arguing that AI could deepen dependence on the software provider rather than disrupt its business.
URN is up 3.3% following reports that Anthropic had entered into a multi-year cloud deal with the data centre firm.
Biogen is rising 2% after J.P. Morgan upgraded the biotech company to Overweight from Neutral, citing several clinical readouts in 2027 as potential catalysts.
Dow Jones Forecast – Technical Analysis
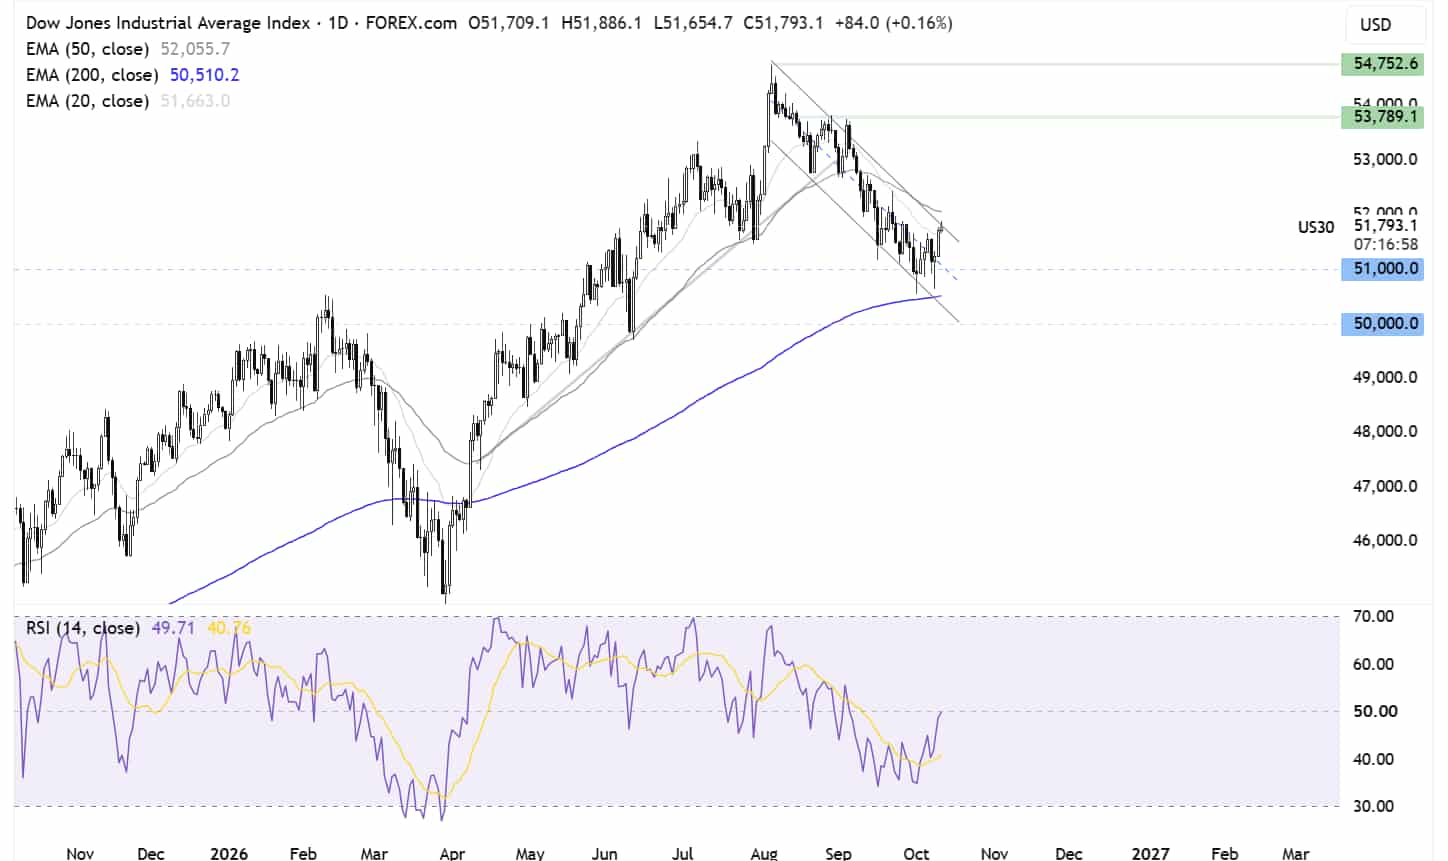
The Dow Jones continues to trade within a descending channel dating back to 5 August. The index is finding support above the 200 EMA, while last week's hammer candle, with its long lower wick, suggests buyers stepped in at lower levels. This could indicate a near-term floor, although further gains are needed to confirm a recovery.
Buyers would need to break above the 50 EMA and the upper boundary of the falling channel near 52,000. A move above this area would make the outlook more constructive, with attention turning to 53,700, the September high.
On the downside, sellers would need to break below the 50,500 weekly low and the 200 EMA to regain momentum, opening the door towards 50,000.
FX Markets – Dollar at a Fresh 18-Month High
The U.S. dollar has extended gains to a fresh 18-month high as escalating Middle East tensions keep investors cautious ahead of U.S. inflation data this week. Bullish positions rose to around $36 billion in the week to October 7, up from just $8.4 billion three weeks earlier, largely at the expense of the euro.
EUR/USD is falling amid a stronger U.S. dollar, with the outlook for the euro closely tied to French sovereign bond yields. Presidential frontrunner Le Pen offered reassurances last week about reining in government spending, which markets appeared to welcome. However, recent protests and marches in support of higher education funding highlight the challenges of improving public finances while maintaining voter support. Markets have scaled back ECB rate hike expectations amid the turmoil in France.
GBP/USD is little changed despite the stronger dollar. Sterling has remained relatively range-bound in recent weeks amid concerns over this month's budget. Markets are pricing in around a 90% probability that the Bank of England will hike rates at its next meeting on November 5, followed by a series of increases in 2027 that could take the base rate to 4.75%.
This contrasts with economists' expectations, with no change to UK interest rates anticipated until 2027 and the next move more likely to be a cut.
Oil rises to a 2-week high
Oil prices have recouped earlier losses and moved higher as investors weigh the prospect of additional Russian diesel supplies and a Russia-Ukraine energy ceasefire against ongoing tensions in the Middle East.
Trump announced an agreement for Russia to supply over 300,000 metric tonnes of diesel, with more to follow, sending gasoline futures down 3%. He also said Ukraine and Russia had agreed to an energy ceasefire, although Zelensky is still awaiting details and Moscow has yet to comment.
However, hopes of easing supply pressures are being offset by renewed attacks around the Strait of Hormuz and strikes on Saudi Arabia. Iran has rejected a U.S. proposal to reopen the strait, while Trump said Washington was considering joining Saudi strikes against the Houthis.
Meanwhile, Hurricane Isaias has disrupted U.S. Gulf Coast production, with over 60% reportedly offline ahead of the storm.
For now, additional Russian supplies could ease pressure on refined products, but continued disruption to Gulf shipping keeps crude supply risks elevated.
Latest market news




Open an account today
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
US Dollar Freight Train Drives EUR/USD, GBP/USD to Fresh Lows
A hawkish Fed and growing jitters around AI have pushed a continued rally in the Greenback, and there’s not yet an end in sight.

S&P500 Forecast: SPX falls as Anthropic drops post IPO
U.S. stocks are trading mixed with tech leading the losses as the mood sours despite Anthropic’s record-breaking IPO yesterday, which failed to calm AI jitters and revive the AI trade.

Gold and Silver's Deepening Dollar Dilemma
The dollar has broken higher, gold and silver have been crushed, and US financial conditions are tightening rapidly. Our historical analysis suggests this is no ordinary precious metals selloff.

From time to time, StoneX Financial Pty Ltd (“we”, “our”) website may contain links to other sites and/or resources provided by third parties. These links and/or resources are provided for your information only and we have no control over the contents of those materials, and in no way endorse their content. Any analysis, opinion, commentary or research-based material on our website is for information and educational purposes only and is not, in any circumstances, intended to be an offer, recommendation or solicitation to buy or sell. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. No representation or warranty is made, express or implied, that the materials on our website are complete or accurate. We are not under any obligation to update any such material.
As such, we (and/or our associated companies) will not be responsible or liable for any loss or damage incurred by you or any third party arising out of, or in connection with, any use of the information on our website (other than with regards to any duty or liability that we are unable to limit or exclude by law or under the applicable regulatory system) and any such liability is hereby expressly disclaimed.