


FTSE 100 rises for fifth day
The FTSE 100 is up 0.3% this morning and the blue-chip index is on course to book its fifth consecutive day of gains if it can close higher today.
The index enters the final day of the week in strong form as it shrugs off the increasingly hawkish views out of the Federal Reserve and European Central Bank this week as both signalled more rate rises are needed to bring down inflation. Meanwhile, we saw the Bank of Japan leave its policy unchanged overnight as it takes a slightly different tact and keeps the economy atop its agenda over inflation, during what was a largely positive session in Asia.
Turning to the economic calendar today, we have eurozone and Italian inflation data out this morning. In the US, we have the Michigan consumer sentiment index this afternoon.
FTSE 100 analysis: UK 100 tests resistance
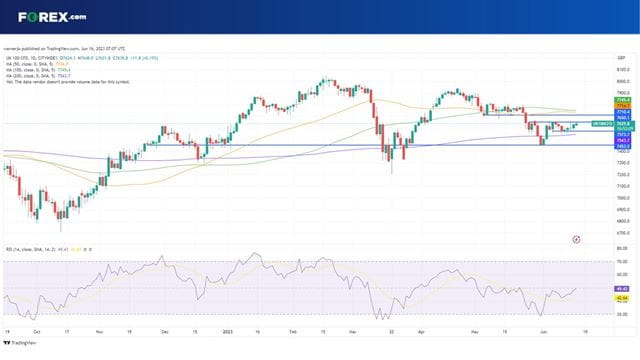
The index has drifted between a ceiling of 7,650 and the June-low of 7,452 this month and we are waiting for the index to break out of this range to decide where it is headed next.
Notably, the index is testing the upper end of that range today and a break above here could pave the way for it to climb toward 7,710, marking the level of support that held throughout most of May.
On the downside, we have seen signs that 7,573 is emerging as a new level of support over the past week, which may hold the index up if it comes under pressure before the June-low comes back into play.
Top UK stock news
Tesco is down 0.4% this morning. The UK’s largest supermarket said there are ‘encouraging early signs that inflation is starting to ease across the market’ as it revealed like-for-like sales rose 8.2% in the 13 weeks to May 27, with revenue amounting to £14.8 billion. Growth was strongest in the UK at 9%, where Tesco has maintained market share and gained ground over premium retailers with its Finest range. That was complimented by 7.3% growth in Ireland and an 8.4% LfL rise from wholesaler Booker. Central Europe remained the laggard after seeing LfLs rise just 1.1% as inflation continues to test consumer spending, particularly on discretionary goods. Tesco reiterated its full year outlook that is looking to hold retail profits broadly flat from last year at around £2.5 billion.
ITV is down over 1% after confirming it is considering buying production firm All3Media from current owner Warner Bros Discovery and Liberty Global to bolster its studio. A report from Reuters said Warner Bros Discovery could sell its stake in All3Media to help raise funds to pay down debt while Liberty Global could seek to retain an interest in the enlarged entity if a deal can be struck. All3Media could come with a price tag north of £1 billion, the report said. ITV released a statement this morning that simply said ‘there can be no certainty as to whether any transaction will take place, nor as to the terms of any such transaction.’
Travis Perkins is down 6.7% and at eight months lows after it warned adjusted operating profit will be down almost 19% this year at around £240 million. The retailer said market conditions have not eased in 2023 as much as hoped and that volumes continue to be tested by weaker demand from both the new housing and DIY markets. It blamed higher interest rates and weaker consumer confidence. It said other end markets - including commercial, industrial, infrastructure and public sector housing, as well as its Toolstation unit - are performing better. That represents a cut to its guidance from the £272 million of profit it was targeting back in April.
Currys is up 2.2% after launching a strategic review of its Greek business named Kotsovolos, which could lead to it selling the business. Kotsovolos, which is also emerging in Cyprus, is profitable but Currys said it does not believe this is reflected in its valuation. ‘Given the robust economic outlook for Greece and future growth opportunities for the business, the board believes that now is the right time to explore all options for Kotsovolos,’ the firm said.
GSK is up 0.2% after the pharmaceutical giant said the US Food & Drug Administration has extended the review looking at its new drug application for momelotinib by three months, with a decision now to be made by September 16. GSK hopes the drug may help people with a rare blood cancer named myelofibrosis.
Glencore is up 1.1% after completing the sale of the Cobar copper mine in Australia for $775 million in cash and $100 million in shares in the buyer, Metals Acquisition Corp. There is also another $75 million due in 12 months and another $150 million could be paid depending on how copper prices perform. Glencore has also secured a 1.5% net smelter return royalty from the mine.
Oil giants BP and Shell are up 0.3% and 0.5%, respectively, this morning as oil prices climb higher, with Brent moving back above $75 a barrel for the first time in a week this morning. Notably, Shell said its Olympus production platform in the Gulf of Mexico is offline for planned maintenance.
Vodafone is up 0.4% after reaching an agreement with unions over managing just over 1,000 job cuts in Italy, according to Reuters. The telecoms giant, which this week struck a deal to combine its UK business with rival Three, is looking to cut costs and said the deal should transform its Italian business while limiting redundancies. Still, the cuts are significant considering Vodafone has around 5,700 employees in Italy, according to its last annual report.
Mitchells & Butlers is up 2.3% amid news it could be the front runner to buy pub-restaurants from Whitbread, according to the Times. Whitbread is thought to be considering offloading about 250 of its 440 pub-restaurants up for sale but is only considering established pub operators as buyers, the report said. Other contenders vying for the sites include Greene King, Heineken, Marston’s and Punch. Whitbread is up 1.1% today.
Fellow pub operator Fuller Smith & Turner has been cut to Hold from Buy by Stifel, which has a price target of 610p on the company. The stock is down 1.4% at 580p this morning.




