





Market Brief Tariff Man strikes again
Things were going quite well, then Trump tweeted.
Share this:

Stock market snapshot as of [2/12/2019 3:11 pm]
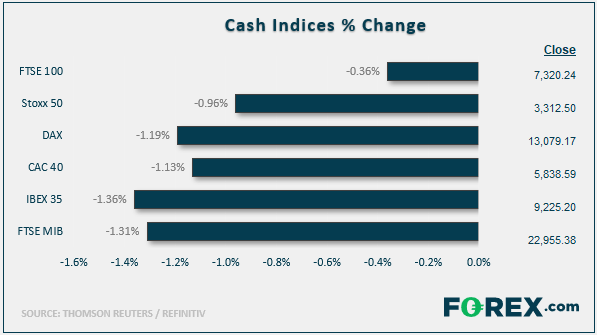
- Things were going quite well, then Trump tweeted. That’s a (somewhat facile) description of not just the first half of Monday’s global market proceedings, but apt for numerous sessions over the last 18 months or so. Monday may be a mild reminder that with global equities standing around cycle highs into the end of the year, whilst much remains inconclusive on trade, geopolitical and political fronts, tail risks may be higher than currently looks priced in
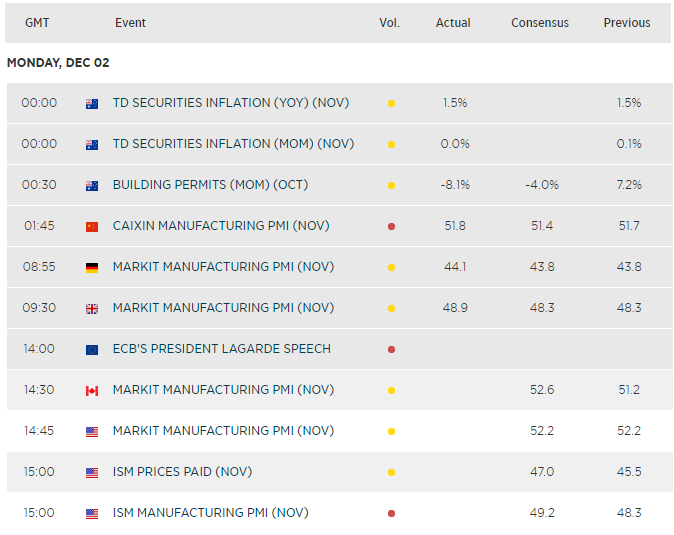
- Earlier, data from Caixin’s closely watched manufacturing PMI for China showed the sector growing for its first two-month stretch since the middle of 2018, and at the fastest rate of expansion for three years. Resilience in the world’s second-largest economy revives hopes of a base in its recent downturn. If corroborated it would have major implications for global markets into the New Year
- The official Chinese purchasing managers’ index, out over the weekend, also showed the sector returning to growth in November, boosted by a pick-up in production and new orders
- The DAX was among key European indices to benefit, albeit fleetingly
- After the U.S. President’s comments though, the German index slumped sharply, trading down 0.7% in the half hour before the U.S. cash open. Wall Street index futures retained a foothold in positive territory though were also markedly below the levels seen before the latest U.S. tariff news
Stocks/sectors on the move
- A mining and steel theme is inescapable and understandable after China's surprise manufacturing uptick and U.S. Presidential contributions. Hopes for a rebound in steel and base metal demand are being moderated after Trump tweeted that he would "restore the Tariffs on all Steel & Aluminum" from Brazil and Argentina
- BHP, Rio Tinto, Anglo American and Glencore were 0.7%-1% higher a short while ago, partly benefiting from positive brokerage commentary by RBC and Credit Suisse. These gains have been pared by Trump’s comments
- Fresnillo, the precious metals group, missed out on the day’s updraft entirely, dropping as much as 4% after lowering production guidance whilst raising capex expectations
- Newmont Gold Corp, the world's largest bullion producer by volume, also dropped production guidance whilst upping its 2020 cost outlook. It did however lower forecasts of its 2021/22 all-in sustaining costs. The trade slightly higher
- Ocado is a key UK standout. It slumps 7%-8% after surging higher by around double that rate on Friday. The online supermarket and technology platform has launched a convertible bond expiring in 2025. Institutions often hedge such bonds by shorting stock
FX snapshot as of [2/12/2019 2:36 pm]
View our guide on how to interpret the FX Dashboard
FX markets including contributions from Senior Technical Analyst Fawad Razaqzada
- ‘Core’ fixed income markets have opted to discount some of Monday’s Trump factor, instead continuing to take their cue from promising global economic hints. Gold looks weak. As well as China’s manufacturing data, German factories posted a better than forecast showing in November, even if they still showed the sector was shrinking. Benchmark Eurozone bunds remain pressured as do U.S. Treasurys
- There’s little outright advantage for the dollar. DXY has slumped from 98.37 to 98.17 just now, as the quest for safety appears to ebb
- The Kiwi leads in the G10 amid a government spending pledge as commodity currencies see resilient flows in the wake of China’s indications
- The Canadian dollar is the weakest major on further signs that the BOC is preparing markets for a change of policy stance, if not outright rate policy changes, as early as its rate announcement scheduled for Wednesday
- The euro remains in familiar ranges albeit the single currency enjoys another positive session above $1.10. The move helps affirm last week’s 1.09812 intermediate low
- Elsewhere, the lira was steady as Turkey’s economy continued its gradual recovery from recession in the third quarter. GDP expanded by 0.9% following a contraction of 1.6% in the previous quarter, though the Q3 rise was lower than consensus
Upcoming economic highlights
Stock market snapshot as of [2/12/2019 2:36 pm]
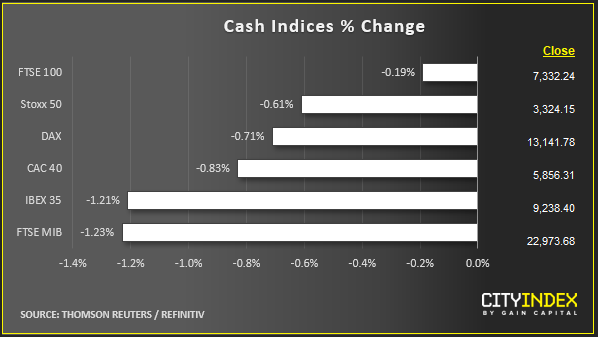
- Things were going quite well, then Trump tweeted. That’s a (somewhat facile) description of not just the first half of Monday’s global market proceedings, but apt for numerous sessions over the last 18 months or so. Monday may be a mild reminder that with global equities standing around cycle highs into the end of the year, whilst much remains inconclusive on trade, geopolitical and political fronts, tail risks may be higher than currently looks priced in
- Earlier, data from Caixin’s closely watched manufacturing PMI for China showed the sector growing for its first two-month stretch since the middle of 2018, and at the fastest rate of expansion for three years. Resilience in the world’s second-largest economy revives hopes of a base in its recent downturn. If corroborated it would have major implications for global markets into the New Year
- The official Chinese purchasing managers’ index, out over the weekend, also showed the sector returning to growth in November, boosted by a pick-up in production and new orders
- The DAX was among key European indices to benefit, albeit fleetingly
- After the U.S. President’s comments though, the German index slumped sharply, trading down 0.7% in the half hour before the U.S. cash open. Wall Street index futures retained a foothold in positive territory though were also markedly below the levels seen before the latest U.S. tariff news
Stocks/sectors on the move
- A mining and steel theme is inescapable and understandable after China's surprise manufacturing uptick and U.S. Presidential contributions. Hopes for a rebound in steel and base metal demand are being moderated after Trump tweeted that he would "restore the Tariffs on all Steel & Aluminum" from Brazil and Argentina
- BHP, Rio Tinto, Anglo American and Glencore were 0.7%-1% higher a short while ago, partly benefiting from positive brokerage commentary by RBC and Credit Suisse. These gains have been pared by Trump’s comments
- Fresnillo, the precious metals group, missed out on the day’s updraft entirely, dropping as much as 4% after lowering production guidance whilst raising capex expectations
- Newmont Gold Corp, the world's largest bullion producer by volume, also dropped production guidance whilst upping its 2020 cost outlook. It did however lower forecasts of its 2021/22 all-in sustaining costs. The trade slightly higher
- Ocado is a key UK standout. It slumps 7%-8% after surging higher by around double that rate on Friday. The online supermarket and technology platform has launched a convertible bond expiring in 2025. Institutions often hedge such bonds by shorting stock
FX snapshot as of [2/12/2019 2:36 pm]
View our guide on how to interpret the FX Dashboard
FX markets including contributions from Senior Technical Analyst Fawad Razaqzada
- ‘Core’ fixed income markets have opted to discount some of Monday’s Trump factor, instead continuing to take their cue from promising global economic hints. Gold looks weak. As well as China’s manufacturing data, German factories posted a better than forecast showing in November, even if they still showed the sector was shrinking. Benchmark Eurozone bunds remain pressured as do U.S. Treasurys
- There’s little outright advantage for the dollar. DXY has slumped from 98.37 to 98.17 just now, as the quest for safety appears to ebb
- The Kiwi leads in the G10 amid a government spending pledge as commodity currencies see resilient flows in the wake of China’s indications
- The Canadian dollar is the weakest major on further signs that the BOC is preparing markets for a change of policy stance, if not outright rate policy changes, as early as its rate announcement scheduled for Wednesday
- The euro remains in familiar ranges albeit the single currency enjoys another positive session above $1.10. The move helps affirm last week’s 1.09812 intermediate low
- Elsewhere, the lira was steady as Turkey’s economy continued its gradual recovery from recession in the third quarter. GDP expanded by 0.9% following a contraction of 1.6% in the previous quarter, though the Q3 rise was lower than consensus
Upcoming economic highlights
Latest market news




Open an account today
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Silver Analysis: XAG/USD Continues to Set New Lows for the Year
It continues to be a challenging period for the silver market in the short term, as the precious metal remains under pressure and keeps posting new lows on a consistent basis. Over the last five trading sessions alone, silver has fallen nearly 12%, a move that has highlighted a strong bearish bias not seen in the market for several months.

ASX 200 Outlook: Potential to Bounce Sits on a Knife Edge
ASX 200 bounce prospects remain on a knife edge as oversold technicals clash with weak financials, commodity pressures and global risk aversion.


Gold Outlook: Asia Buys the Dip, US Hammers the Rip
Asia buys the dip, the US sells the rip. Hourly gold, dollar and Treasury yield data reveal a regional divide that has become especially pronounced since September.

From time to time, StoneX Financial Pty Ltd (“we”, “our”) website may contain links to other sites and/or resources provided by third parties. These links and/or resources are provided for your information only and we have no control over the contents of those materials, and in no way endorse their content. Any analysis, opinion, commentary or research-based material on our website is for information and educational purposes only and is not, in any circumstances, intended to be an offer, recommendation or solicitation to buy or sell. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. No representation or warranty is made, express or implied, that the materials on our website are complete or accurate. We are not under any obligation to update any such material.
As such, we (and/or our associated companies) will not be responsible or liable for any loss or damage incurred by you or any third party arising out of, or in connection with, any use of the information on our website (other than with regards to any duty or liability that we are unable to limit or exclude by law or under the applicable regulatory system) and any such liability is hereby expressly disclaimed.