US futures
Dow futures 0.3%, S&P futures 0.43% & Nasdaq futures 0.58%
In Europe
- FTSE 0.86% & DAX 0.09%
- Stocks pop after the NFP smashes forecasts
- 130k jobs were added vs 70k expected, unemployment falls to 4.3%
- Fed rate cut expectations are pushed out to July
- Oil steadies after yesterday’s jump

US NFP beats forecasts & unemployment drops
US stocks are rising following the stronger-than-expected US nonfarm payroll report
The delayed report, due to the partial US government shutdown, showed that 130k jobs were added in January, well ahead of the 70k forecast and significantly up from the 48k in December. Meanwhile, the unemployment rate unexpectedly fell to 4.3%, down from 4.4%, and wage growth was also stronger than expected, at 0.4% month-on-month.
In the three months to January 2026, payroll gains averaged 73,000, a healthy figure despite a slowdown in labour supply and the fastest 3-month average since February 2025.
This was a solid report across headline job creation, unemployment, and wage growth, easing concerns over the health of the US labour market. Following the data, the markets have pushed back on expectations for the next rate cut by the Federal Reserve to July, compared to June previously.
Attention will now turn towards Friday's inflation data for further clues on when the Fed could cut rates.
Following the release, U.S. Treasury yields have pushed higher, as has the USD, and U.S. stocks are trading at session highs in a risk-on rally. Tech stocks are outperforming in a rare showing.
Benchmark stock indices continued to trade near all-time highs despite concerns that AI could hurt certain sectors. Investors have pivoted towards companies they see as being less likely to be negatively affected and away from those expected to be disrupted. This fueled a sellout from software stocks last week.
Corporate news
Lyft is falling 17% after bookings in Q4 were in line with expectations. However, first-quarter profit forecasts fell slightly short of expectations.
Ford is up 1% after fourth-quarter revenue came in at $42.4 billion, above consensus estimates of $41.83 billion. However, the automaker reported its widest quarterly earnings miss in four years, at $0.13 per share, below the $0.19 expected.
Nasdaq 100 forecast – technical analysis.
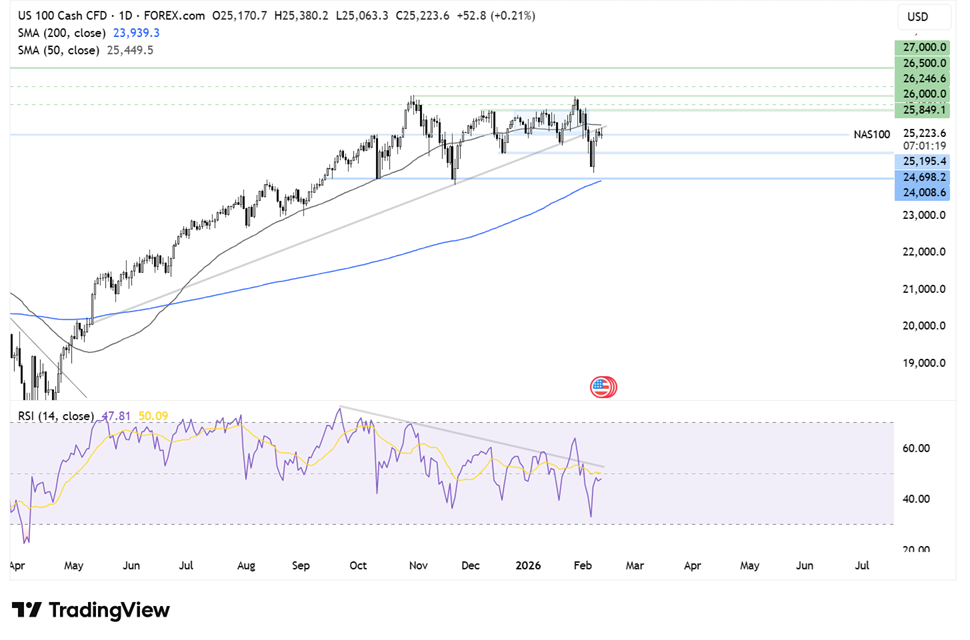
The Nasdaq 100 has recovered from the 24,150 low, rising above the 25,200 resistance and testing the rising trendline. Buyers will need to rise above the trendline and 50 SMA at 25,460 to extend gains towards 25,865, the December high, ahead of 26,250, the record high. However, it's worth noting that momentum remains weak. A break below 25,200 brings 24,700, the December low, into focus ahead of 24,000.
FX markets – USD rises, USD/JPY rises
The USD is rising following the solid US NFP report, which lifted Treasury yields and boosted the USD as investors pushed out rate-cut expectations.
EUR/USD is falling away from 1.19 amid a stronger USD and a quiet eurozone economic calendar. Data earlier this week showed a solid jump in eurozone investor sentiment, while ECB president Christine Lagarde 3rd she believes inflation will return to the 2% target, having dipped to 1.7% in January.
USD/JPY has recovered from earlier losses as the USD rebounded. The yen had strengthened earlier in the day following Takeichi's landslide victory in the weekend elections. Hopes of stronger growth, lifting hawkish BoJ bets, and political clarity saw a reduction in shorts.
Oil rises as US-Iran tensions remain in focus.
Oil prices are rising on Wednesday, boosted by escalating geopolitical risks, with US-Iran talks in focus. Meanwhile, draws from key stockpiles suggested stronger demand.
US-Iran tensions in the Middle East remain under the spotlight with Trump saying that he was considering sending a second aircraft carrier to the Middle East, even as negotiations between the US and Iran aimed at averting a new conflict were set to resume. This increased the risk premium on the oil price.
The broad expectation is still that the US and Iran will strike a deal on its nuclear missile programme.
Crude drawdowns from stocks held independently at the Amsterdam, Rotterdam, and Antwerp refining and storage hubs indicate some market tightness. However
U.S. oil inventory data from the API showed inventories rose by 13.4 million barrels in the week ending February 6th. EIA data is due later today.