US futures
Dow futures 0.71%, S&P futures -0.45% & Nasdaq futures -0.81%
In Europe
FTSE -0.05% & DAX -0.01%
- Stocks slip after the Fed’s hawkish cut
- Trump lowers tariffs on China
- Alphabet rises, MSFT & META drop after earnings
- Oil steadies after inventory data ahead of OPEC+
Fed’s hawkish cut, Mag 7 earnings
The Nasdaq 100 and S&P 500 are falling away from record highs on Thursday, pulled lower by the tech sector, particularly Meta and Microsoft, while the Dow Jones posts gains.
Meta and Microsoft have fallen amid concerns about surging AI spending, unnerving investors already worried about the pace of monetary policy easing following the Federal Reserve's decision yesterday.
While the Fed cut interest rates by 25 basis points, as expected, Federal Reserve chair Jerome Powell raised questions about the Fed's ability to cut rates again in December, dashing market optimism that had gotten carried away.
Fed Chair Powell’s warning to the market to show restraint saw investors lower December rate-cut expectations from above 90% before the meeting to 70% at the time of writing.
Meanwhile, U.S. President Trump and China's Xi Jinping’s meeting did little to improve overall sentiment. Trump agreed to rein in some tariffs on Chinese imports in exchange for Beijing resuming soybean purchases, keeping rare exports moving, and cracking down on fentanyl trafficking.
However, the move fell short of an all-out trade deal and could be seen more as a de-escalation than a marked change in the relationship.
Corporate news
Alphabet has risen by over 7% on strong results, boosted by revenue from global cloud and YouTube advertising. The tech giant posted EPS of $3.10 per share, well above the $2.33 expected. Revenue was $102.35 billion U.S. dollars, also ahead of $99.89 billion forecast.
Meta has dropped over 10% after lifting its capital expenditure outlook to invest more in AI. Meta expects to spend between $70 to $72 billion, up from $66 billion to $72 billion previously. This overshadowed better-than-expected third-quarter earnings and revenue.
Microsoft is falling after warning that capital spending will accelerate this fiscal year, which overshadowed stronger than forecast results as revenue from Azure cloud jumped 40%
Amazon and Apple are due to report after the close.
Nasdaq 100 forecast – technical analysis.
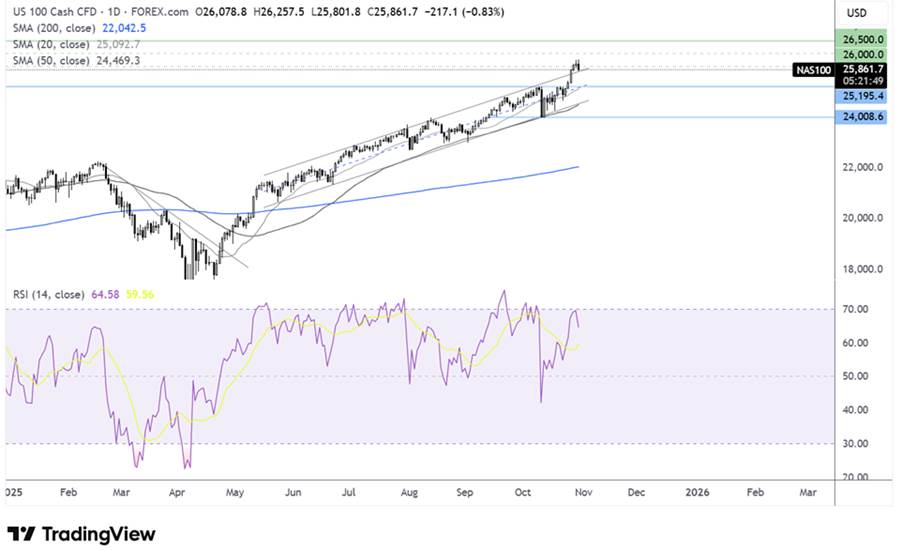
The Nasdaq 100 has broken out above its rising channel, surging to a record high above 26250 before easing back below 26000, to test the upper band of the rising channel. The RSI has moved away from overbought territory. The trend remains bullish, with no concrete signs of a reversal. Support can be seen at 25,200, the October 9 high. It would take a break below 23,950 to create a lower low, altering the chart's structure. Buyers will look to rise above 26,250 to extend gains to 26,500 and 27,000.
FX markets – USD rises, USD/JPY soars
The U.S. dollar is rising as investors react to optimism from Trump surrounding U.S.-China trade talks and as attention turns to the FOMC rate decision, where the central bank is expected to cut rates.
EUR/USD is falling and a stronger USD, but has pared some of those losses following the ECB rate decision. The ECB left rates unchanged at 2% for a third straight meeting with minimal change to guidance. Q3 GDP was slightly stronger than expected at 0.3% QoQ.
The USD/JPY has risen above 154 to a multi-month high after the hawkish Fed cut and the dovish pause from the BoJ, both of which caught the market by surprise. The BoJ appears to be prepared for the Spring wage negotiation data before moving.
Oil steadies after inventory data & ahead of OPEC
Oil prices are unchanged on Thursday for a second straight day as the market weighs inventory data, the Fed rate decision, and developments in China-US trade talks.
Trump's lowering of tariffs on China from 57% to 47% in a one-year deal showed a de-escalation rather than a structural change in the US-China relationship. Still, it’s a move in the right direction to support the oil demand outlook.
Data yesterday showed that inventories fell by 6.86 million in the week to October 24, significantly more than the 211k forecast.
OPEC+ is due to meet this Sunday and is expected to announce a further 137k barrel per day cut.