


NZD Hit as Softer CPI Keeps RBNZ Easing in Play
Despite some sticky spots, New Zealand’s latest CPI report points to fading inflation risks—keeping a further RBNZ cut firmly in play.
Share this:
- Q2 CPI rose 2.7% y/y vs 2.8% expected, 2.6% RBNZ forecast
- Core inflation ticked up to 2.7% but stayed within target
- Market sees 85% chance of RBNZ cut in August
- NZD/USD weaker, stays in firm downtrend
NZD Summary
Consumer prices in New Zealand rose less than forecast in the June quarter, delivering a modest decline in the New Zealand dollar. While marginally above what the Reserve Bank of New Zealand (RBNZ) forecast in May, the underlying detail of the report points to the likelihood of at least one additional rate cut from policymakers over the remainder of the year.
Inflation Remains Contained
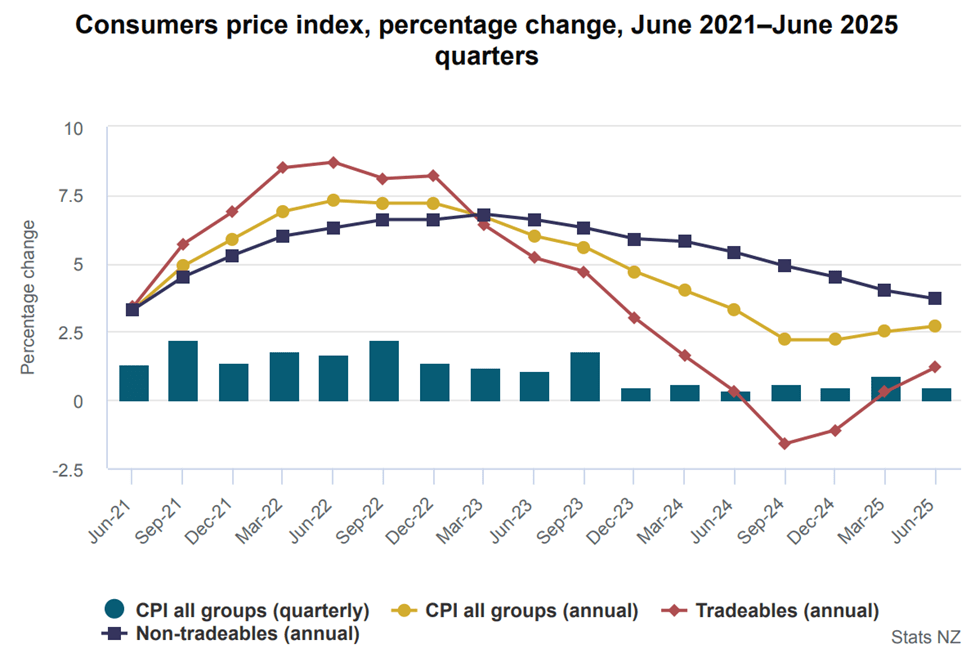
New Zealand’s CPI rose 0.5% in the June quarter and 2.7% over the year, a touch hotter than the RBNZ’s 2.6% forecast but below the 2.8% pace expected by markets. It marked a slight pickup from 2.5% in Q1 but remained within the RBNZ’s 1–3% target band for a fourth consecutive quarter. The biggest driver of the annual increase was local authority rates, up 12.2% and accounting for 13% of the rise—though that lift was captured back in the September 2024 quarter. Petrol prices fell 8% over the year, helping contain the headline result. Excluding petrol, CPI rose 3.2% annually.
Source: StatsNZ
Non-tradeable prices—which typically reflect domestic demand and supply factors—rose 0.7% for the quarter and 3.7% over the year, continuing the disinflationary trend established in early 2023 when it peaked at an annual rate of 6.8%. Tradable prices which largely reflect offshore factors increased by 0.3% for the quarter, seeing the annual pace accelerate modestly to a still-weak 1.2%.
Core inflation, excluding food, household energy and vehicle fuels, rose 0.4% on the quarter and 2.7% over the year, up from 2.6% in Q1 but still within target. The RBNZ’s sectoral factor model, its preferred measure of underlying inflation, will be released at 3pm Wellington (1pm Sydney).
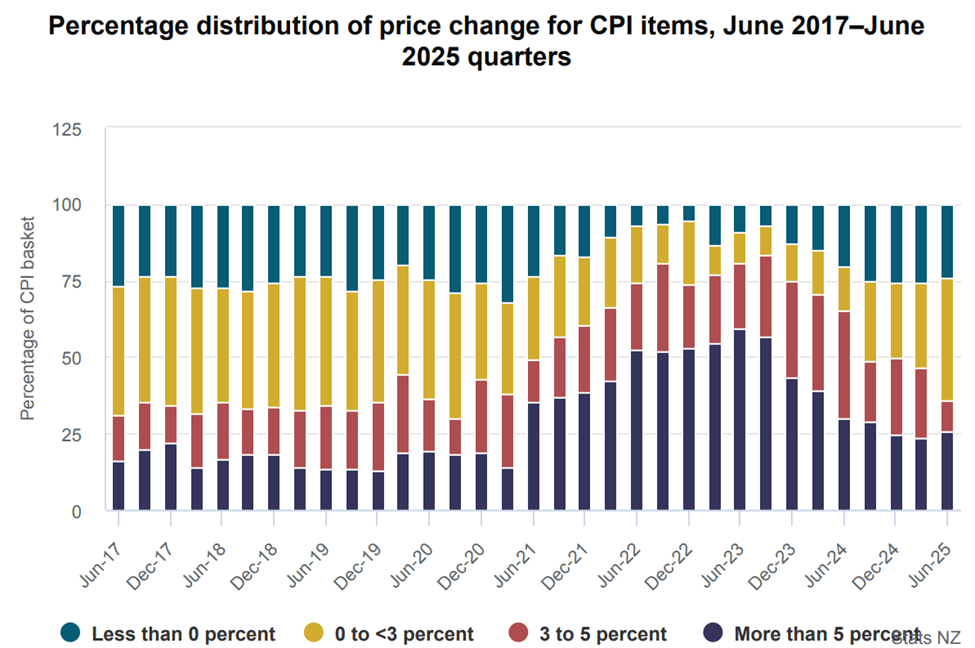
Adding to confidence that inflationary pressures remain contained despite 225 basis points worth of rate cuts from the RBNZ already this cycle, the proportion of the CPI basket with price increases of 3% or less increased to 64.3% in Q2, the highest proportion since Q3 2020.
Source: StatsNZ
Keeping RBNZ Rate Cuts in Play
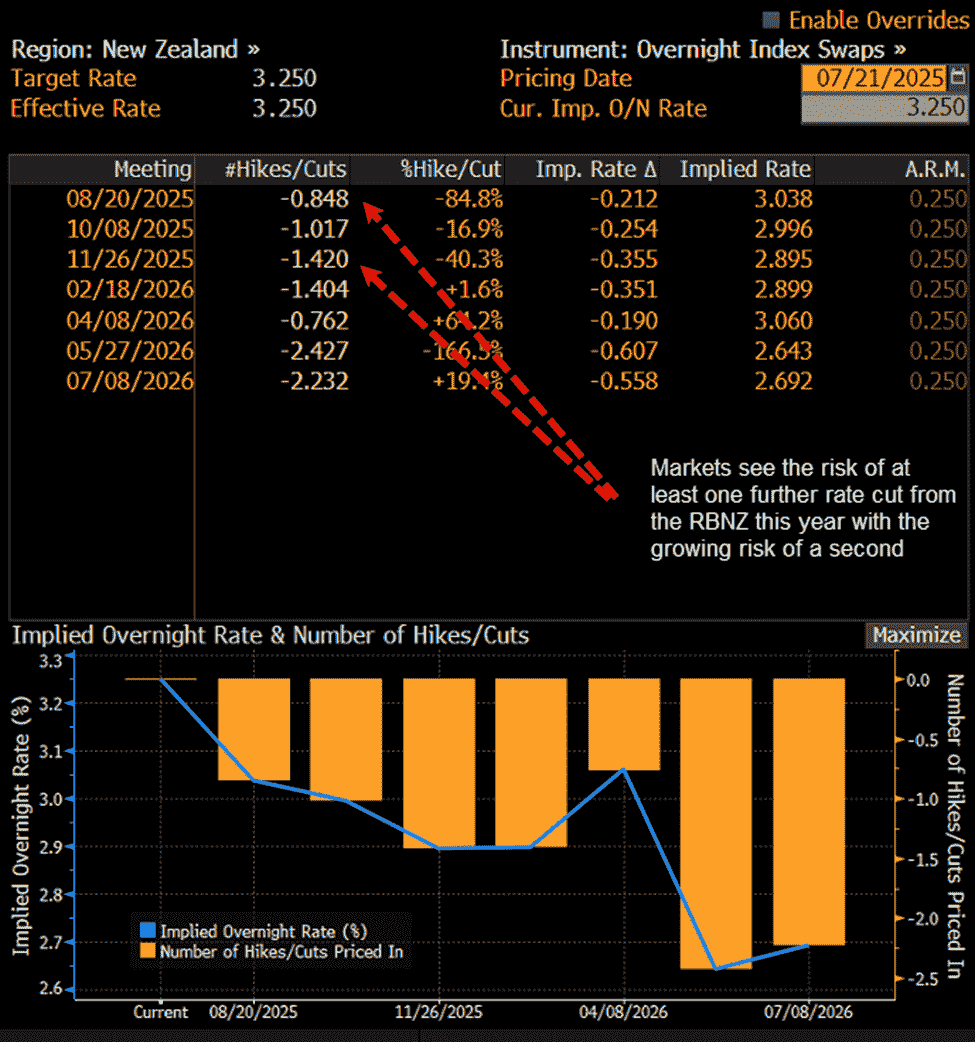
Following the inflation report, swaps markets put the probability of the RBNZ reducing the cash rate by a further 25 basis points to 3% on August 20 at 85%. Looking further out, a full cut it priced by the bank’s October meeting with a 42% probability seen of a second 25-pointed by year-end.
Source: Bloomberg
With markets paring expectations for multiple rate cuts from the Federal Reserve this year, it’s combined with the slightly softer Kiwi inflation report to push NZD/USD weaker in early Asian trade on Monday.
NZD/USD Remains in Downtrend
Source: TradingView
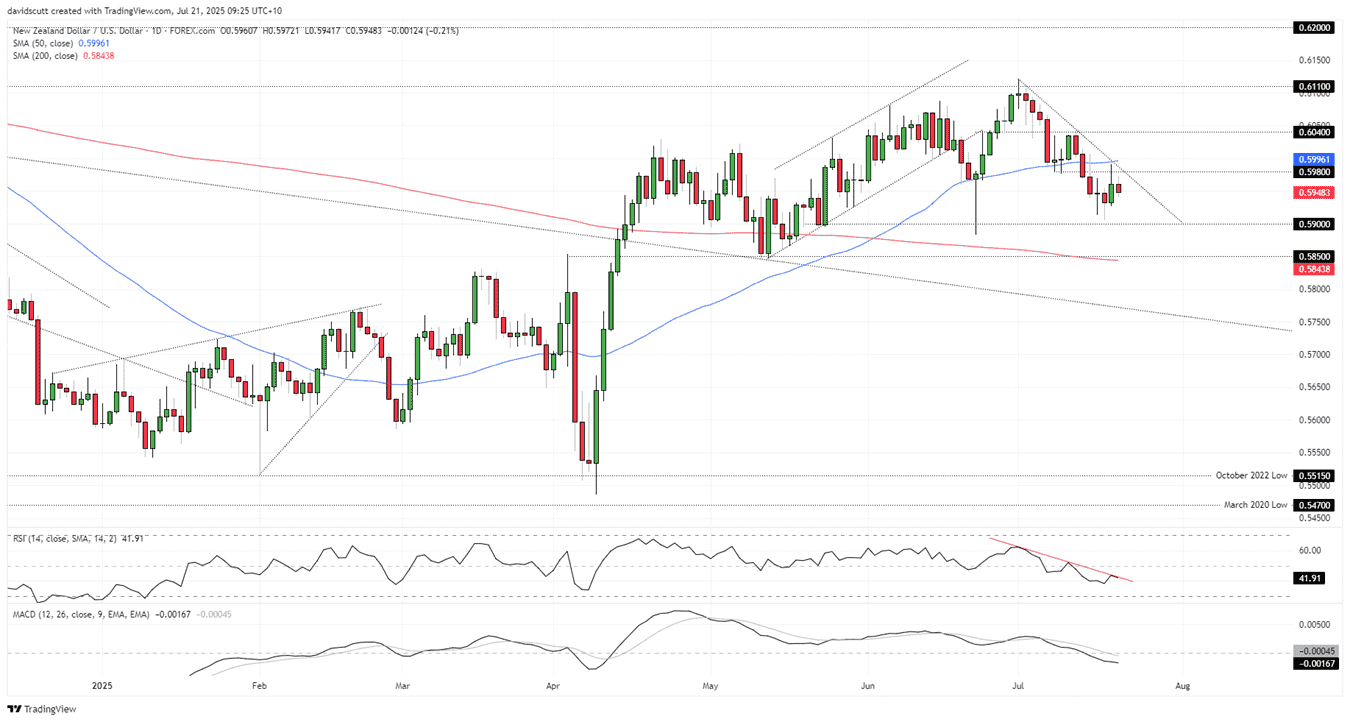
For the moment, NZD/USD remains a sell-on-rallies play, sitting in an established downtrend with momentum indicators like RSI (14) and MACD trending lower and sitting in negative territory, favouring a bearish bias.
Resistance kicks in at .5980 and again at the 50-day moving average located some 16 pips above. On the downside, bids have been noted recently ahead of support at .5900. If they were to be overrun, .5850 and the 200-day moving average would be the next two downside levels of note.
AUD/NZD Key Reversal?
Source: TradingView
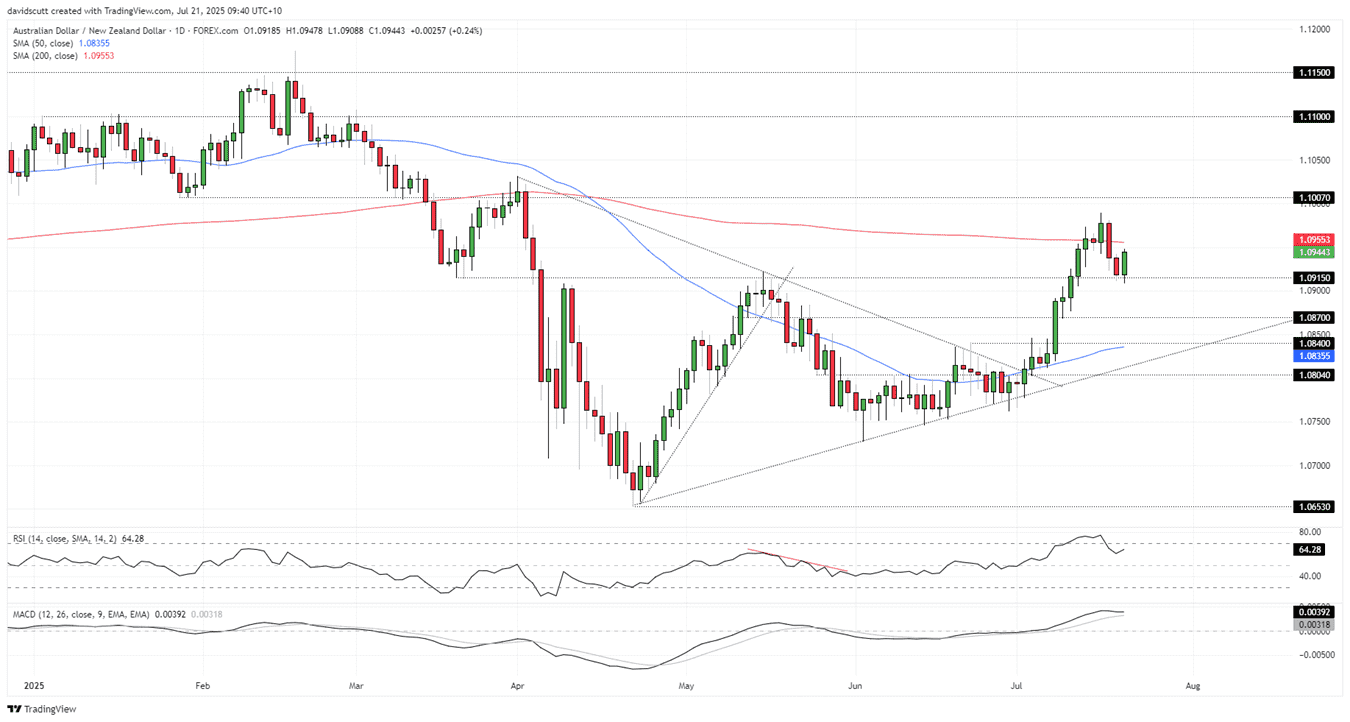
Looking briefly at AUD/NZD, the pair found buying support late last week at 1.0915 and again in early trade on Monday, with the inflation report helping to spark a reversal back above Friday’s opening level. Things could quickly change, but the daily candle will print as a key bullish reversal if it closes at or above these levels, pointing to the potential for further gains ahead should it eventuate.
Levels to watch on the topside include the 200-day moving average, Wednesday’s high around 1.0990, along with horizontal resistance at 1.1007. Benearth 1.0915, 1.0870 and 1.0840 are levels of note.
From a directional perspective, a bullish bias remains favoured with MACD and RSI (14) remaining in positive territory even with the moderation in topside momentum seen in recent days.
Latest market news




Open an account today
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
US Dollar Freight Train Drives EUR/USD, GBP/USD to Fresh Lows
A hawkish Fed and growing jitters around AI have pushed a continued rally in the Greenback, and there’s not yet an end in sight.

Japanese Yen Forecast: USD/JPY Bulls Falter at Major Resistance—Critical Range Break in Focus 11 20 2026
USD/JPY’s latest retreat puts the September recovery under scrutiny, with nearby support offering bulls their next opportunity to respond.


USD/JPY Outlook: Yen Strength Builds as Carry Trades Come Under Threat
Rising equity volatility threatens yen carry trades as USD/JPY struggles at 160 resistance and AUD/JPY leads a broader recovery in the Japanese yen.

From time to time, StoneX Financial Pty Ltd (“we”, “our”) website may contain links to other sites and/or resources provided by third parties. These links and/or resources are provided for your information only and we have no control over the contents of those materials, and in no way endorse their content. Any analysis, opinion, commentary or research-based material on our website is for information and educational purposes only and is not, in any circumstances, intended to be an offer, recommendation or solicitation to buy or sell. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. No representation or warranty is made, express or implied, that the materials on our website are complete or accurate. We are not under any obligation to update any such material.
As such, we (and/or our associated companies) will not be responsible or liable for any loss or damage incurred by you or any third party arising out of, or in connection with, any use of the information on our website (other than with regards to any duty or liability that we are unable to limit or exclude by law or under the applicable regulatory system) and any such liability is hereby expressly disclaimed.