


NZD/USD forecast: Jobs report weakens case for aggressive RBNZ hikes
Stronger employment wasn't enough to offset a surge in labour force participation, leaving unemployment at its highest level in more than a decade. The report keeps a September RBNZ hike in play but casts doubt on the rate path beyond.
Share this:

- Unemployment hits highest level since June 2015
- Underutilisation jumps despite stronger-than-expected hiring\
- Kiwi swaps retreat as rate bets unwind
- AUD/NZD rebounds after support holds
Labour market slack builds
New Zealand's unemployment rate climbed to its highest level in over a decade in the June quarter, reinforcing the view that abundant labour market slack leaves little risk of a wage breakout that could reignite domestic inflationary pressures.
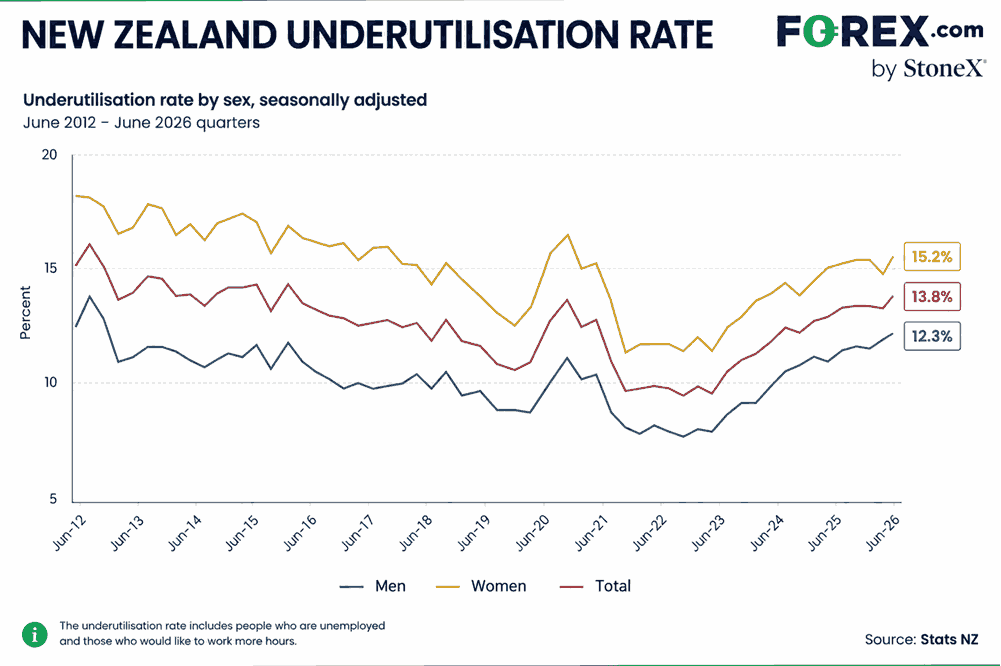
The unemployment rate climbed to 5.6% in the June quarter, the highest level since the June quarter of 2015, comfortably above the 5.4% expected by both markets and RBNZ. Broader measures softened too, with the underutilisation rate climbing to 13.8% from 12.9%. This measure includes unemployed, people wanting more hours and those on the sidelines available for work, making it a broader gauge of spare capacity in the labour market.
Source: StatsNZ, FOREX.com
This content was created by an affiliate of FOREX.com and represents the views and opinions of the author/speakers, not the views and opinions of FOREX.com, StoneX Group Inc., or its subsidiaries. The content has not been independently reviewed by FOREX.com.
Despite the increase in slack, the report masked what was a strong quarter for hiring. Employment increased 0.5%, more than double the 0.2% gain expected by markets and well above the 0.1% increase forecast by the RBNZ. Over the year, it grew by 1.2%.
The reason unemployment increased was a sharp lift in labour force participation, with the rate jumping to 70.7%, well above the 70.3% expected by both markets and the RBNZ. More people entered the workforce than the economy was able to absorb, leaving unemployment and underutilisation higher.
Wage growth wasn't a game changer either. While private sector labour cost inflation edged above the RBNZ's forecast at 2.0% year-on-year, it remains at levels inconsistent with the type of wage breakout that could fuel domestic inflationary pressures.
Markets may have overcooked the RBNZ
Despite the softness of the report, it is unlikely to derail the near-term RBNZ outlook with another 25 basis point rate increase still highly likely at next month's meeting, fitting with the hawkish bias delivered in July when policymakers began the tightening cycle.
At the conclusion of that meeting, the RBNZ said "with inflation still above target and economic activity expected to strengthen, some further reduction in monetary stimulus is likely to be required to return inflation to the 2 percent target mid-point", while adding that future cash rate decisions would depend on incoming data, price-setting behaviour and the strength of economic activity.
Beyond next month's meeting, today's data does raise fresh questions over how far rates will ultimately need to move beyond neutral, estimated by the RBNZ to be around 3%.
Source: LSEG, FOREX.com
This content was created by an affiliate of FOREX.com and represents the views and opinions of the author/speakers, not the views and opinions of FOREX.com, StoneX Group Inc., or its subsidiaries. The content has not been independently reviewed by FOREX.com.
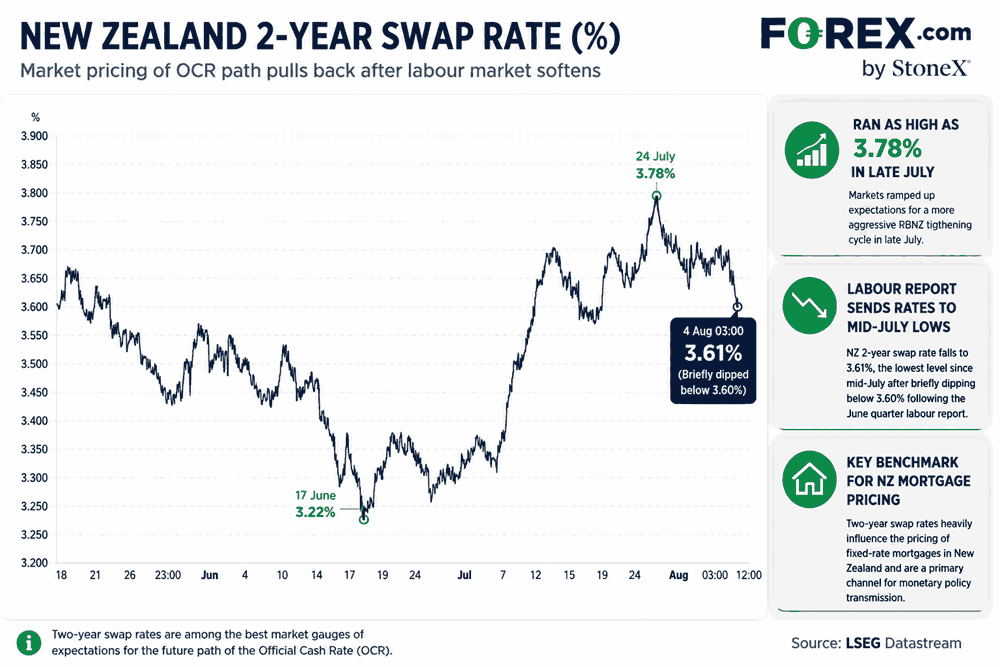
That was reflected in New Zealand's two-year swap rate, a key market gauge of expectations for the future path of the cash rate. The rate fell to 3.61% following the release, the lowest level since mid-July after briefly dipping beneath 3.60%. That's a notable reversal given it traded as high as 3.78% in late July as markets ramped up expectations for a more aggressive tightening cycle.
The move matters because two-year swap rates heavily influence the pricing of fixed-rate mortgages in New Zealand, making them one of the primary channels through which changes in RBNZ policy are transmitted to households and the broader economy.
Risk appetite calls the shots for NZD/USD
Source: TradingView
For NZD/USD, the domestic rates story is superseded by broader risk appetite as the primary directional driver, helping to explain why the Kiwi has only edged lower following the labour market report.
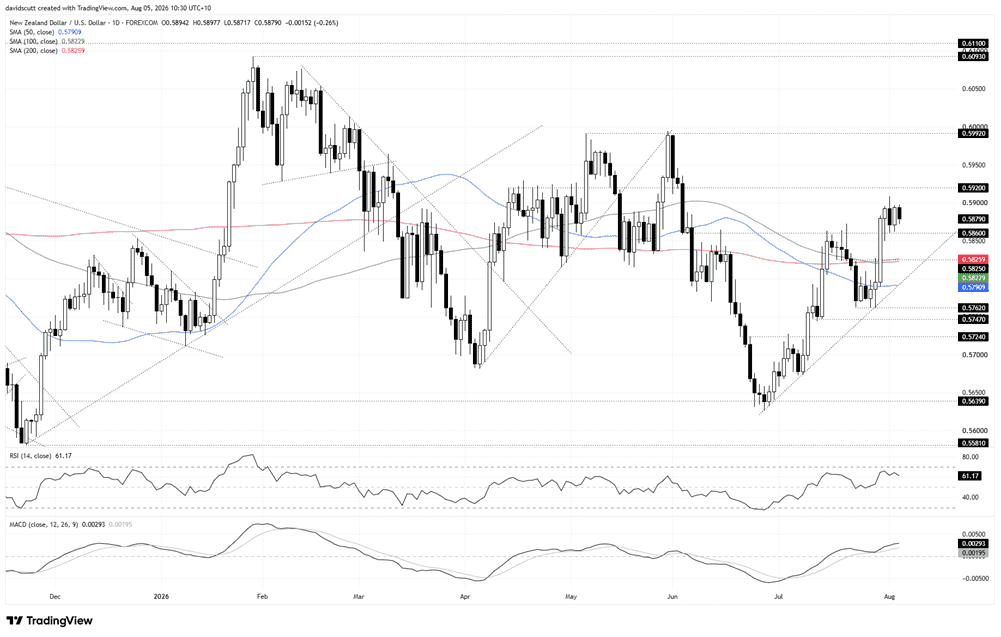
More importantly, the pullback has done little to threaten last week's break above resistance at 0.5860. Having bounced from around that level in each of the past two sessions, it remains the immediate level to watch on the downside. Below, the confluence of the 50 and 100-day moving averages, along with minor support at 0.5825, marks the next downside zone of note before the uptrend from the June lows comes into view.
On the topside, the pair stalled above 0.5900 on Monday, leaving that and more persistent resistance at 0.5920 as the immediate hurdles. A break above the latter would open the door for a retest of the 0.5992 double top established earlier this year.
Momentum indicators continue to favour buying dips over selling rallies. RSI (14) remains above the neutral 50 level despite losing some upside momentum in recent sessions, while MACD continues to hold above both its signal line and zero, maintaining the bullish bias established in early July.
AUD/NZD tries to turn the tide
Source: TradingView
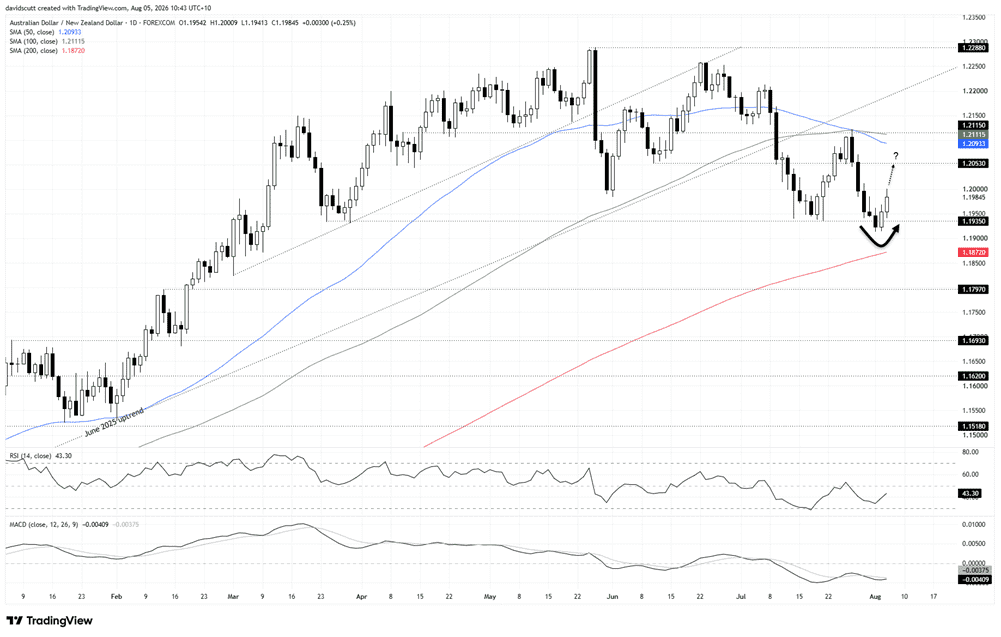
Where relative rate expectations matter far more is in the crosses, including AUD/NZD. Combined with stronger-than-expected Australian household spending data for June released on Tuesday, New Zealand's soft labour market report has helped the pair rebound after a failed attempt to break below support at 1.1935.
Having held on this occasion, AUD/NZD is now pushing back towards 1.2000. Above there, former support at 1.2053 is the next hurdle, followed by the confluence of the 50 and 100-day moving averages and horizontal resistance at 1.2115.
Should the broader downtrend reassert itself, the recent lows beneath 1.1935 and the nearby 200-day moving average remain the immediate downside focus.
Momentum indicators have become less bearish in recent sessions. RSI (14) has turned higher from oversold territory and is pushing back towards the neutral 50 level, while MACD has started to curl back towards its signal line while remaining in negative territory. It suggests downside momentum is fading, leaving the near-term directional outlook looking far more balanced than it did only a few days ago.


Open an account today
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Nasdaq 100, SOX: Tech rout may be a symptom of something far larger
The financial tide is going out, and some of the market's biggest winners are being hammered. Our research suggests there's more to the tech rout than the AI headlines.

USD/JPY Outlook: Yen Strength Builds as Carry Trades Come Under Threat
Rising equity volatility threatens yen carry trades as USD/JPY struggles at 160 resistance and AUD/JPY leads a broader recovery in the Japanese yen.


Gold and Silver's Deepening Dollar Dilemma
The dollar has broken higher, gold and silver have been crushed, and US financial conditions are tightening rapidly. Our historical analysis suggests this is no ordinary precious metals selloff.
From time to time, StoneX Financial Pty Ltd (“we”, “our”) website may contain links to other sites and/or resources provided by third parties. These links and/or resources are provided for your information only and we have no control over the contents of those materials, and in no way endorse their content. Any analysis, opinion, commentary or research-based material on our website is for information and educational purposes only and is not, in any circumstances, intended to be an offer, recommendation or solicitation to buy or sell. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. No representation or warranty is made, express or implied, that the materials on our website are complete or accurate. We are not under any obligation to update any such material.
As such, we (and/or our associated companies) will not be responsible or liable for any loss or damage incurred by you or any third party arising out of, or in connection with, any use of the information on our website (other than with regards to any duty or liability that we are unable to limit or exclude by law or under the applicable regulatory system) and any such liability is hereby expressly disclaimed.