



Q2 Australian CPI preview and what comes next for the ASX200
Tucked in between this week's FOMC meeting, U.S Q2 GDP data, and earnings reports from U.S mega tech is the release of Australian Q2 inflation data
Share this:
Tucked in between this week's FOMC meeting, U.S Q2 GDP data, and earnings reports from U.S mega tech is the release of Australian Q2 inflation data.
Following a 2.1% rise in Q1, headline CPI is expected to rise by 1.8% in Q2, which would take the annual rate of inflation to 6.2%, its highest level since 2001 on the back of price rises in petrol, electricity, gas, food and new home construction costs.
Core inflation or the "trimmed mean" is expected to rise by 1.5%, taking the annual rate to 4.7%.
A firmer AU Q2 CPI number on Wednesday, followed by a hawkish Fed on Thursday morning, would raise the chances that the RBA opts for a larger rate hike of 65 or 75bp when the Board meets next Tuesday.
More so, as RBA communique last week brought a new hawkish element to the table, noting that "the current level of the cash rate is well below" the estimated neutral rate, thought to be "at least" 2.5%.
Currently, the interest rate market is 77% priced for a 65bp interest rate hike at next week's RBA Board meeting, which would take the cash rate to 2%. The interest rate market then expects another 140bp of rate hikes in 2022, taking the cash rate to 3.4% by year-end.
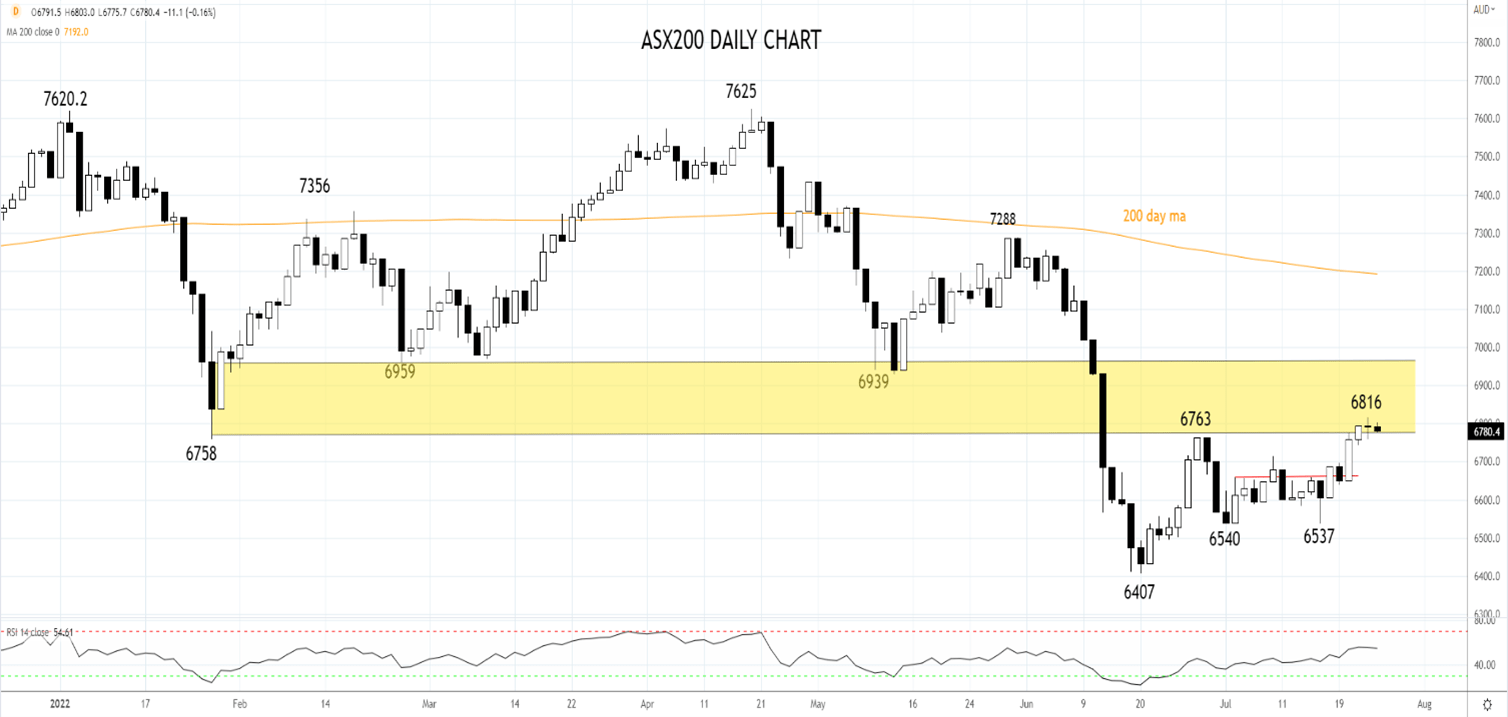
Turning to the ASX200, last week it gained 2.81%, for its best week since March, supported by a rebound on Wall Street and gains in tech and financial stocks.
The ASX200 is chipping away at the band of resistance 6750/6950. To negate the technical damage caused by the breakdown in June, a sustained break above 6950 is required.
Until this occurs, the rally from the 6407 low is viewed as a bear market countertrend rally.
Source Tradingview. The figures stated are as of July 25th ,2022. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Tucked in between this week's FOMC meeting, U.S Q2 GDP data, and earnings reports from U.S mega tech is the release of Australian Q2 inflation data.
Following a 2.1% rise in Q1, headline CPI is expected to rise by 1.8% in Q2, which would take the annual rate of inflation to 6.2%, its highest level since 2001 on the back of price rises in petrol, electricity, gas, food and new home construction costs.
Core inflation or the "trimmed mean" is expected to rise by 1.5%, taking the annual rate to 4.7%.
A firmer AU Q2 CPI number on Wednesday, followed by a hawkish Fed on Thursday morning, would raise the chances that the RBA opts for a larger rate hike of 65 or 75bp when the Board meets next Tuesday.
More so, as RBA communique last week brought a new hawkish element to the table, noting that "the current level of the cash rate is well below "the estimated neutral rate, thought to be "at least" 2.5%.
Currently, the interest rate market is 77% priced for a 65bp interest rate hike at next week's RBA Board meeting, which would take the cash rate to 2%. The interest rate market then expects another 140bp of rate hikes in 2022, taking the cash rate to 3.4% by year-end.
Turning to the ASX200, last week it gained 2.81%, for its best week since March, supported by a rebound on Wall Street and gains in tech and financial stocks.
The ASX200 is chipping away at the band of resistance 6750/6950. To negate the technical damage caused by the breakdown in June, a sustained break above 6950 is required.
Until this occurs, the rally from the 6407 low is viewed as a bear market countertrend rally.
Source Tradingview. The figures stated are as of July 25th ,2022. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
- Open a Forex.com account, or log in if you’re already a customer.
- Search for the pair you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels.
- Place the trade.



Open an account today
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

ASX 200 On Track for Worst Week in Four Years, Raising Bear Market Fears
The ASX 200 faces its worst week in four years as falling commodities, China's economic weakness and broad-based selling threaten a deeper correction.
US CPI Preview: Will Inflation Fall Enough to Put a Fed Hike in Doubt?
A CPI reading that comes in above, or even at, consensus expectations this month would keep the FOMC on track to hike, so only a notable downside surprise would be likely to drive significant market volatility - what does that mean for the US Dollar?

Brazil Elections: Is Investor Confidence Beginning to Fade?
One of the most relevant events for emerging markets in recent sessions has been the outcome of Brazil’s presidential election. Following Lula da Silva’s victory in the second round, investor sentiment began to deteriorate noticeably. This can be observed in both the iShares MSCI Brazil ETF and the VanEck Brazil Small-Cap ETF, two important benchmarks for tracking the Brazilian equity market, both of which have posted declines of more than 15% at the start of the week.

From time to time, StoneX Financial Pty Ltd (“we”, “our”) website may contain links to other sites and/or resources provided by third parties. These links and/or resources are provided for your information only and we have no control over the contents of those materials, and in no way endorse their content. Any analysis, opinion, commentary or research-based material on our website is for information and educational purposes only and is not, in any circumstances, intended to be an offer, recommendation or solicitation to buy or sell. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. No representation or warranty is made, express or implied, that the materials on our website are complete or accurate. We are not under any obligation to update any such material.
As such, we (and/or our associated companies) will not be responsible or liable for any loss or damage incurred by you or any third party arising out of, or in connection with, any use of the information on our website (other than with regards to any duty or liability that we are unable to limit or exclude by law or under the applicable regulatory system) and any such liability is hereby expressly disclaimed.