

US futures
Dow futures 0.13%, S&P futures 0.6% & Nasdaq futures 1.4%
In Europe
FTSE 0.03% & DAX 0.51%
- Stocks are rising after losses last week
- US economic data ramps up this week
- Fed Waller’s dovish comments lift Fed rate cut expectations
- Oil steadies after falling 3% last week
US stocks rise after losses last week
US stocks are set to open higher on Monday, as the market kicks off the holiday-shortened Thanksgiving week, with thin volumes expected.
Stocks are extending gains from Friday as traders increased bets of a Federal Reserve rate cut next month following dovish comments from New York Fed president John Williams.
According to the CME Fed watch, the odds of a 25 basis point reduction in December currently stand at 65%, up from 25% on Thursday. The dominant theme is without doubt Fed rate cut expectations, and the market could remain choppy until the December 10 meeting.
This week sees the release of U.S. economic data, including retail sales, durable goods orders, and PPI figures, as the economic calendar starts to return to normal after a record-long shutdown.
These figures come ahead of the Thanksgiving holiday on Thursday, extending into Black Friday and Cyber Monday. Consumer patterns will be very much in focus given the importance of consumption in the US economy, particularly as inflation remains sticky and concerns over job layoffs linger.
According to the National Retail Federation, US holiday sales are expected to surpass $1 trillion for the first time. US retail stocks will be in focus.
Worries over AI valuations appear to be easing this week, after tech stocks fell sharply last week despite Nvidia’s impressive results.
All three leading indices are heading for a monthly loss in November, with the S&P 500 and the NASDAQ set for their steepest decline since March.
However, it's not all bad news. Deutsche Bank lifted some of the gloom by forecasting the S&P 500 would surge to 8000 by the end of next year, fighting resilient corporate earnings and AI gains. This has been the most British cool among global brokerages.
Corporate news
Tesla is rising pre-market after CEO Elon Musk said on X that the company is close to finalising its latest AI chip, A-15, and has started work on the A16 chip. Tesla is going to bring a new AI chip design to volume production every 12 months.
Alphabet is gaining 3.5% and was the only Magnificent Seven stock to post gains last week. Alphabet launched its latest AI model, Gemini 3, last week.
Alibaba's US-listed shares of the Chinese e-commerce company rose 4% after it announced that its AI app Qwen had 10 million downloads in its first week.
Novo Nordisk is dropping over 10% after the Danish pharmaceutical firm's trial for Alzheimer's failed to meet its primary goals of slowing the disease's progression.
S&P500 forecast – technical analysis.
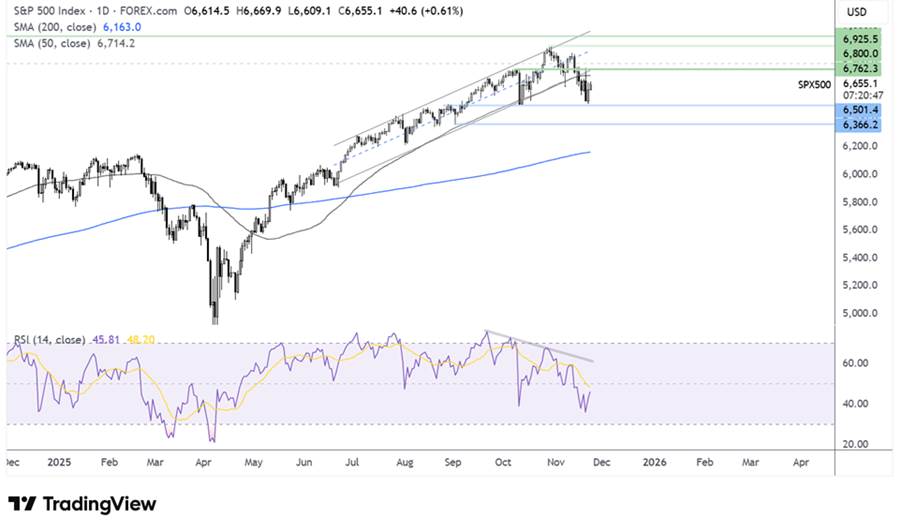
The S&P 500 found support at 6500 last week and rebounded higher. However, the price continues to trade below its multi-month rising channel and below its 50 SMA. Buyers will need to extend the recovery above 6715, the 50 SMA, and 6760, the October 7 high, to negate the near-term selloff and head towards 6925 and fresh record highs. Sellers will need to fall below 6500 to create a lower low towards 6360, the September low.
FX markets – USD rises, GBP/USD falls
The U.S. dollar is edging lower after hitting a six-month high last week. The dollar is under pressure after comments from the New York Fed president last week raised December rate expectations above 70%.
USD/JPY remains close to a 10-month high, though traders stay on alert for a risk of Japanese authorities intervening to prop up the yen. The yen has fallen by over 1.8% so far in November amid growing concerns over the nation's fiscal health and low interest rates.
EUR/USD is rising amid a weaker USD, although German business sentiment data limits gains. German Ifo business sentiment unexpectedly falls in November, as companies lose hope for a recovery in the German economy. Ifo business climate fell to 88.1 in November, down from 88.4 in October. This was below forecasts of 88.5.
GBP/USD is holding steady on Monday amid a cautious mood ahead of Britain's budget announcement this week. The bond market, especially, will be watching to see whether Rachel Reeves's fiscal plan is credible. The pound could also come under pressure if Reeves announces measures to ease inflationary pressures. This could pave the way for another BoE rate cut in December.
Oil steadies after dropping 3% last week
After falling 3.5% last week, oil prices are stabilising as investors weighed up the chance of a US rate cut against the prospect of a Ukraine-Russia peace deal, which could lead to reduced sanctions on major producer Russia.
President Trump's Thursday deadline for a peace plan, which, if agreed to by Ukraine and Russia, could see sanctions on Russia lowered to increase oil supply to the market. However, there are some questions over whether Thursday's deadline is set in stone.
Uncertainties regarding US interest rate cuts have been another factor weighing on investors' appetite. Rate-cut expectations for next month jumped after New York Fed Reserve President John Williams suggested a cut in the near term.
Oil prices are down around 17% this year, reflecting persistent negative sentiment amid expectations of increased supply, and we could demand




