usdcny the currency pair that sparked a global meltdown 2101962015
USDCNY is the currency pairing that sparked a global flight from risky assets when the People’s Bank of China (PBoC) unexpectedly devalued the yuan against […]

USDCNY is the currency pairing that sparked a global flight from risky assets when the People’s Bank of China (PBoC) unexpectedly devalued the yuan against […]

USDCNY is the currency pairing that sparked a global flight from risky assets when the People’s Bank of China (PBoC) unexpectedly devalued the yuan against the US dollar by the largest amount in one day for over two decades. The PBoC widened USDCNY’s reference rate by 1.9% in mid-August in response to sustained upward pressure on the US dollar and threats to growth stemming from a weak exports sector in China. Since then USDCNY has retraced some of these gains after a brief stint above 6.4.
USD is still king
Looking at the US dollar side of the equation, upward pressure on the world’s reserve currency has been easing lately as traders have discounted the possibility of tighter interest rates in the US this month. Turmoil in markets across the globe, fears of global deflation and a lack of inflation at home have cast doubt over the need for tighter monetary policy at this stage. It may be a mistake for the world’s first modern central bank to tighten the purse strings amidst such a toxic environment. This is making US dollar bulls nervous, even enough to stem some safe haven flows into the US dollar that would normally occur in this kind of risk-adverse marketplace.
However, the US dollar is still king, as the Fed is still poised to be the first major central bank, with the exception of a short hawkish run from the Reserve Bank of New Zealand, to raise interest rates in a long time. The US dollar has been in the midst of a war between long-term bulls and short-term positioning, although recent strong US employment figures have reenergised short-term USD bulls. Overall, the medium/long-term implications for USDCNY should be positive, especially given China’s slowing economy and the accompanied monetary policy easing.
China needs a lower exchange rate
China’s economy needs support, at least according to a string of weak economic numbers. A strong exchange rate is a major hindrance for growth in China’s still important export sector, which is also struggling under the weight of soft global domestic demand and increased competition. A further depreciation of the renminbi could help ease some pressure and support overall economic activity that is also being weighed down by a lack of domestic demand.
So, why doesn’t the PBoC weaken CNY further?
However, the PBoC is reluctant to weaken the yuan further as it may increase capital outflows. Capital has been flowing out of China lately, partly due to the belief that the yuan has been overvalued, which is severely limiting the ability of the PBoC to spur economic activity through increased liquidity.
What does the market think?
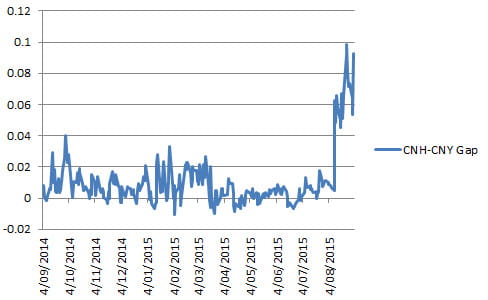
Downward pressure on CNY (onshore yuan) has greatly reduced since the PBoC’s decision to move USDCNY’s reference rate significantly higher, as evidenced by how close to its midpoint USDCNY is trading post-devaluation (see figure 1). However, there appears to be more downward pressure in offshore yuan (see figure 2) as the gap between offshore and onshore yuan widens. This could see upward pressure build in USDCNY in the medium-term, especially if the market thinks the PBoC may weaken the yuan once more, which is may do given the futility of attempting to prevent capital outflows right now and the need to support its export sector.
Figure 1: USDCNY vs. its reference rate

Source: City Index, Bloomberg
Figure 2: offshore/onshore gap
Source: City Index, Bloomberg