



A peek at (peak?) inflation
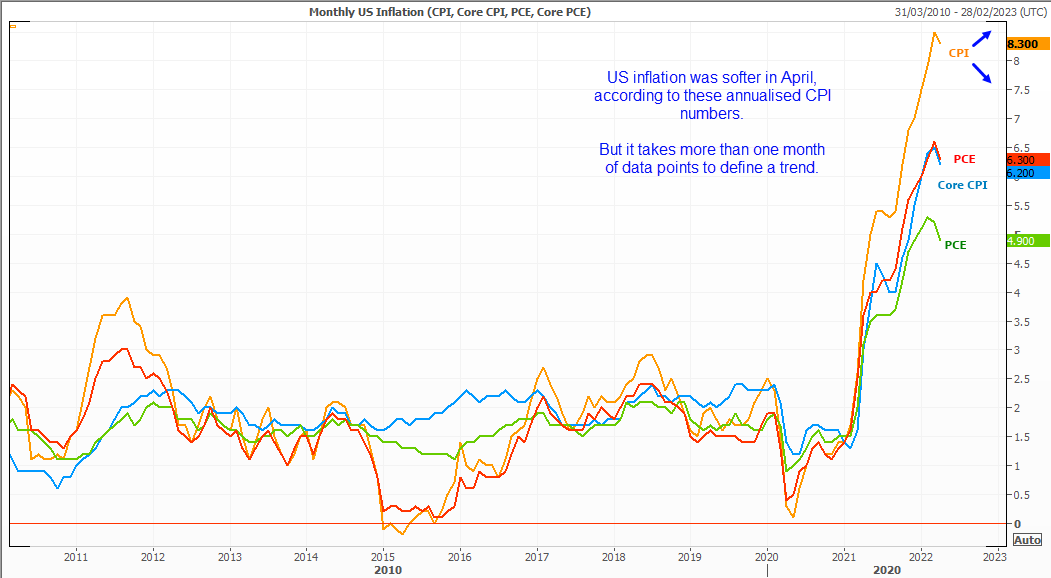
US Inflation may have softened to a degree in April, but traders really want to see further evidence that inflation is pointing lower to call ‘peak inflation’ with more confidence.
Share this:

We knew going into last month’s inflation report that it was likely to be followed by a slew of ‘peak inflation’ headlines. CPI was forecast to soften from multi-decade highs and, when it did, the headlines did not disappoint.
Annualised prints of CPI, core CPI, PCE and core PCE all softened in April, and that’s an important first step to identifying a peak. But a month’s worth of data points don’t define a trend. Therefore, Friday’s inflation report is really about convincing us that the worst of eye-watering levels of inflation really are behind us. We simply need to see is soften again. And if we look through some inflation inputs, it’s beginning to look promising that it is.
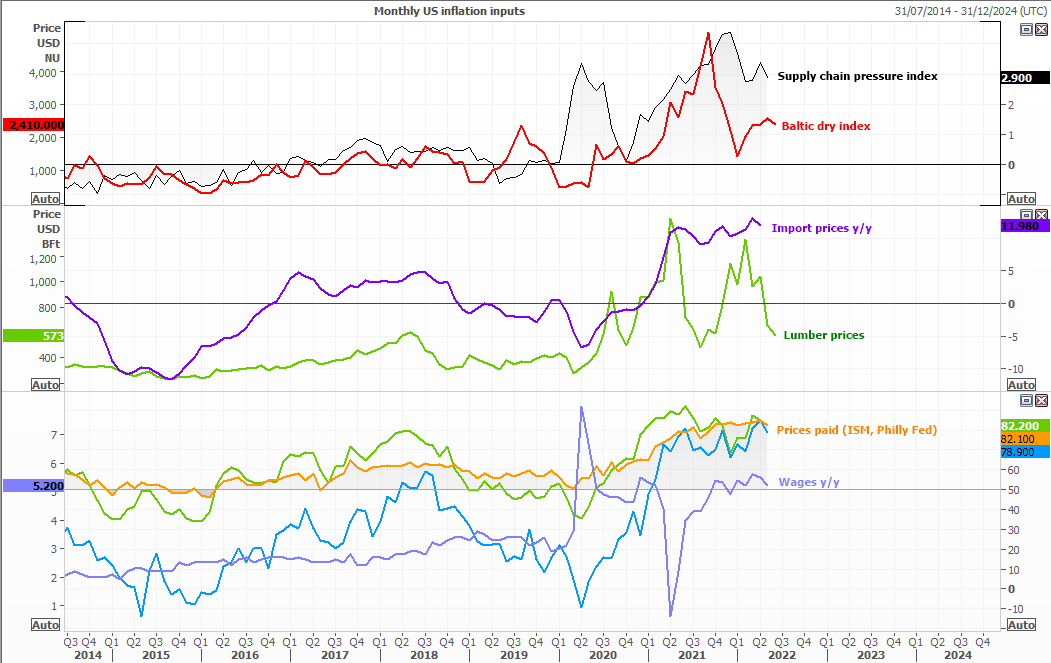
Some inflationary inputs are pointing lower
‘Prices paid’ by services and manufacturing companies also fell in April according to the ISM and Philly Fed reports. Import prices (effectively imported inflation) and wages also fell on an annualised basis, whilst lumber prices have plummeted from this year’s high. There are also signs that bottlenecks are easing with the supply chain pressure index falling lower in March, and sitting quite a bit beneath its December peak. The Baltic dry index – the cost of sea freight – has also turned lower. And earlier this week US retailer Target (TGT) warned they will have to slash prices due to a large build-up of inventory (low demand).
When things get too hot, they also get ‘sticky’
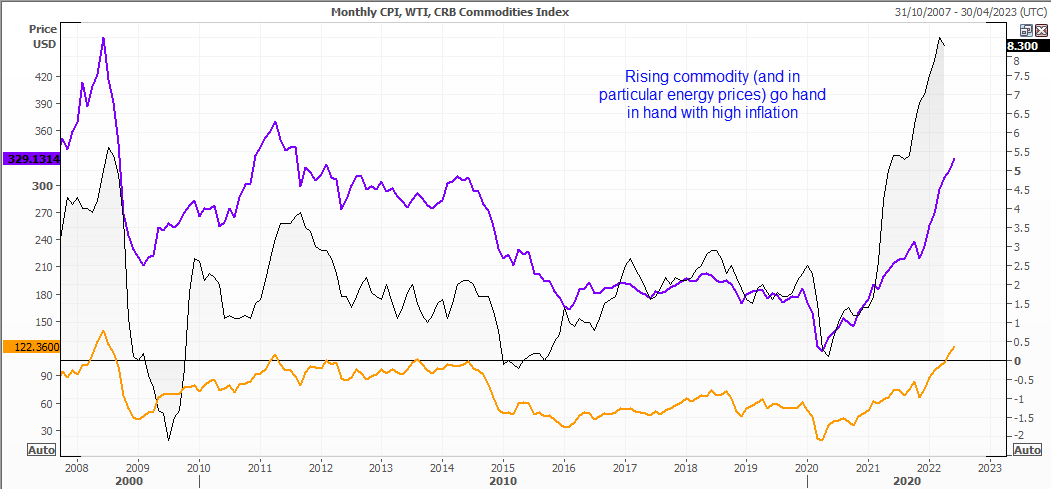
As nice as that is to see, it doesn’t escape the fact that commodities (and energy in particular) are soaring. High energy prices make an impact globally for consumers and businesses, whether it be manufacturing, transportation or simply heating your home. Oil prices continue to rise with US driving season underway and China’s reopening supporting its trend. Oil therefore remains a major inflationary input for policy makers to mull over. Earlier this week, US Secretary of the Treasury Janet Yellen said inflation is at “unacceptable levels” and likely to remain high. We suspect most agree. Going forward it is not so much the absolute level of inflation that matters so much as its direction and rate of change.
Ultimately the fear going forward is that inflation has become so hot that it will become ‘sticky’ at higher levels. The longer prices remain high the more of a drag it becomes on consumption, consumer and business sentiment and therefore growth.
So let’s face the fact that central banks are behind the curve and there was no need for inflation to get to such levels. It surely would have been better to feel short-term pain (higher rates, sooner) for long-term gain (lower rates than we’re now likely to have going forward). The cost of delaying these hikes is likely to put a further strain on consumer sentiment and housing sector, of which cracks are already appearing.
Economists are expecting inflation to fall in May 2022
- Core CPI is forecast to fall to 0.5% m/m in May, down from 0.6% in April.
- Annual core CPI is forecast to fall to 5.9% from 6.2% y/y.
- CPI (which includes food and energy) is expected to rise to 0.7% m/m from 0.3%.
- Annual CPI is expected to remain flat at the giddy height of 8.3%.
With CPI expected to rise to 0.7% m/m (from 0.3%), anything less is a bonus. Clearly the nest outcome for peak inflation is 0.2% or low, whilst 0.3% would still be seen as a victory. But with energy prices soaring this seems unlikely. Core CPI is expected to fall to 0.5% (from 0.6%), so 0.5% or lower for core CPI is a result for the ‘peak inflation’ crowd.
How might markets react around the US inflation report?
Wall Street’s major indices have been confined within a range for the past 8-days, and it seems clear that the US inflation report is a likely catalyst to make it break out of that range – one way or another. A softer data set could help equity traders rejoice and break indices out of their ranges, and with some volatility for decent measure.
A softer inflation report could also weigh on the dollar for the same reasons equities rally; softer inflation removes some pressure for the Fed to act so aggressively with higher interest rates. We’ve already heard murmurs of the Fed potentially pausing rates around September after a series of 50-bps hikes. And a soft inflation print would certainly help with that case.
Of course, should inflation unexpectedly rise then it could wreak havoc across markets. Equities could embark upon their next leg lower, and the US dollar catch a fresh bid as the case for aggressive hike to continue from the Fed retake centre stage.
How to trade with City Index
You can easily trade with City Index by using these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
How to trade with FOREX.com
Follow these easy steps to start trading with FOREX.com today:
- Open a Forex.com account, or log in if you’re already a customer.
- Search for the pair you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels.
- Place the trade.




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
FOMC Meeting Preview: Three Questions for Chairman Warsh
Assuming the Fed delivers the expected hike, traders will want to know WHAT could prompt another hike, WHY they hiked this time, and HOW to interpret the dot plot.

Crude Oil Price Outlook: WTI and Brent Lead the Market Narrative
Crude Oil Price Outlook: Crude oil remains the market’s dominant narrative despite conflicting headline signals


Dow Jones Breaks Support as Oil and Yields Hit Stocks
Dow Jones weakness links rising crude oil and Treasury yields with pressure on stocks, while a rebound leaves the broken uptrend unconfirmed.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.