



Asia Morning June 17
On Tuesday, U.S. stocks advanced further, as investors were encouraged by upbeat retail sales readings and a news report of a potential one-trillion-dollar infrastructure plan by the government...
Share this:

On Tuesday, U.S. stocks advanced further, as investors were encouraged by upbeat retail sales readings and a news report of a potential one-trillion-dollar infrastructure plan by the government. Meanwhile, Federal Reserve Chairman Jerome Powell told the Senate Banking Committee: "Until the public is confident that the disease is contained, a full recovery is unlikely."
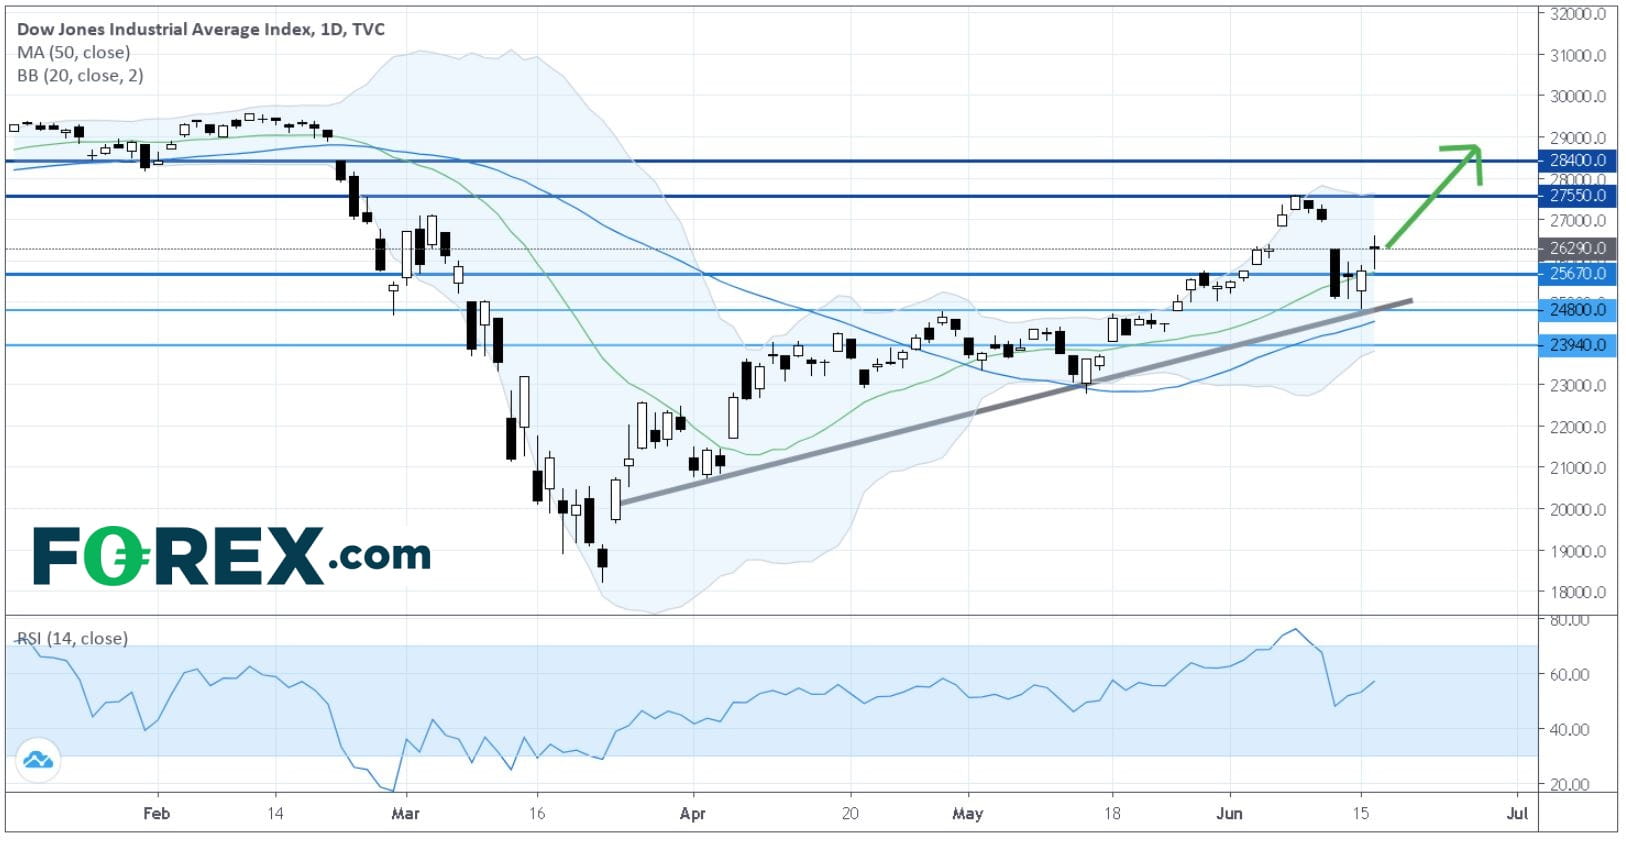
The Dow Jones Industrial Average jumped 526 points (+2.0%) to 26290, the S&P 500 increased 58 points (+1.9%) to 3124, and the Nasdaq 100 was up 172 points (+1.8%) to 9949.

Pharmaceuticals, Biotechnology & Life Sciences (+3.02%), Energy (+2.82%) and Technology Hardware & Equipment (+2.63%) sectors were market leaders. Eli Lilly (LLY +15.68%), Nordstrom Inc (JWN +12.91%), Kohls Corp (KSS +8.96%), Vulcan Materials (VMC +8.76%) and Gap (GPS +8.48%) were top gainers.
On the technical side, about 41.3% (39.3% in the prior session) of stocks in the S&P 500 Index were trading above their 200-day moving average, and 53.8% (46.2% in the prior session) were trading above their 20-day moving average.
U.S. official data showed that Retail Sales surged 17.7% on month in May (+8.4% expected), the biggest increase on record. Industrial Production rose 1.4% on month in May (+3.0% expected).
Due later today will be Housing Starts for May (an increase to an annualized rate of 1.100 million units expected).
European stocks recorded beefy gains, with the Stoxx Europe 600 Index advancing 2.9%. Germany's DAX surged 3.4%, France's CAC rose 2.8%, and the U.K.'s FTSE 100 jumped 2.9%.
U.S. government bond prices remained under pressure, as the benchmark 10-year U.S. Treasury yield settled higher at 0.754%.
Spot gold was little changed at $1,725 an ounce.
Oil prices rose for a second session, as economic recovery expectations were boosted by better-than-expected U.S. retail sales data. U.S. WTI crude oil futures (July) climbed 3.4% to $38.38 a barrel.
On the forex front, the ICE U.S. Dollar Index rose 0.5% on day to 97.03, lifted by a record gain in U.S. retail sales.
EUR/USD slid 0.6% to 1.1260. German ZEW Current Situation Index improved to -83.1 in June (-82.0 expected) from -93.5 in May and Expectations Index climbed to 63.4 (60.0 expected) from 51.0.
GBP/USD fell 0.3% to 1.2571. Official data showed that U.K. jobless rate was steady at 3.9% in the three months to April (4.7% expected). On the other hand, CPI data for May will be released later today (+0.5% on year expected).
USD/JPY was broadly flat at 107.38. The Bank of Japan kept its benchmark rate unchanged at -0.10% as expected, while expanding its special lending program to 110 trillion yen from 75 trillion yen. This morning, government data showed that Japan's exports decline 28.3% on year in May (-26.1% expected) and imports sank 26.2% (-20.4% expected),
The Dow Jones Industrial Average jumped 526 points (+2.0%) to 26290, the S&P 500 increased 58 points (+1.9%) to 3124, and the Nasdaq 100 was up 172 points (+1.8%) to 9949.
Dow Jones Industrial Average: Daily Chart
Source: GAIN Capital, TradingView
Pharmaceuticals, Biotechnology & Life Sciences (+3.02%), Energy (+2.82%) and Technology Hardware & Equipment (+2.63%) sectors were market leaders. Eli Lilly (LLY +15.68%), Nordstrom Inc (JWN +12.91%), Kohls Corp (KSS +8.96%), Vulcan Materials (VMC +8.76%) and Gap (GPS +8.48%) were top gainers.
On the technical side, about 41.3% (39.3% in the prior session) of stocks in the S&P 500 Index were trading above their 200-day moving average, and 53.8% (46.2% in the prior session) were trading above their 20-day moving average.
U.S. official data showed that Retail Sales surged 17.7% on month in May (+8.4% expected), the biggest increase on record. Industrial Production rose 1.4% on month in May (+3.0% expected).
Due later today will be Housing Starts for May (an increase to an annualized rate of 1.100 million units expected).
European stocks recorded beefy gains, with the Stoxx Europe 600 Index advancing 2.9%. Germany's DAX surged 3.4%, France's CAC rose 2.8%, and the U.K.'s FTSE 100 jumped 2.9%.
U.S. government bond prices remained under pressure, as the benchmark 10-year U.S. Treasury yield settled higher at 0.754%.
Spot gold was little changed at $1,725 an ounce.
Oil prices rose for a second session, as economic recovery expectations were boosted by better-than-expected U.S. retail sales data. U.S. WTI crude oil futures (July) climbed 3.4% to $38.38 a barrel.
On the forex front, the ICE U.S. Dollar Index rose 0.5% on day to 97.03, lifted by a record gain in U.S. retail sales.
EUR/USD slid 0.6% to 1.1260. German ZEW Current Situation Index improved to -83.1 in June (-82.0 expected) from -93.5 in May and Expectations Index climbed to 63.4 (60.0 expected) from 51.0.
GBP/USD fell 0.3% to 1.2571. Official data showed that U.K. jobless rate was steady at 3.9% in the three months to April (4.7% expected). On the other hand, CPI data for May will be released later today (+0.5% on year expected).
USD/JPY was broadly flat at 107.38. The Bank of Japan kept its benchmark rate unchanged at -0.10% as expected, while expanding its special lending program to 110 trillion yen from 75 trillion yen. This morning, government data showed that Japan's exports decline 28.3% on year in May (-26.1% expected) and imports sank 26.2% (-20.4% expected),
On Tuesday, U.S. stocks advanced further, as investors were encouraged by upbeat retail sales readings and a news report of a potential one-trillion-dollar infrastructure plan by the government. Meanwhile, Federal Reserve Chairman Jerome Powell told the Senate Banking Committee: "Until the public is confident that the disease is contained, a full recovery is unlikely."
The Dow Jones Industrial Average jumped 526 points (+2.0%) to 26290, the S&P 500 increased 58 points (+1.9%) to 3124, and the Nasdaq 100 was up 172 points (+1.8%) to 9949.
Pharmaceuticals, Biotechnology & Life Sciences (+3.02%), Energy (+2.82%) and Technology Hardware & Equipment (+2.63%) sectors were market leaders. Eli Lilly (LLY +15.68%), Nordstrom Inc (JWN +12.91%), Kohls Corp (KSS +8.96%), Vulcan Materials (VMC +8.76%) and Gap (GPS +8.48%) were top gainers.
On the technical side, about 41.3% (39.3% in the prior session) of stocks in the S&P 500 Index were trading above their 200-day moving average, and 53.8% (46.2% in the prior session) were trading above their 20-day moving average.
U.S. official data showed that Retail Sales surged 17.7% on month in May (+8.4% expected), the biggest increase on record. Industrial Production rose 1.4% on month in May (+3.0% expected).
Due later today will be Housing Starts for May (an increase to an annualized rate of 1.100 million units expected).
European stocks recorded beefy gains, with the Stoxx Europe 600 Index advancing 2.9%. Germany's DAX surged 3.4%, France's CAC rose 2.8%, and the U.K.'s FTSE 100 jumped 2.9%.
U.S. government bond prices remained under pressure, as the benchmark 10-year U.S. Treasury yield settled higher at 0.754%.
Spot gold was little changed at $1,725 an ounce.
Oil prices rose for a second session, as economic recovery expectations were boosted by better-than-expected U.S. retail sales data. U.S. WTI crude oil futures (July) climbed 3.4% to $38.38 a barrel.
On the forex front, the ICE U.S. Dollar Index rose 0.5% on day to 97.03, lifted by a record gain in U.S. retail sales.
EUR/USD slid 0.6% to 1.1260. German ZEW Current Situation Index improved to -83.1 in June (-82.0 expected) from -93.5 in May and Expectations Index climbed to 63.4 (60.0 expected) from 51.0.
GBP/USD fell 0.3% to 1.2571. Official data showed that U.K. jobless rate was steady at 3.9% in the three months to April (4.7% expected). On the other hand, CPI data for May will be released later today (+0.5% on year expected).
USD/JPY was broadly flat at 107.38. The Bank of Japan kept its benchmark rate unchanged at -0.10% as expected, while expanding its special lending program to 110 trillion yen from 75 trillion yen. This morning, government data showed that Japan's exports decline 28.3% on year in May (-26.1% expected) and imports sank 26.2% (-20.4% expected),
The Dow Jones Industrial Average jumped 526 points (+2.0%) to 26290, the S&P 500 increased 58 points (+1.9%) to 3124, and the Nasdaq 100 was up 172 points (+1.8%) to 9949.
Dow Jones Industrial Average: Daily Chart
Source: GAIN Capital, TradingView
Pharmaceuticals, Biotechnology & Life Sciences (+3.02%), Energy (+2.82%) and Technology Hardware & Equipment (+2.63%) sectors were market leaders. Eli Lilly (LLY +15.68%), Nordstrom Inc (JWN +12.91%), Kohls Corp (KSS +8.96%), Vulcan Materials (VMC +8.76%) and Gap (GPS +8.48%) were top gainers.
On the technical side, about 41.3% (39.3% in the prior session) of stocks in the S&P 500 Index were trading above their 200-day moving average, and 53.8% (46.2% in the prior session) were trading above their 20-day moving average.
U.S. official data showed that Retail Sales surged 17.7% on month in May (+8.4% expected), the biggest increase on record. Industrial Production rose 1.4% on month in May (+3.0% expected).
Due later today will be Housing Starts for May (an increase to an annualized rate of 1.100 million units expected).
European stocks recorded beefy gains, with the Stoxx Europe 600 Index advancing 2.9%. Germany's DAX surged 3.4%, France's CAC rose 2.8%, and the U.K.'s FTSE 100 jumped 2.9%.
U.S. government bond prices remained under pressure, as the benchmark 10-year U.S. Treasury yield settled higher at 0.754%.
Spot gold was little changed at $1,725 an ounce.
Oil prices rose for a second session, as economic recovery expectations were boosted by better-than-expected U.S. retail sales data. U.S. WTI crude oil futures (July) climbed 3.4% to $38.38 a barrel.
On the forex front, the ICE U.S. Dollar Index rose 0.5% on day to 97.03, lifted by a record gain in U.S. retail sales.
EUR/USD slid 0.6% to 1.1260. German ZEW Current Situation Index improved to -83.1 in June (-82.0 expected) from -93.5 in May and Expectations Index climbed to 63.4 (60.0 expected) from 51.0.
GBP/USD fell 0.3% to 1.2571. Official data showed that U.K. jobless rate was steady at 3.9% in the three months to April (4.7% expected). On the other hand, CPI data for May will be released later today (+0.5% on year expected).
USD/JPY was broadly flat at 107.38. The Bank of Japan kept its benchmark rate unchanged at -0.10% as expected, while expanding its special lending program to 110 trillion yen from 75 trillion yen. This morning, government data showed that Japan's exports decline 28.3% on year in May (-26.1% expected) and imports sank 26.2% (-20.4% expected),
Related tags:
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD into a Massive Week as Yields Fly and Gold Breaks
It’s a huge week with PCE and NFP, but it’s what’s happening off of the calendar that demands attention with US yields flying to fresh multi-decade highs.
USDJPY Forecast Intervention Fears Clash with Dollar Strength
Recent trading sessions have produced mixed results for the Japanese yen. By the end of last week, USD/JPY had fallen by more than 1.00%, reflecting a modest recovery in the yen. However, the start of this week has seen the pair move slightly back in favor of the U.S. dollar, posting gains of around 0.04%.

AUD/USD forecast: Currency Pair of the Week | September 28, 2026
The week has started with stocks, gold, silver and bitcoin all falling, as crude oil rebounded and bond yields pushed further higher. Trump refusing to agree to Tehran’s proposal to re-open the Strait of Hormuz has left the markets disappointed. Still, reports that mediators are expected to hold talks with the two sides on an amended version of the 7-day proposal that Iran presented, keeps hopes alive that we may see some progress.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.