



USDBRL should reflect fiscal fears in Brazil, FOMC minutes, and elections in Argentina
Bullish factors Uncertainty about the viability of budget targets in 2024 may increase risk premium requirements by investors for Brazilian assets and diminish foreign investments, weakening the real. Argentine elections can increase the perception of risks for other countries in the region and temporarily decrease managed money for Brazil, weakening the real. Bearish factors Disclosure of the minutes of the FOMC decision can reinforce the perception that American interest rates have already peaked and contributed to weakening the dollar.
Share this:

Bullish factors
- Uncertainty about the viability of budget targets in 2024 may increase risk premium requirements by investors for Brazilian assets and diminish foreign investments, weakening the real.
- Argentine elections can increase the perception of risks for other countries in the region and temporarily decrease managed money for Brazil, weakening the real.
Bearish factors
- Disclosure of the minutes of the FOMC decision can reinforce the perception that American interest rates have already peaked and contributed to weakening the dollar..
Our Brazil team provides regular weekly coverage of the Brazilian economy and the outlook for the Real, accessible by clicking the link in the banner above.
The week in review
The week was marked by the release of milder-than-expected data for the American economy, reinforcing the perception that the Federal Reserve will no longer raise the country's interest rates and promoting a global weakening of the American currency. The strengthening of the real was constrained by the prolongation of fiscal fears amid uncertainty about the possibility of changing the budget target for 2024.
The USDBRL ended the week lower, closing Friday's session (17) at BRL 4.906, a weekly decrease of 0.2%, a monthly decrease of 2.8%, and an annual decrease of 7.1%. The dollar index closed Friday's session at 103.8 points, a change of -1.8% for the week, -2.0% for the month, and +0.5% for the year.
USDBRL and Dollar Index (points)

Source: StoneX cmdtyView. Design: StoneX
HIGHLIGHTS: Fiscal target and LDO
Expected impact on USDBRL: bullish
This week's highlight should be the vote on the Budget Guidelines Law (LDO, in Portuguese) bill in the Joint Budget Committee (CMO, in Portuguese). After weeks of uncertainty and behind-the-scenes discussions about the possibility of changing the target fiscal goal for the 2024 Budget, the federal government has decided not to submit an amendment and to maintain the original objective of a zero primary deficit in the LDO. The rapporteur, Deputy Danilo Forte (União-CE), is expected to present the report for consideration on Monday (20) by the CMO and vote on it this week. Then, the LDO will go to the Plenary of the National Congress, which is expected to vote in the next two weeks, and then the Annual Budget Law (LOA) must be voted on, with the deadline for Plenary voting scheduled for the last week before the recess (December 18-22).
If, on the one hand, maintaining fiscal goals at this moment is a victory for the government's economic team and helps in defending the maintenance of the target, behind the scenes, according to reports from specialized media, it still seems certain that the change in the target will occur in the future, but through a bill, which will require a majority of deputies and senators, probably in March, when the first bimonthly report on revenues and expenses is presented. In this way, in addition to opting for a strategy that may require legislative mobilization, which has been a weak point of this government, it is not possible to recover the credibility of fiscal policy management, which may maintain higher perceptions of fiscal risks to Brazilian assets and increase the requirement of risk premiums by investors, weakening the real.
FOMC Minutes
Expected impact on USDBRL: bearish
This week, the release of the minutes from the last meeting of the Fed's Federal Open Market Committee (FOMC), which took place between October 31 and November 1, should also be highlighted. The decision of the Committee to keep the American basic interest rates stable and a speech considered more balanced indicated that the monetary tightening cycle of the institution may be nearing its end. This perception was reinforced by the release of economic data that were milder than expected for October, boosting a sharp appetite for risks among investors. In this way, the month of November is being marked, so far, by a significant global weakening of the American currency, a significant decline in yields of US Treasury bonds, and an appreciation of risky assets, such as paper, commodities, and currencies of countries that export primary products.
In a certain sense, the minutes will reflect an outdated situation since the discussions at the end of October were centered on concerns of "higher for longer" economic data for September warmer than experts' expectations and continued pressure from Treasury yields. On October 19, for example, yields on 10-year Treasuries had surpassed 5% p.a. for the first time since 2007, compared to 4.42% p.a. this Friday, November 17. Similarly, the speech of Federal Reserve authorities is still cautious and calls for patience, stating that the inflationary reduction so far is welcome but that any price reacceleration can provoke a new interest rate hike. Market agents want to explore the considerations about the interest rate trajectory, as there is almost consensus that a new hike is unlikely and that the Fed should keep rates unchanged for some time before starting a cycle of cuts.
For Brazil and the real, the boost in risk appetite meant a significant fall in the rating of Brazilian bonds, with the spread of Credit Default Swap (CDS) contracts reaching the lowest value since February 2021. Additionally, there was a higher demand for Brazilian assets, contributing to the strengthening of the real, which can be observed, for example, in the balance of foreign capital flow on the B3 during the month.
Spread of Brazil's 5-year Credit Default Swap (CDS) contracts (basis points)

Source: Bloomberg. Design: StoneX.
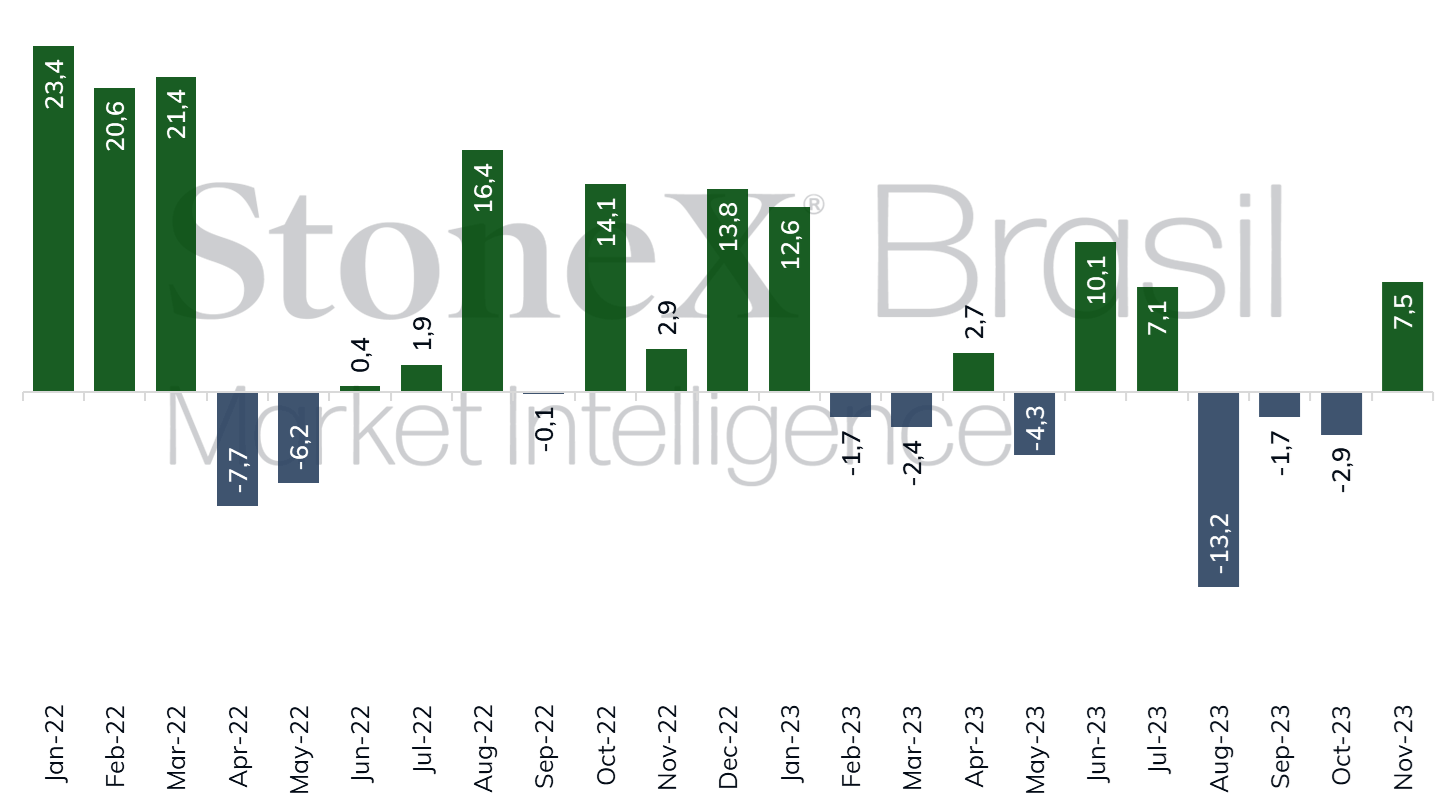
Foreign capital flow balance on the B3 as of November 14, 2023 (BRL/billion)
Argentina's elections
Expected impact on USDBRL: bullish
This Sunday (19), the second round of presidential elections in Argentina occurs between candidates Javier Milei and Sergio Massa. The voting intention surveys show a balanced race, usually with differences within the margins of error. Any elected candidate will face an economy with very difficult economic challenges, such as high inflation rates and a shortage of international reserves. Suppose the current Minister of Economy Massa represents the continuity of a government with many failures. In that case, the oppositionist and ultraconservative Milei accumulated controversial statements such as abandoning Mercosur if elected and not doing business with Brazil.
Key Indicators

Analysis by: Leonel Oliveira Mattos ([email protected]), Alan Lima ([email protected]), and Vitor Andrioli ([email protected]).
Translation by Rodolfo Abachi ([email protected]).
Financial editor: Paul Walton ([email protected]).


Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Gold Outlook: XAU/USD hit hard as US yields, dollar resume ascent
A stronger dollar, surging front-end yields and renewed geopolitical tension have combined to push gold back towards key technical support.


S&P 500 Forecast: SPX rises as oil prices fall, but treasuries remain at multi-decade highs
U.S. stocks are rising on Friday after a volatile week that saw a surge in Treasury yields ripple through financial markets.

USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.