



US Dollar Bulls Return as Euro and Pound Shorts Build | COT Report
US dollar net-longs surged at their fastest pace in seven years as futures traders added bearish exposure to the euro and British pound.
Share this:
US dollar bulls returned in force last week, with net-long exposure rising by $12.5 billion to $17.3 billion – the fastest weekly increase in seven years. Meanwhile, futures traders increased bearish exposure to both the euro and British pound as the dollar rally gathered momentum.
View related analysis:
US Dollar Longs Surge as Euro and Pound Positioning Turns Bearish
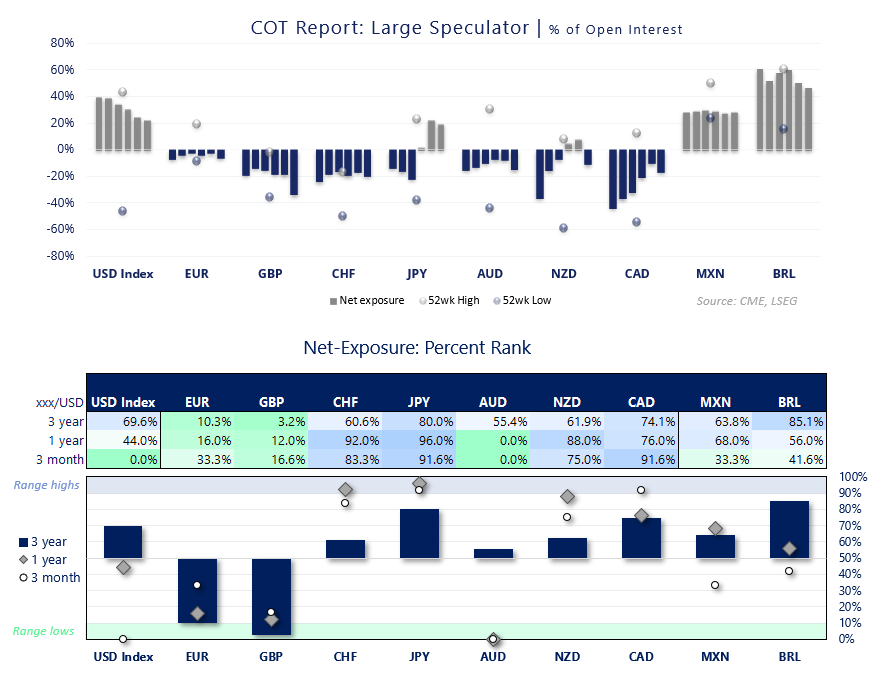
Large Speculator Positioning from the COT report
Source: CFTC (COT), LSEG
- US Dollar: Net-longs rose at their fastest weekly pace in seven years by $12.5 billion to $17.3 billion
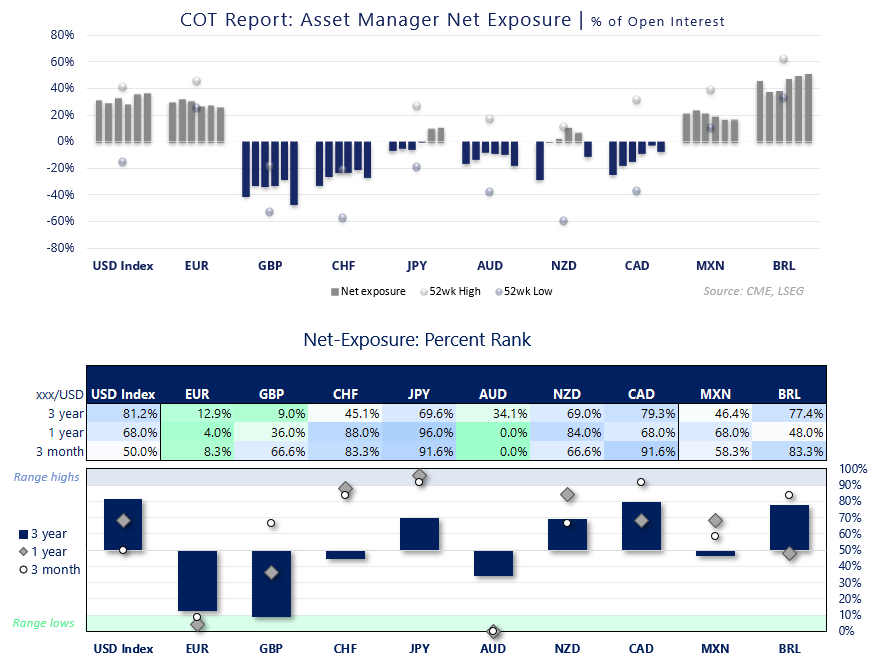
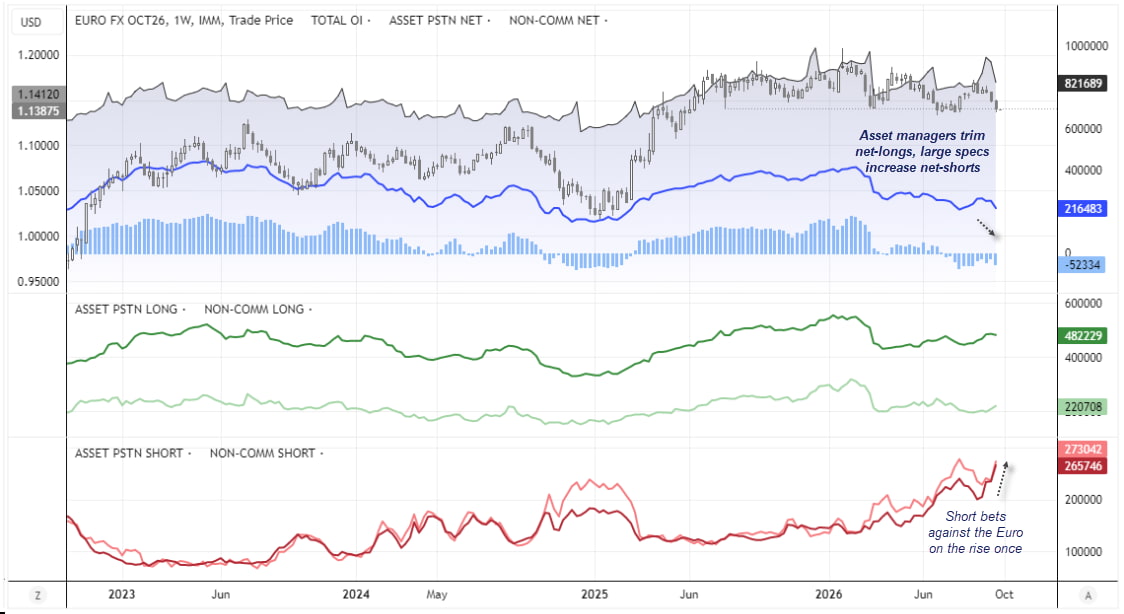
- EUR/USD: Asset managers reduced net-longs by 35k contracts and large specs increased net-shorts by 25k contracts
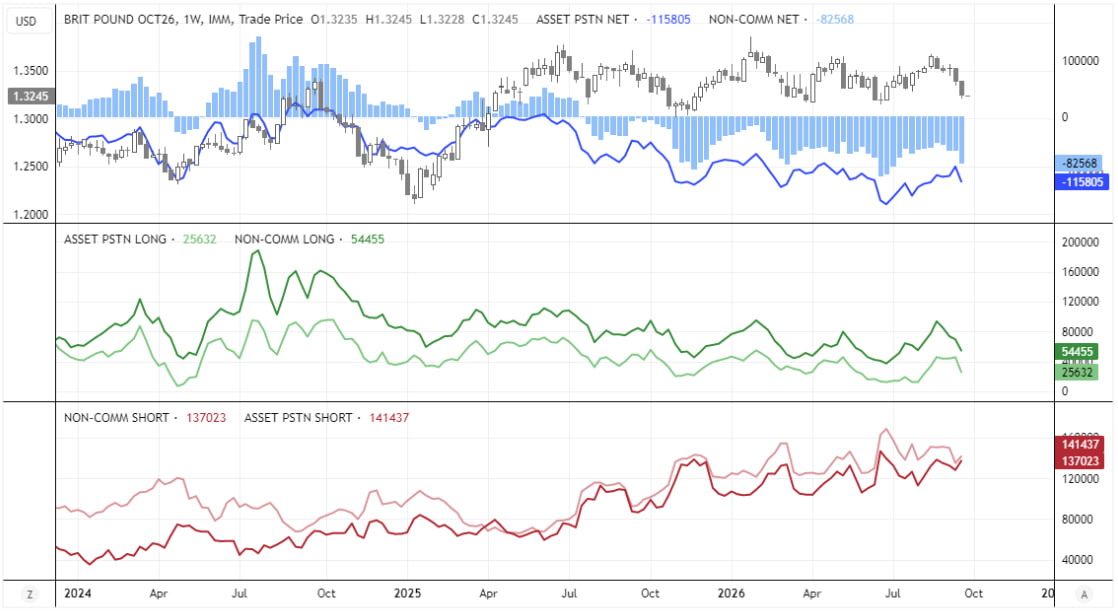
- GBP/USD: Net-shorts increased a combined 50.5k contracts to mark their fastest weekly rise in three months
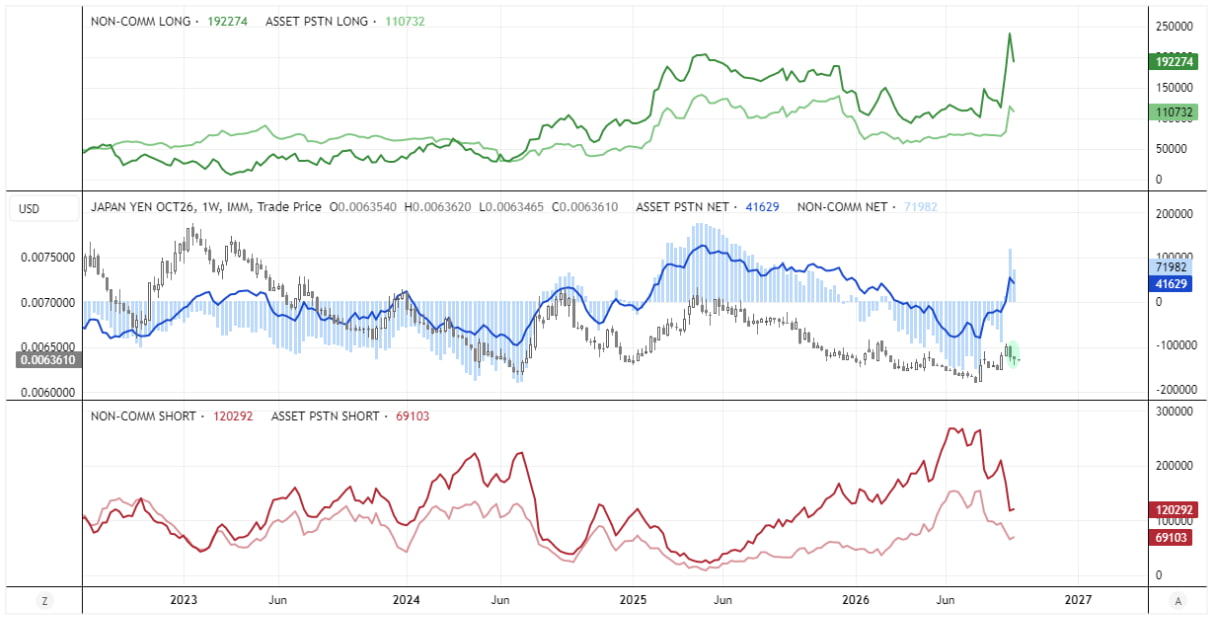
- USD/JPY: Traders remained net-long by a combined 113k, despite a reduction of around 58k contracts last week
- USD/CHF: Only minor adjustments kept net-short exposure to the Swiss franc by a combined 62.2k contracts
- USD/CAD: Prices continued to fall at a faster pace than net-shorts increased, suggesting the late surge of gross-longs have since been forced to cover
- AUD/USD: Open interest fell at the fastest weekly pace on record, though net-short exposure only increased marginally
- NZD/USD: Large specs and Asset managers reverted to net-short exposure
Asset Manager Positioning | COT Report
Source: CFTC (COT), LSEG
FX Futures Positioning | COT Report (IMM Data)
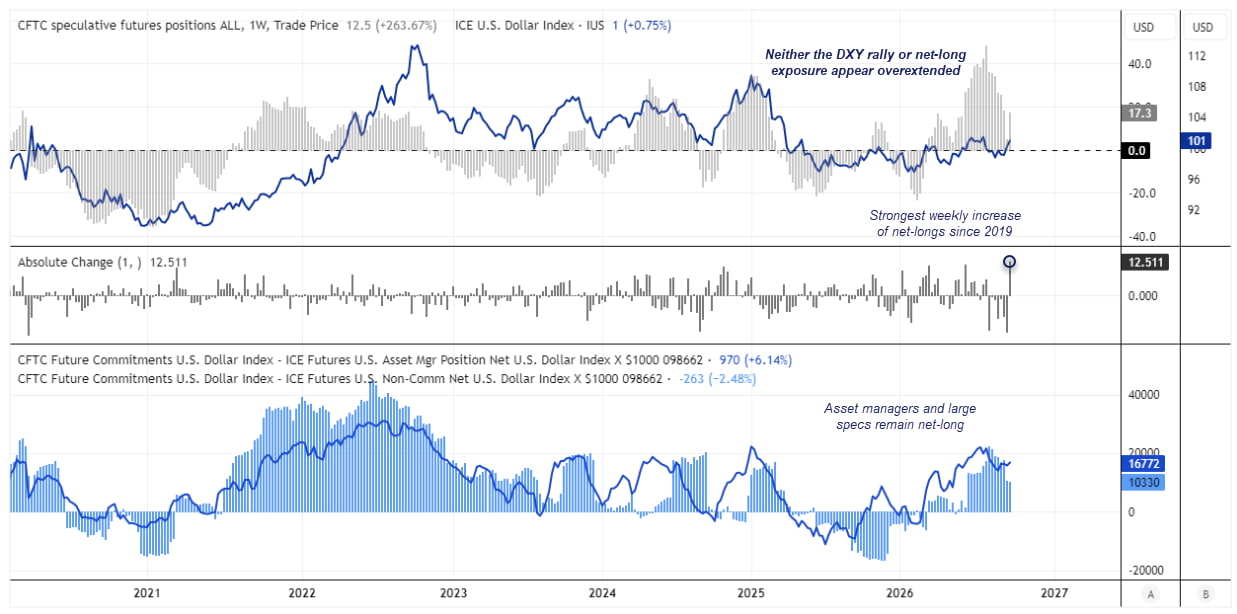
US Dollar Index (DXY) Futures Positioning | COT Report
We saw a strong influx of bullish bets on the US dollar last week, with net-long exposure rising by $12.5 billion to $17.3 billion – the fastest weekly increase in seven years. And I suspect we’ll see a further increase by the time the next COT report drops, given DXY was only up 0.4% by Tuesday’s close – and went on to rise a further 0.8% by Thursday’s high.
The US dollar index has now rallied 2.6% in 11 days, so I do not think Friday’s pullback is enough to call an end to this rally. Especially since neither the US dollar index nor net-long exposure is near a sentiment extreme.
Traders have a plethora of Fed members speaking this week, alongside ISM, NFP and PCE inflation. My guess at this stage is that they will show a strong economy with inflationary pressures, which leaves little room for Fed members to be any less hawkish than they have been since their last hike.
Source: CFTC (COT), ICE, LSEG
This content was created by an affiliate of FOREX.com and represents the views and opinions of the author/speakers, not the views and opinions of FOREX.com, StoneX Group Inc., or its subsidiaries. The content has not been independently reviewed by FOREX.com.
EUR/USD Futures Positioning | COT Report
My assumption over the past few months that the euro had bottomed is on the brink of being invalidated. But with momentum moving aggressively towards those swing lows, we may not need to wait for the break to invalidate it. The way prices move to or from a level can sometimes be just as, or even more, important than the level itself.
Net-short exposure to EUR/USD futures rose to a five-week high among large speculators, nearly doubling after increasing by 25k contracts over the week. Asset managers reduced net-longs by 35k, resulting in an effective combined shift of around 60k contracts towards a more bearish euro position.
Source: CFTC (COT), CME, LSEG
GBP/USD Futures Positioning | COT Report
It appears the British pound wants to head for its range lows around 1.3150, judging by how bearish momentum is accelerating towards the June low. Gross shorts have been trending higher for a couple of years, yet interestingly, net-short exposure is not flashing an imminent sentiment-extreme warning. The US dollar remains in the driving seat, though diminishing odds of a BOE hike could also decide how quickly GBP/USD breaks that June low – if it takes that route.
Source: CFTC (COT), CME, LSEG
USD/JPY Futures Positioning | COT Report
I stand by my long-held assumption that we saw the low for the Japanese yen this year back in June. While it retraced lower for a second week, a bullish hammer formed on the weekly chart, suggesting the yen is trying to form a swing low.
While large speculators and asset managers trimmed gross longs, they’re not exactly in a rush to short this market after several rounds of intervention. Both sets of traders remain net-long, which supports my ‘buy the dip’ bias for the yen and translates into a ‘fade the rally’ bias for USD/JPY.
Source: CFTC (COT), CME, LSEG
Related tags:


Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

AUD/USD hammered by US yields and fading RBA hike bets
US yields, dollar strength and fading RBA hike bets have combined to drive AUD/USD to fresh multi-month lows. The macro and technical bias remains bearish, although history suggests parts of the move are now reaching unusually stretched levels.

Japanese Yen Outlook: USD/JPY, GBP/JPY, AUD/JPY Setups
USD/JPY and GBP/JPY show signs of stabilising, while AUD/JPY remains vulnerable as yen crosses deliver mixed technical signals.

EUR/USD Forecast: Euro Struggles to Find Support Even After U.S. PCE Data
The euro continues to face a challenging environment in the short term. The currency has struggled to regain ground against a U.S. dollar that remains firmly supported, a dynamic reflected in EUR/USD, which has now recorded three consecutive losing sessions and a decline of roughly 0.6%.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.