



AUD/USD Q4 Outlook: RBA and Fed Hikes Set the Tone
AUD/USD enters Q4 with RBA and Fed hikes in focus as sticky inflation, rising unemployment and US dollar strength shape the Australian dollar.
Share this:
The Australian dollar enters Q4 with monetary policy firmly back in control of the macro narrative. The Fed has already resumed tightening, while markets expect the RBA to deliver at least one more hike as persistent inflation keeps policymakers on alert.
That leaves AUD/USD facing a more balanced rate backdrop than it did entering Q3. Australian rate expectations have risen sharply, yet the Aussie has still retreated from its Q3 highs as US dollar strength and broader risk sentiment outweigh the increasingly supportive yield differential.
The question for Q4 is whether rising unemployment gives the RBA enough room to pause after one more hike, while the Fed potentially tightens once or even twice more before year-end.
View related analysis:
AUD/USD Fundamental Outlook: RBA, Fed and Economic Data
The Australian economy continues to lose momentum, although the slowdown remains relatively orderly.
GDP increased just 0.4% in Q2 and 2.1% over the year, while the unemployment rate climbed to 4.6% in August. Full-time employment also fell during the month, even though headline employment increased by 39,500 as part-time jobs rose sharply.
Those figures provide further evidence that the labour market is gradually easing under the weight of higher interest rates. However, they hardly point to an economy falling off a cliff. Participation remains historically high, household spending increased for a third consecutive month in July and wages were still growing at 3.2% year-on-year in Q2.
Inflation therefore remains the greater headache for the RBA. Trimmed mean inflation remains elevated at 3.6% year-on-year, while the RBA expects underlying inflation to ease only gradually back towards its 2–3% target range. Markets also expect at least one further RBA hike this quarter, which would take the cash rate to 4.60%.
That leaves policymakers facing the uncomfortable combination of slowing growth and rising unemployment alongside inflation that remains too high.
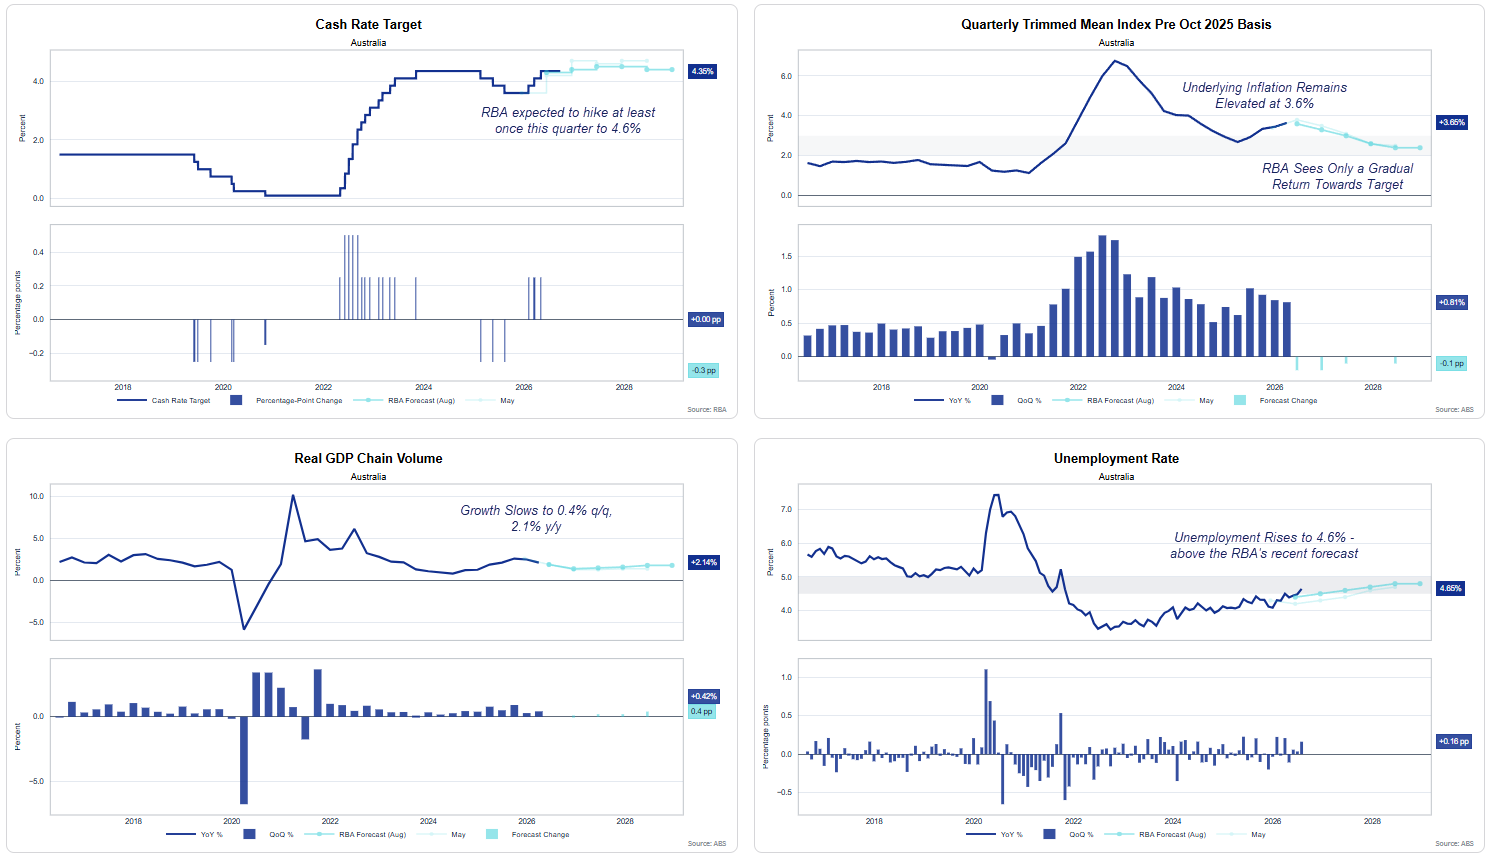
Source: ABS
Takeaway: Australia's economy is slowing, but persistent underlying inflation gives the RBA little room to declare victory.
RBA Outlook: One More Hike, then a Q4 Pause?
Markets expect another 25bp increase to 4.60%, and OIS pricing implies some risk of further tightening beyond that. However, I suspect rising unemployment will allow the RBA to stop at 4.60% through the remainder of Q4 and reassess whether another hike is required in February.
The renewed rise in crude oil prices has complicated the outlook considerably. Energy prices initially retreated during Q3, but renewed Middle East tensions have pushed crude oil sharply higher and increased the risk that higher fuel, freight and production costs feed into consumer prices.
Governor Michele Bullock has also warned that some of the inflation risks identified by the RBA appear to be materialising. With underlying inflation still running at 3.6%, another hike remains difficult to rule out.
However, the labour market provides an important counterweight. Unemployment has already risen to 4.6%, and further increases would strengthen the case for giving the existing tightening more time to work.
That makes 4.60% my base case for the cash rate through Q4. Unless inflation delivers another material upside surprise, February looks a more likely opportunity to reassess whether further tightening is required.
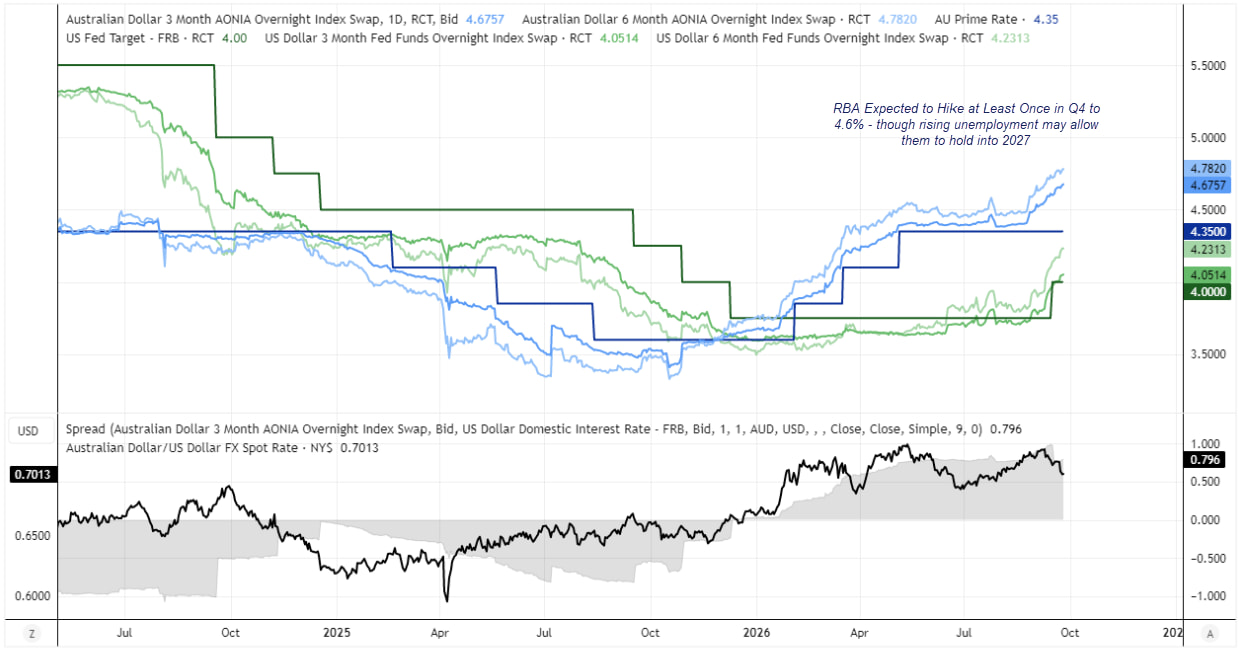
Source: LSEG, Reserve Bank of Australia, Federal Reserve.
Takeaway: I expect one further RBA hike to 4.60%, before rising unemployment allows policymakers to pause through Q4 and reassess the need for further tightening in February.
Fed Outlook: Another Hike Remains a Live Q4 Risk
The Fed delivered the rate hike that markets were only beginning to contemplate when the Q3 outlook was published. September’s unanimous 25bp increase lifted the federal funds target range to 3.75–4.00%.
The Fed’s updated projections point to a median year-end policy rate of 4.1%, which is broadly consistent with one further 25bp hike before the end of the year. However, market pricing has turned more hawkish. Fed funds futures currently imply around a 76% chance of another hike in October, while December pricing assigns roughly a 59% probability to rates reaching 4.25–4.50% — effectively two further 25bp hikes in Q4.
There is enough resilience in the US economy to support that argument. Payrolls increased by 162,000 in August and unemployment remained at 4.1%, while the ISM services index accelerated to 55.4. More importantly for the Fed, the services prices index climbed to 72.6, its highest level since August 2022.
Inflation also remains uncomfortable. Headline CPI increased 3.4% year-on-year in August, while July PCE inflation stood at 3.7%. Core CPI was softer at 2.4%, although core PCE remained higher at 3.3%.
However, there are signs that tighter financial conditions are beginning to bite. Q2 GDP slowed to an annualised 1.5%, while the ISM services employment index remained in contraction territory at 47.8.
That makes incoming inflation and employment data critical. Continued resilience alongside elevated inflation would strengthen the case for one or even two further hikes and likely keep the US dollar supported. A sharper deterioration in activity would make that path harder to deliver and could instead bring forward a peak in US yields and the dollar.
Takeaway: The Fed’s own projections point to one more hike in Q4, but markets are increasingly pricing the risk of two. That keeps the US dollar supported unless growth or inflation data weaken materially.
This content was created by an affiliate of FOREX.com and represents the views and opinions of the author/speakers, not the views and opinions of FOREX.com, StoneX Group Inc., or its subsidiaries. The content has not been independently reviewed by FOREX.com.
AUD/USD Technical Outlook: Charts, Positioning and Seasonality
AUD/USD Chart Signals Turn More Cautious
If the Aussie can close the month above 0.6919, it will have notched up its seventh consecutive bullish quarter. However, it could also mark its second shooting star candle over this period, with both forming around the upper wick of Q3. And with quarterly volatility also falling, it has the hallmarks of a market that may be topping out.
The correlation with the Chinese yuan is not what it once was, with AUD/USD instead showing a stronger relationship with the US dollar — albeit an inverse one.
The US dollar index appears to be headed for 104 and is on the cusp of forming a three-month bullish reversal pattern called a morning star. With the Fed potentially hiking twice this quarter, the US dollar could be in for a strong Q4, which could weigh on AUD/USD.
That could see traders fading into rallies and eyeing a potential break of the March low. Note that the three-month implied-volatility band has blown out to around 420 pips either side, which could potentially see the Aussie heading below 67c if the selloff continues.
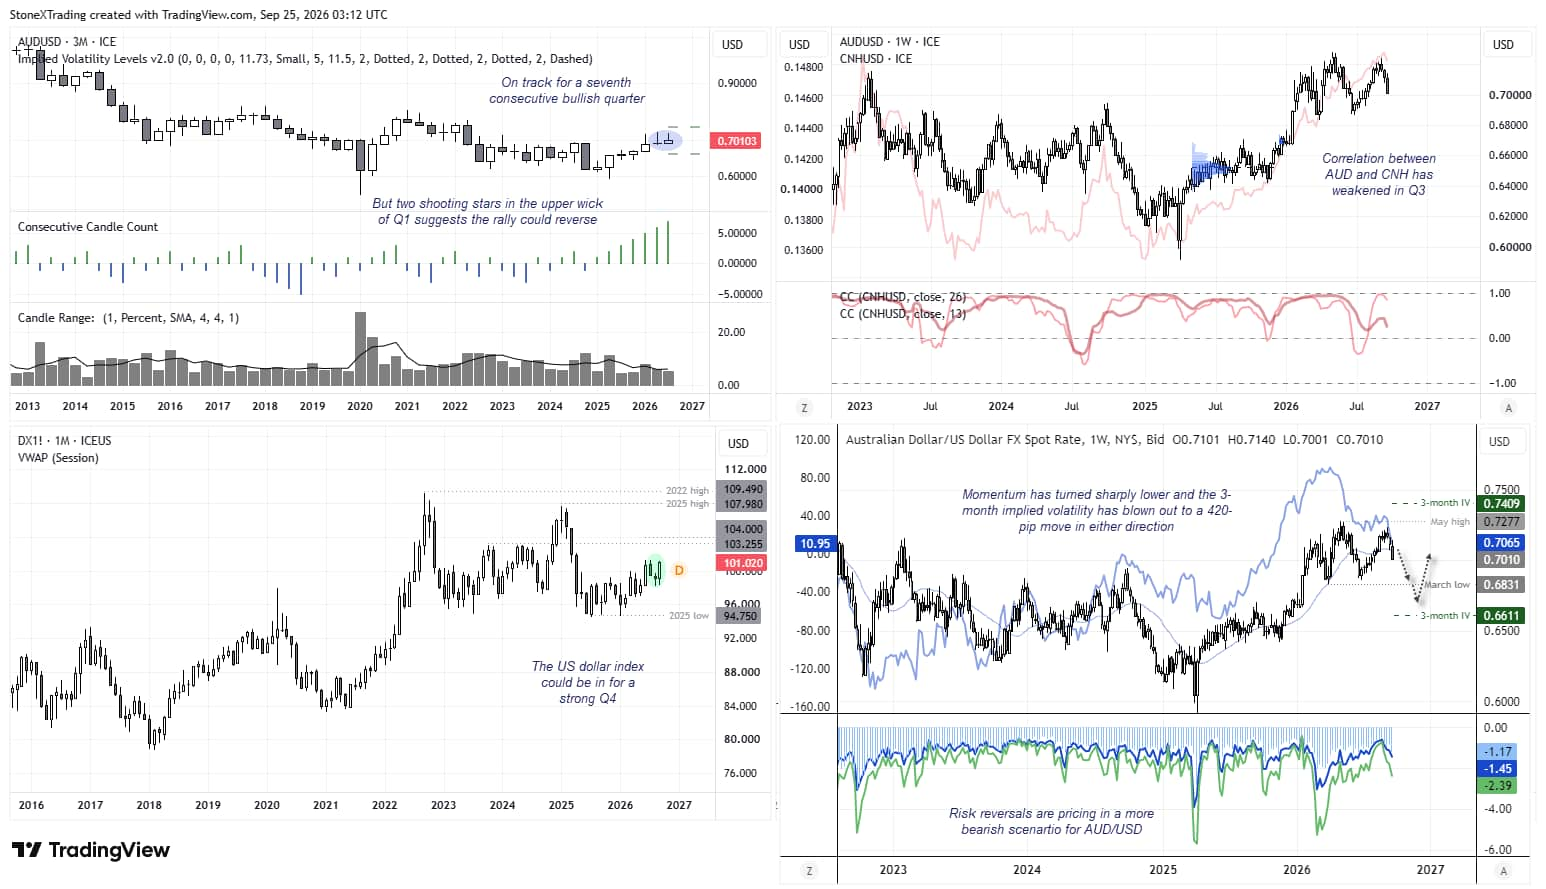
Source: ICE, TradingView
Takeaway: AUD/USD has lost momentum below 0.7200, but its Q4 direction may ultimately depend more on whether the US dollar extends its rebound or finally forms a cyclical peak.

Q4 Seasonality Improves Towards December
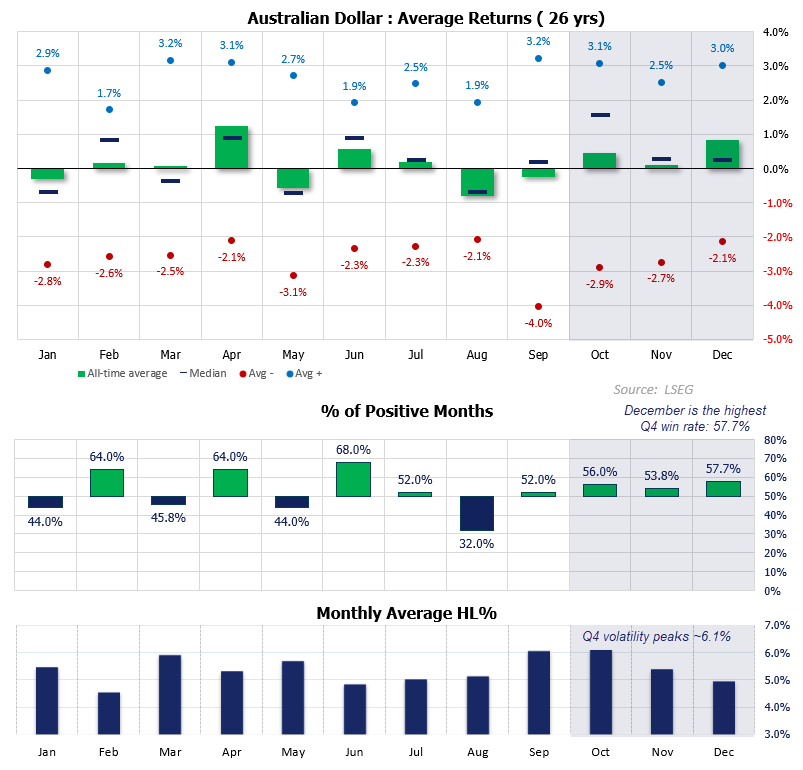
The basic seasonality pattern in Q4 is diminishing volatility through to December, alongside positive win rates, average returns and median returns. December has posted the strongest average return of the quarter at 0.84% and a win rate of 57.7%, although its median return is just 0.24%.
Returns have been effectively flat in November, while its average loss of 2.7% outweighs the average gain of 2.5%.
While seasonality patterns are useful to know, they’re not a roadmap to future gains. Macro drivers — such as a hawkish Fed or broader risk-off tone — could easily override seasonal tendencies and weigh on AUD/USD.
Source: LSEG
Takeaway: Q4 seasonality carries a modest bullish bias for AUD/USD, with positive returns across the quarter and volatility tending to diminish into December. But macro drivers can easily override the seasonal pattern.
AUD/USD Futures Positioning Sends Mixed Signals
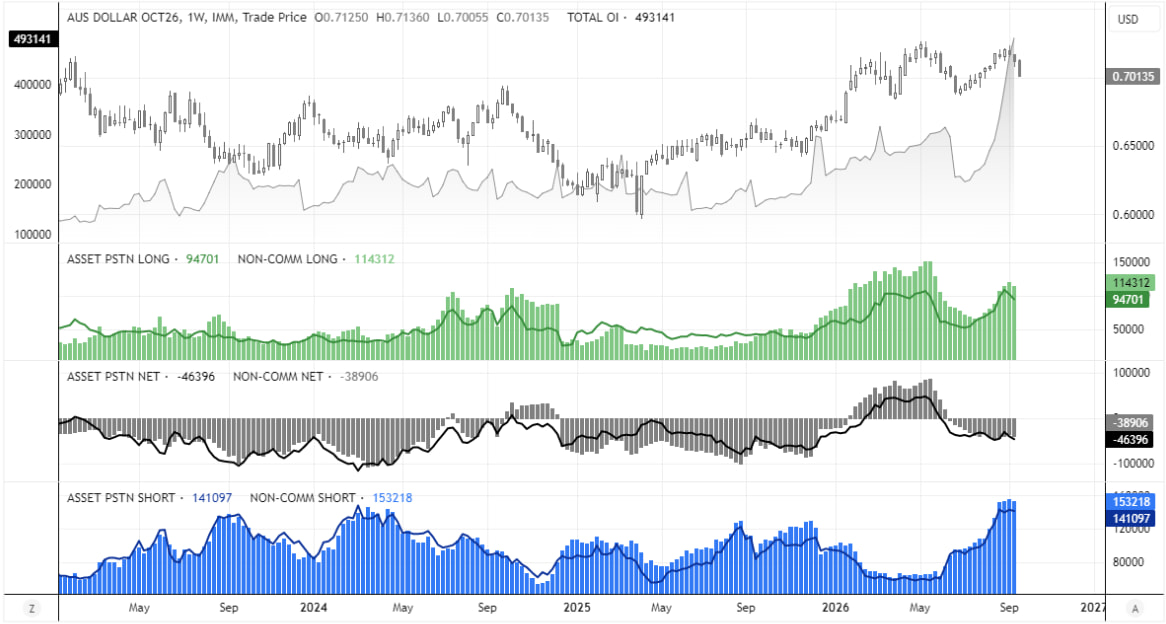
Throughout Q3 I noted that AUD/USD prices were accelerating higher despite futures traders remaining net short. That caution now looks better justified following the reversal around 72c and the accelerating three-week decline. Total open interest had also risen to a record high, with the latest data showing its fastest 10-week increase on record.
Yet the recent deterioration in positioning may actually be more about a reduction in gross longs than a fresh wave of short selling, given gross shorts were already just below record highs last week. This suggests positioning may be approaching a sentiment extreme, even though prices currently are not.
Source: CME, CFTC (COT), LSEG
Takeaway: AUD futures positioning remains bearish, but with shorts already near record highs and open interest elevated, sentiment may be closer to an extreme than price action suggests.
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Gold, silver outlook: Sandwiched between bullish bonds and AI angst
XAU/USD and XAG/USD may be approaching a bullish turning point as Treasury futures threaten a breakout. The problem? Both metals have recently been trading more like tech stocks than havens.
USD/CHF Feels the Weight of US Midterms, USD/CAD Clings to Support
US midterms threaten fresh dollar volatility as USD/CHF tests technical support and USD/CAD clings to 1.3940 ahead of election results.
US Dollar, GBP/USD, USD/CAD, USD/CHF, Gold Weekly Technical Outlook 11 2 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.