



Australian Dollar Outlook: AUD/USD Retraces Ahead of Jobs, Trump–Xi Summit
AUD/USD outlook ahead of Australian employment, RBA speakers and the Trump–Xi summit as the Aussie extends its two-week retracement.
Share this:
The Australian dollar’s rally finally faltered last week as stronger US inflation data, rising crude oil prices and a firmer US dollar weighed on AUD/USD. Attention now shifts to Australia’s final employment report before next week’s RBA decision, alongside fresh RBA commentary and the Trump–Xi summit.
View related analysis:
AUD/USD Retraces as Jobs, RBA and Trump–Xi Come into Focus
Bullock Keeps RBA Hike Risk Alive
RBA Governor Bullock struck a hawkish tone before the House on Friday, warning that inflation risks are already materialising through the Middle East conflict, the AI investment boom and other cost pressures. She also made it clear that demand still needs to cool while productivity remains weak, keeping the door firmly open to another hike.
The hearing also put the RBA’s modelling under the spotlight after officials admitted they had not run one to consider how a large cut in government spending might affect inflation.
Fed Hikes, Though 2027 Path Remains Uncertain
Meanwhile, the Fed delivered its expected rate hike and effectively signalled another move by December, although its median forecasts stopped short of endorsing the two additional hikes money markets had been trying to price in.
Overall, the US dollar rally looks a little stretched on the daily chart, although the weekly structure remains solid. That could allow for a modest AUD/USD bounce before another leg lower, but I suspect any recovery may be limited at this stage.
Australia This Week: Economic Data and Events for AUD/USD Traders
Australian Jobs and Bullock Could Seal the RBA Hike Case
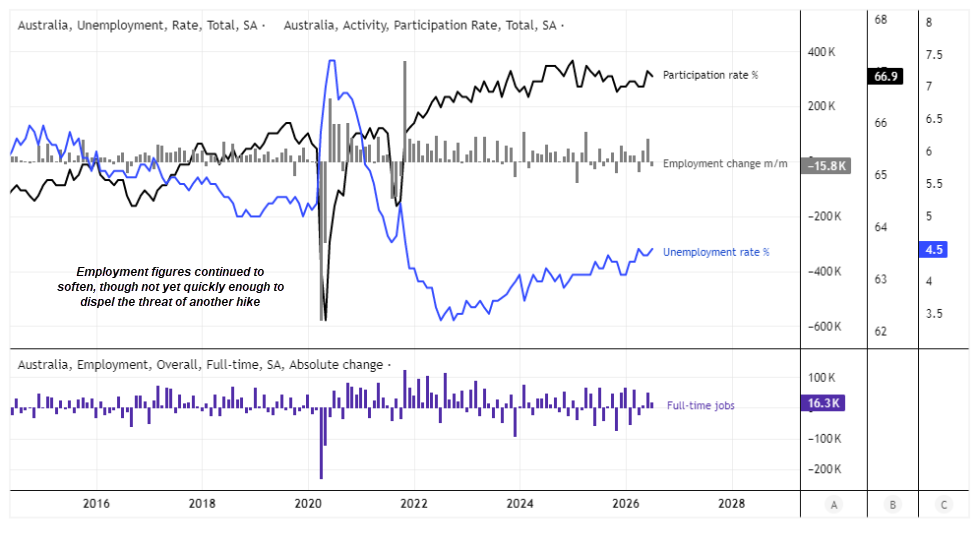
This week brings Australia’s final employment report ahead of next week’s RBA cash rate decision. With the majority of big banks and market pricing backing a hike, it would likely take quite a downside shock from the jobs figures to derail expectations at this point.
The 1-month OIS is currently around 15bp above the cash rate, which roughly implies a 60% chance of a 25bp hike at the meeting. The 3-month OIS has effectively priced in one full 25bp hike, while the 1-year implies nearly 60bp of tightening — or just over two full hikes.
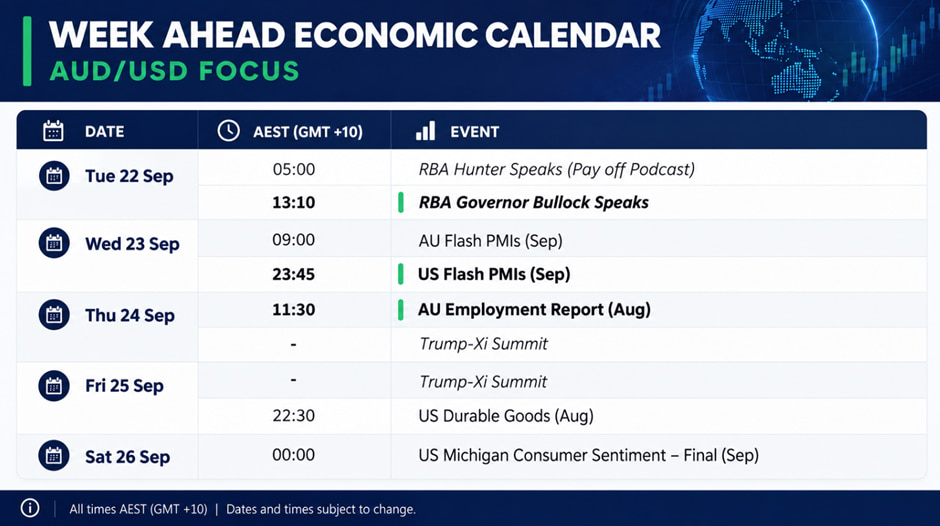
That said, the jobs report may matter less if Governor Bullock decides to ramp up expectations of a hike when she speaks on Tuesday. If she wants to steer markets towards a move next week, this would be an ideal opportunity.
Source: ABS, LSEG
Trump–Xi Summit Puts China Risk Back on the AUD/USD Radar
Trump and Xi meet in Washington on Thursday, with trade likely to dominate the agenda. Markets will be watching for progress on extending the US-China tariff truce, alongside potential tariff reductions, agricultural purchases, technology restrictions and critical minerals.
This could leave AUD/USD vulnerable to any shift in sentiment, given the Aussie’s sensitivity to China, the yuan and broader risk appetite. A constructive outcome could support AUD, while renewed trade tensions would likely work in the opposite direction.
AUD/USD Technical Analysis: Australian Dollar vs US Dollar
AUD/USD Correlations Keep the US Dollar in Focus
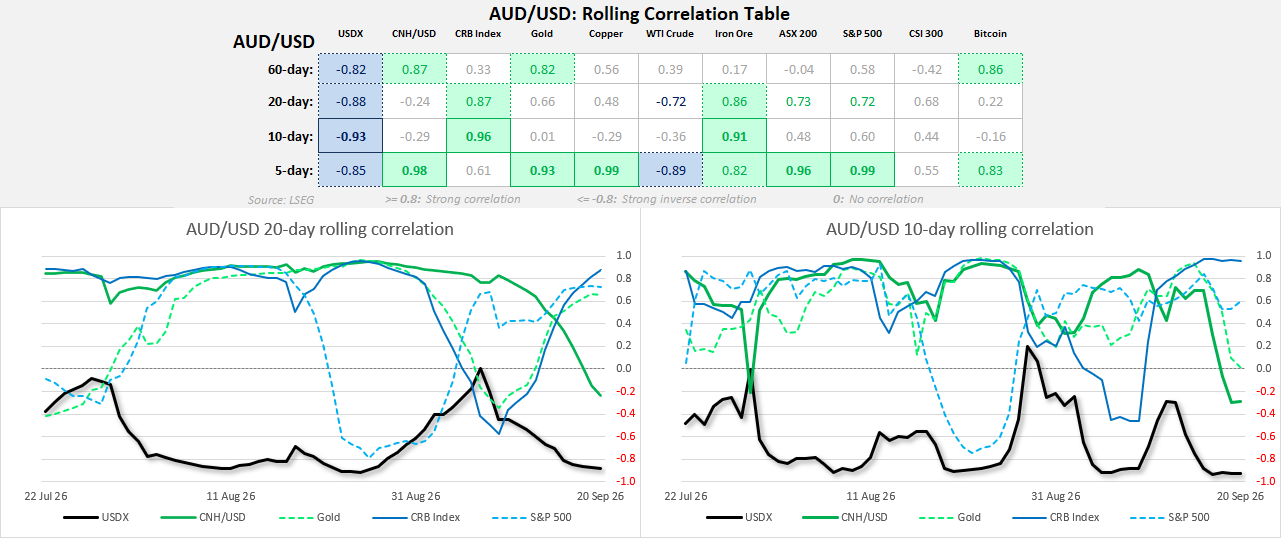
- DXY remains the main external driver: AUD/USD is still strongly inversely correlated with the US dollar, so any follow-through from Friday’s DXY shooting star could support an early-week bounce.
- Risk appetite still matters: AUD/USD has recently moved closely with equities, copper and iron ore, so stronger risk sentiment would likely help the Aussie while a renewed risk-off move would work against it.
- China signals are less reliable right now: The yuan relationship has been choppy across shorter timeframes, so CNH is probably better used as confirmation rather than the main trading cue.
Source: LSEG
AUD/USD Futures Positioning | COT Report
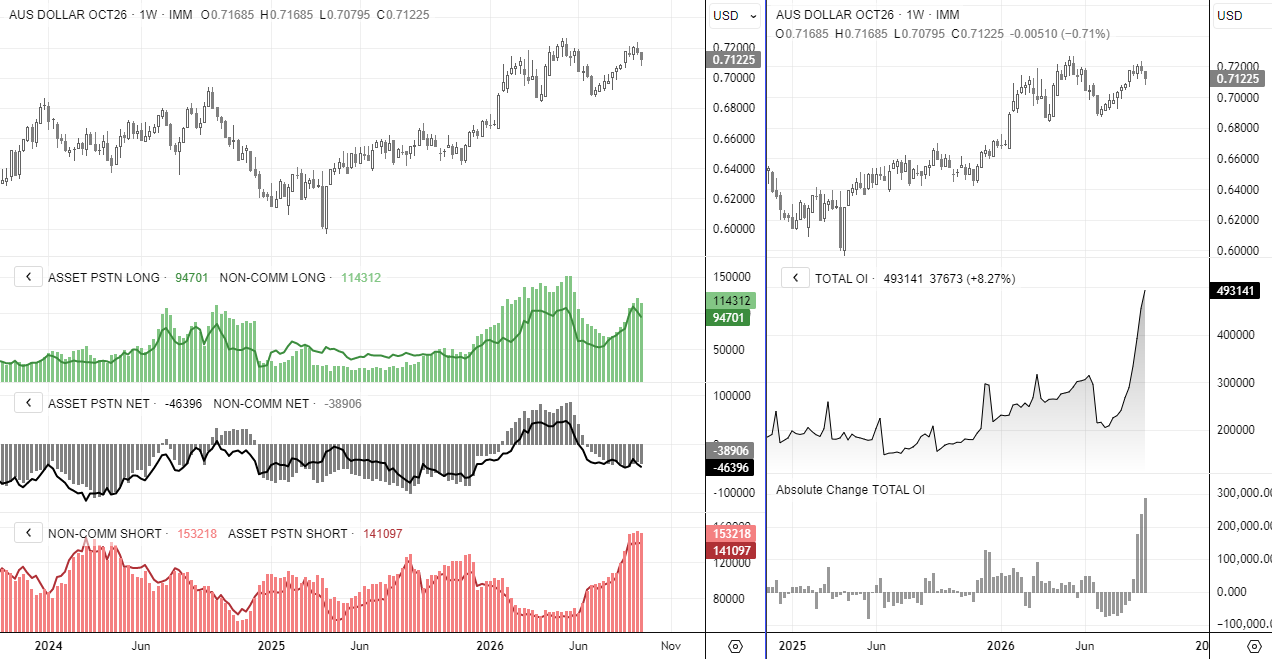
Demand for the Australian dollar remains apparent across the futures market. Total open interest reached yet another record high, marking its 10th consecutive weekly increase. In fact, the 288k rise in open interest over the past 10 weeks is also a new record.
That makes the marginal increase in net shorts among large speculators and asset managers something of a moot point, while the two-week pullback in AUD/USD looks healthy given the prior 10-week rally. AUD/USD may still be undergoing a correction, but it is one that dip buyers may be waiting to capitalise on and prevent from becoming too deep.
Source: CFTC (COT) CME, LSEG

AUD/USD Options and Volatility Analysis (Risk Reversals, HVN Levels)
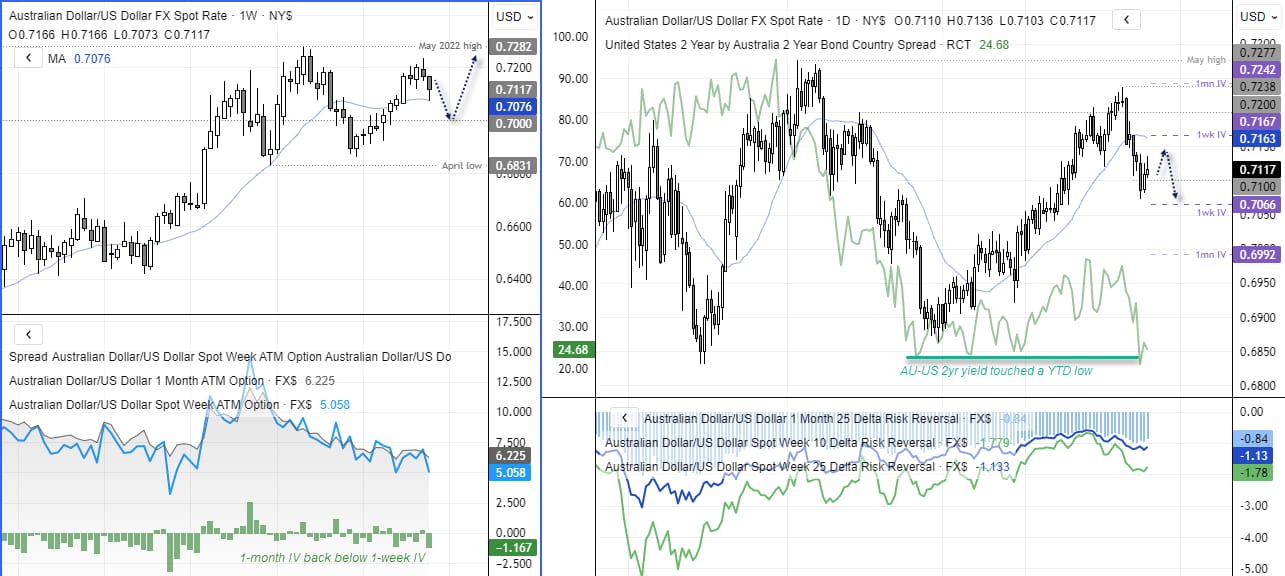
Implied volatility actually finished lower last week despite the pickup in realised volatility. Also note that 1-month IV is back below 1-week IV, suggesting traders are not overly alarmed by the two-week pullback in AUD/USD heading into this week’s trade. Given the shooting star candle on the US dollar index daily chart, perhaps a minor pullback is due — and that could benefit AUD/USD early this week.
However, the AU-US 2-year yield spread fell to a year-to-date low last week, leaving yields unfavourable for any meaningful AUD/USD rebound. That said, risk reversals remain supported, which is another clue that we may not be staring at a particularly deep pullback in the Australian dollar. That also lines up with the analysis from the Commitment of Traders report.
A break of last week’s low and the 20-week SMA would open the door to a move towards 70c, a level I suspect will hold for now. Any rebound towards the 20-day EMA and upper 1-week implied volatility level could be tempting for bears over the near term.
Source: ICE, TradingView
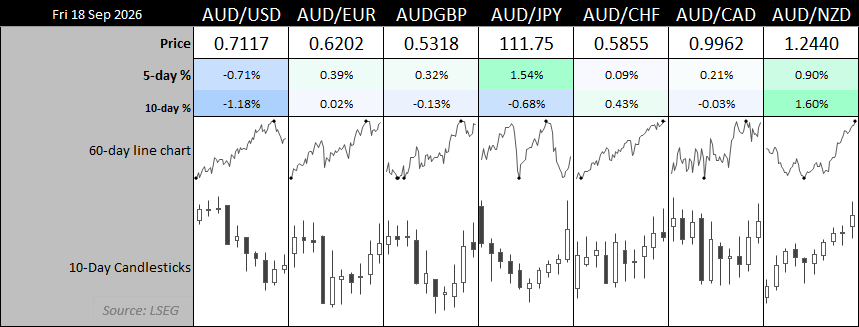
Australian Dollar Performance
Source: LSEG
Related tags:


Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/JPY forecast: US dollar strengths amid hawkish Fed despite recent oil weakness
The US dollar has extended its gains this morning, even if oil prices finished lower for the fifth consecutive day yesterday. Oil prices have bounced back in this first half of today’s session, causing a bit of pressure on currencies that rely on energy imports such as the euro, pound, Swiss franc, and Japanese yen. But it was the dollar that was exerting the most pressure, amid hawkish FedSpeak. Meanwhile, European indices and precious metals were also under a bit of pressure amid the strength of the dollar.
USD/JPY and USD/CHF Could Diverge as CHF/JPY Approaches Resistance
USD/JPY and USD/CHF retain bullish structures, but CHF/JPY resistance could expose a divergence between the two US dollar pairs.

EUR/AUD, GBP/AUD Outlook: Rates, risk and metals reinforce bearish technical case
EUR/AUD and GBP/AUD are coiling near support, with recent correlations suggesting the Aussie’s strength is being driven more by rates, risk and metals than energy.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.