



Bulls back in charge, NASDAQ and S&P rally
The Fed didn’t shock anyone with its unanimous decision to hold rates, but it did surprise markets with its post-meeting statement that rates could rise again, and three officials predicting a 6% peak (possibly two more raises from the present 5.25-5.50% range.) Equity markets fell on the news but soon bouWall Street put the Federal Reserve's comments and a ‘no rate hike’ meeting in its rear-view mirror as stocks pushed higher today on renewed optimism about the US economy, paradoxically something which might lead the Fed to raise rates as it hinted yesterday. Data on consumer spend and jobless claims point to continuing economic strength Bottom line – risk-on.
Share this:

Wall Street put the Federal Reserve's comments and a ‘no rate hike’ meeting in its rear-view mirror as stocks pushed higher today on renewed optimism about the US economy, paradoxically something which might lead the Fed to raise rates as it hinted yesterday. Data on consumer spend and jobless claims point to continuing economic strength
Bottom line – risk-on.
TODAY’S MAJOR NEWS
Fed’s “hawkish pause”
Wall Street got the “hawkish pause” it expected, after 10 hikes in ten months, but the Federal Reserve made it clear that it is not done yet. Rather, it made clear that two more rate hikes would be likely this year. Fed members made it very clear in their statement that they did not want the markets to misconstrue this month’s pause as a pivot, with 12 of the 18 members indicating support for the future rate hikes. The markets had previously priced in one more rate hike in July, and that cuts would begin by the end of the year. If that is the bull market narrative it might be wide of the mark.
Fed Chair Jerome Powell understands the risks of resurgent inflation as long as stimulus remains in the system. He believes that tighter credit standards by banks will help do the job of slowing the economy, reducing the need for further significant rate hikes. However, this thesis needs time to be proven – rather the contrary could be true. A dovish interest policy could is leading to a resurgent stock market, optimistic consumer confidence, an increase in spending, and a rebound in the housing sector. And this could reignite inflation before sufficient stimulus has been withdrawn.
The Fed is trying to talk down this enthusiasm by indicating that two more rates hikes, and at a 6% peak interest rate, might be administered. But is anyone listening? For contrast, the European Central Bank moved forward with another 25-basis point rate hike this morning. Powell made it clear that the primary challenge remaining to hit the 2% mandate for inflation is cooling the consumer economy and bringing down wage inflation. This might take some doing.
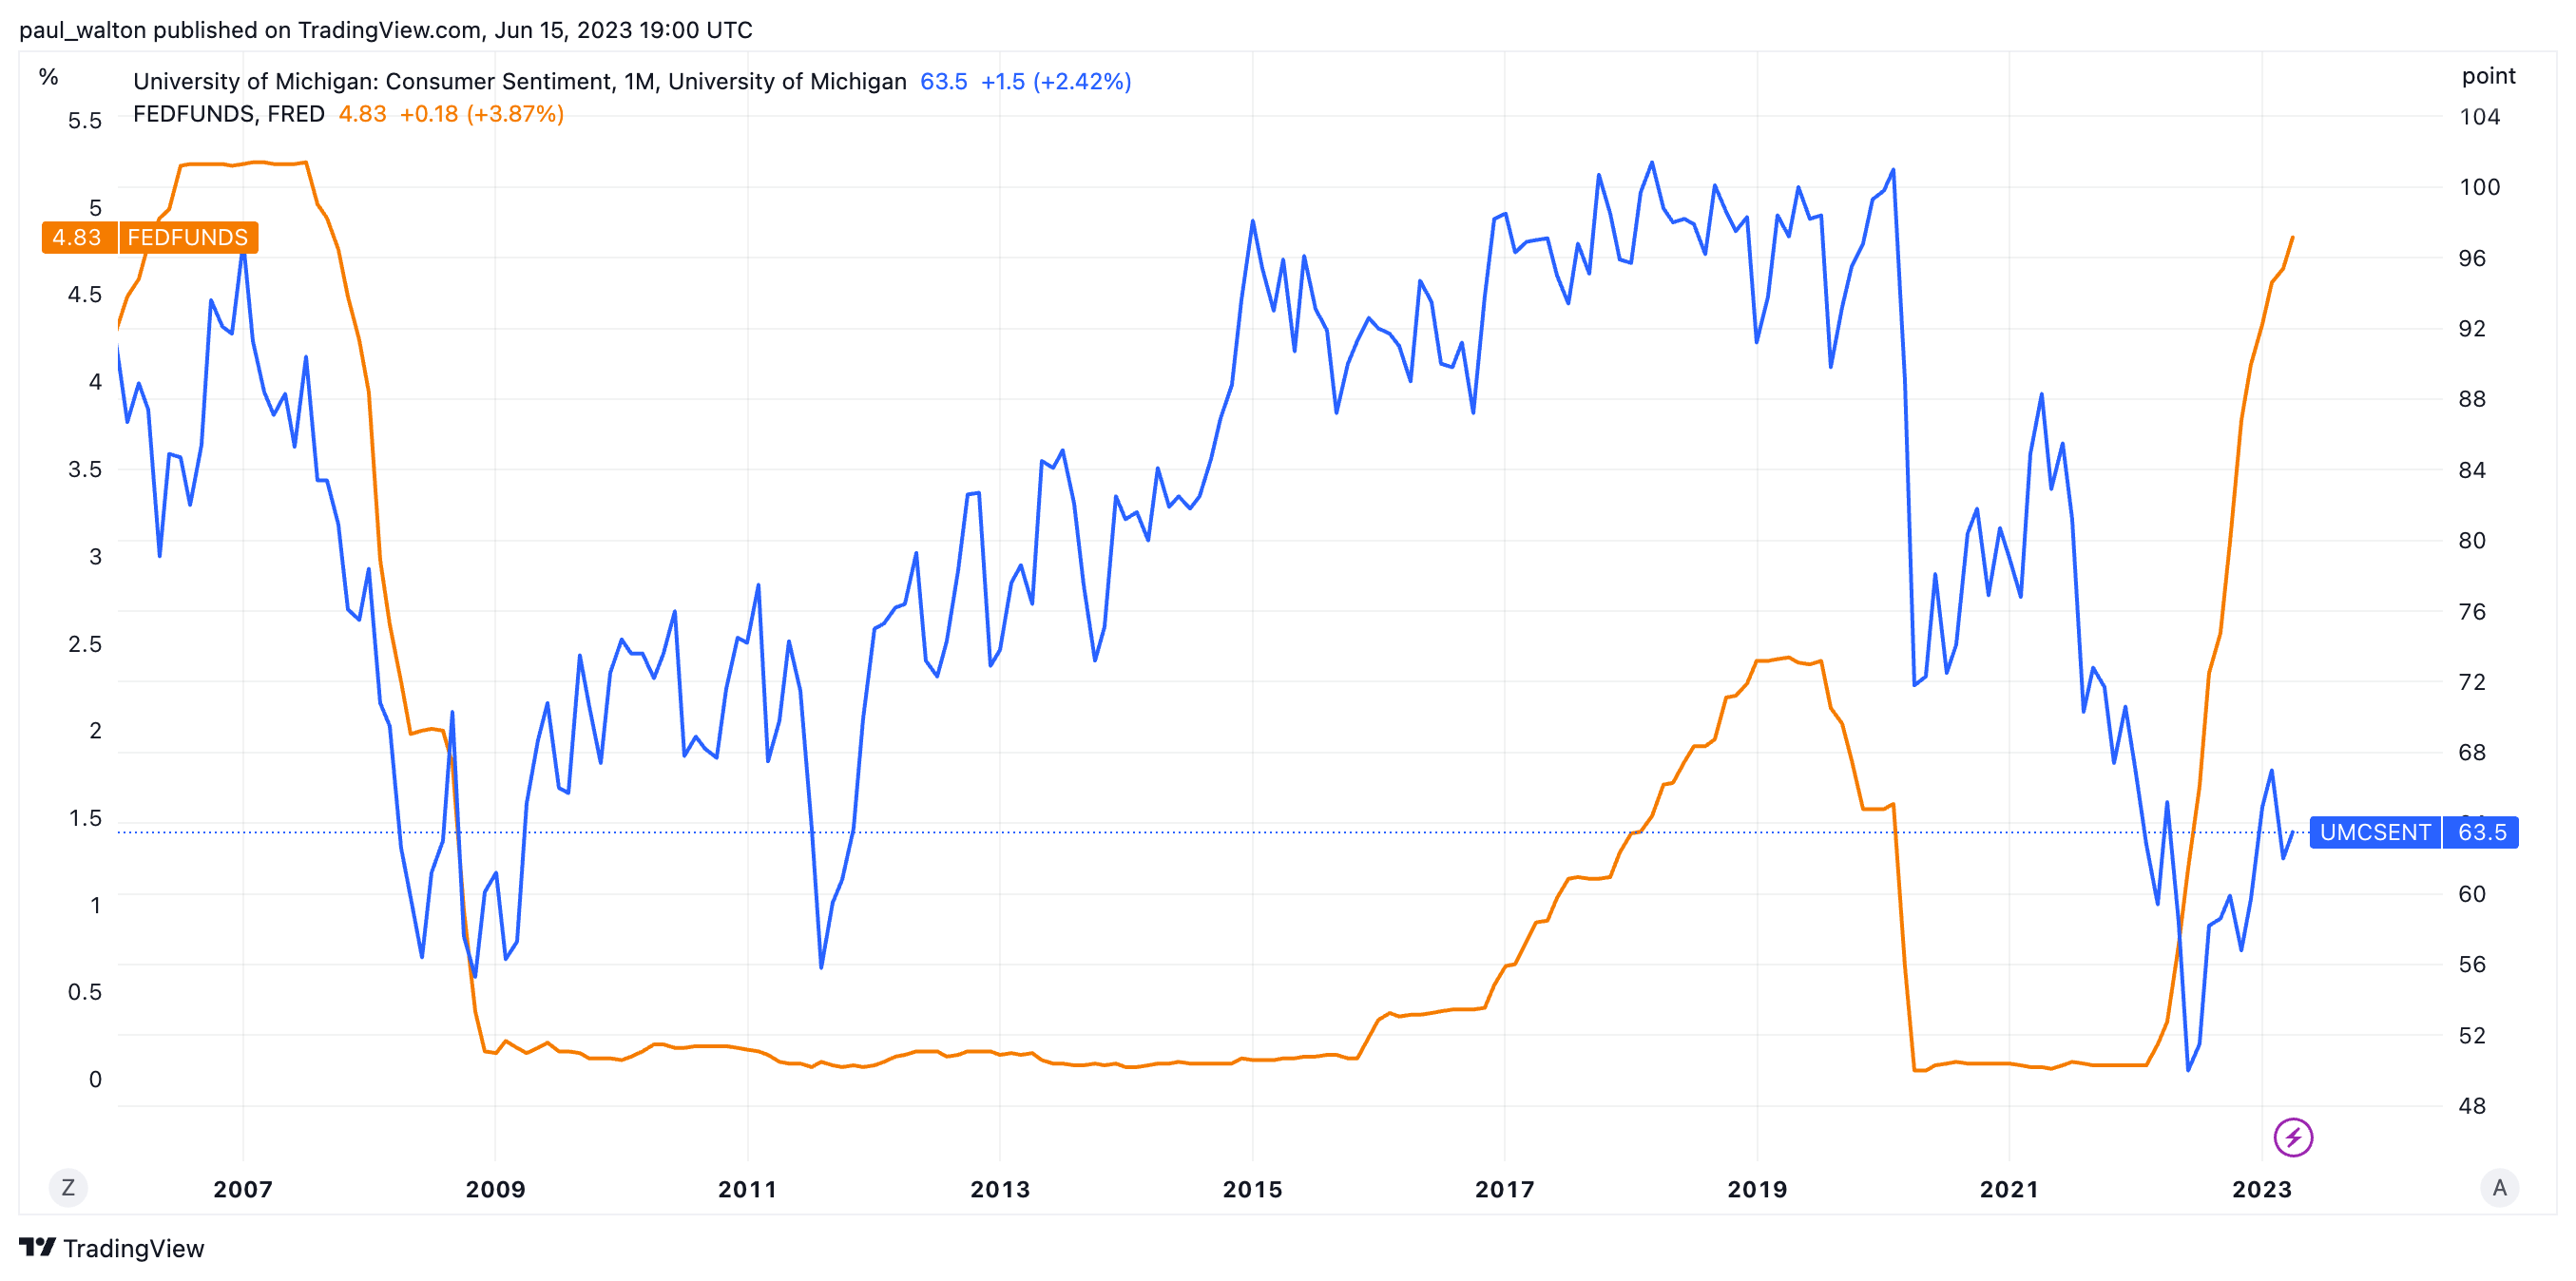
Consumer sentiment can often take time to catch up with rate rises, as the chart below for the University of Michigan Consumer Confidence index versus the Fed Funds rate makes clear. The Fed is betting that its rate increases will, in due course impact consumer spending, the real economy and inflation (as was the case in 2007-08 and 2020 onwards, Covid notwithstanding.)
University of Michigan Consumer Confidence index versus the Fed Funds rate
Retail sales growth continues to be resilient
- A sustained rate of consumer buying and a resurgence in auto sales were partly offset by falling gas prices in May retail sales
- Retail sales for May grew 1.6% year-on-year, ahead of analyst expectations, with signs of underlying consumer confidence
- Retail sales grew 0.3% month-on-month, versus an expected 0.1% decline, and a shade lower than 0.4% growth in April
- Retail sales minus vehicles and gas rose 0.4% month-on-month, double the expected 0.2% growth, and a shade lower than 0.5% growth in April
Industrial production
- Industrial Production for May was down 0.2% month-on-month in May, below the expected 0.5% rise, and the 0.5% increase in April
- Manufacturing output grew by 0.1%, down from 1.0% growth last month
- Capacity utilization slipped slightly to 79.6% in May, down from 79.8% last month
Jobless claims don’t indicate major layoffs
- Jobless claims continue to reflect a relatively tight labor market when combined with many other data points from the sector, with no signs that current interest rates are leading to lay-offs
- First-time claims for unemployment benefits were unchanged in the week ending June 10 at 262,000, above an expected 248,000
- The four-week moving claims average rose to 246,750, up from 237,500 claims the previous week
- Continuous claims for the week ending June 3 rose 20,00 to 1.775 million, with the four-week moving average dropping by 6,000 to 1.778 million
TODAY’S MAJOR MARKETS
Equity markets
- The S&P 500 and Nasdaq 100 indexes rose 1.0%, and 0.9% respectiveley, while the more broadly based Russell 2000 was up 0.4%
- European stocks rallied despite the ECB’s rate hike, with the DAX up 1.3%
- The Nikkei 225 and FTSE 100 indexes were unchanged and up 0.3%, respectively
- The VIX, Wall Street’s fear index, rose 1.6% to 14.1
Currencies, Bonds and Crypto
- The dollar index fell back 0.8% to 101.8 against a basket of currencies, heading back to the bottom of its year-to-date trading range
- Euro and sterling x-rates versus the dollar were highlights, both up around 1.0%
- Bonds rallied after the Fed’ no-hike meeting, with yields on 2- and 10-year Treasuries lower at 4.63% and 3.73%
- Bitcoin is approaching a testing technical level around $25,000, with today’s 2.8% decline bring that past several week decline to 10%
Commodities
- Gold prices were unchanged at $1,970 per ounce
- Crude oil prices rebounded, up 3.4% to $70.6 per barrel
- Grain and oilseed markets were stronger on the weaker dollar and as continued dryness across the Midwest threatens crop yields
Analysis by Arlan Suderman, Chief Commodities Economist. [email protected].
Market outlook by Paul Walton, Financial Writer. [email protected].


Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

US Core PCE Preview: Stale or Significant for the Fed
Core PCE inflation takes center stage Wednesday, with traders watching for signs of renewed price pressure and clues on whether the Fed could hike again in October.


Gold Forecast: Are Bears Regaining Control of XAU/USD?
The start of the trading week has not been particularly favorable for gold. This can be seen in recent XAU/USD price action, with the metal falling nearly 4.00% over the last two trading sessions and bringing renewed attention to a bearish bias within the market.


Gold outlook: XAU/USD hammered, stretched and vulnerable to a sharp rebound
Gold is getting hammered for solid fundamental reasons, but history suggests extreme four-hourly oversold conditions can produce violent countertrend rallies.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.