




Europe Heads Higher Tech Under Pressure
The rotation from tech stocks into value stocks in response to a vaccine coming is driving market moves.
Share this:
Wall Street closed mixed with a significant divergence between old world stock and tech stock as investors continue to price in the Pfizer vaccine news and a return to “normal” life. The rotation from tech stocks into value stocks in response to a vaccine coming is driving market moves. The Dow closed 0.9% higher, whilst the tech heavy Nasdaq closed -1.3% in the red.
Faster global economic recovery
European stocks are pointing to a firmer start still buoyed by the game changing vaccine news from earlier in the week. In light of Pfizer’s announcement that its vaccine was found to be 90% effective, expectations are now for the global economy to recover considerably more quickly. Goldman Sachs is predicting US growth will be back to pre-pandemic levels by Q2 of 2021. Expectations for UK growth is , in some cases equally optimistic, and the UK could also return to pre-pandemic growth levels potentially as soon as mid-2021.
European stocks are pointing to a firmer start still buoyed by the game changing vaccine news from earlier in the week. In light of Pfizer’s announcement that its vaccine was found to be 90% effective, expectations are now for the global economy to recover considerably more quickly. Goldman Sachs is predicting US growth will be back to pre-pandemic levels by Q2 of 2021. Expectations for UK growth is , in some cases equally optimistic, and the UK could also return to pre-pandemic growth levels potentially as soon as mid-2021.
UK NIESR GDP data
The UK NIESR GDP reading for the three months to October is expected to show that momentum in the British economy kept building through Autumn, up 20.1% , compared to 15.2% in the 3 months to September. However, with lockdown 2.0 now in full swing November is expected to show a sharp fall. That doesn’t mean to say that October’s print is meaningless, a strong reading would reveal that the UK economy is falling this month from a stronger position.
The UK NIESR GDP reading for the three months to October is expected to show that momentum in the British economy kept building through Autumn, up 20.1% , compared to 15.2% in the 3 months to September. However, with lockdown 2.0 now in full swing November is expected to show a sharp fall. That doesn’t mean to say that October’s print is meaningless, a strong reading would reveal that the UK economy is falling this month from a stronger position.
Vaccine trade
Those stocks which suffered the most during the pandemic, such as travel, aviation and hotel stocks are seen as those benefitting the most in this weeks’ vaccine inspired rally. Other beaten down areas of the market such as energy and banks have also been in favour as investors search for areas of value .The euphoria of Monday has certainly calmed considerably, particularly given the very difficult few months that need to be navigated through first before any covid vaccination becomes widely available, hopefully by the spring.
Those stocks which suffered the most during the pandemic, such as travel, aviation and hotel stocks are seen as those benefitting the most in this weeks’ vaccine inspired rally. Other beaten down areas of the market such as energy and banks have also been in favour as investors search for areas of value .The euphoria of Monday has certainly calmed considerably, particularly given the very difficult few months that need to be navigated through first before any covid vaccination becomes widely available, hopefully by the spring.
Divergences in Europe
Equities in the UK, France and Spain are once again looking to outperform the Dax. This could be because these are the countries which have been hardest hit by the pandemic with higher mortalities and a bigger hit to the economy – therefore they stand to gain more from a vaccine. The other point to consider is that the Dax had already put in an impressive run up from its mid-March lows, outperforming other EU indices to trade almost at pre-pandemic levels even prior to the vaccine announcement.
In an otherwise quiet day on the economic calendar, investors will be looking towards a speech by ECB President Christine Lagarde for clues over the economic outlook for the region particularly following the vaccine news and the prospects of stimulus.
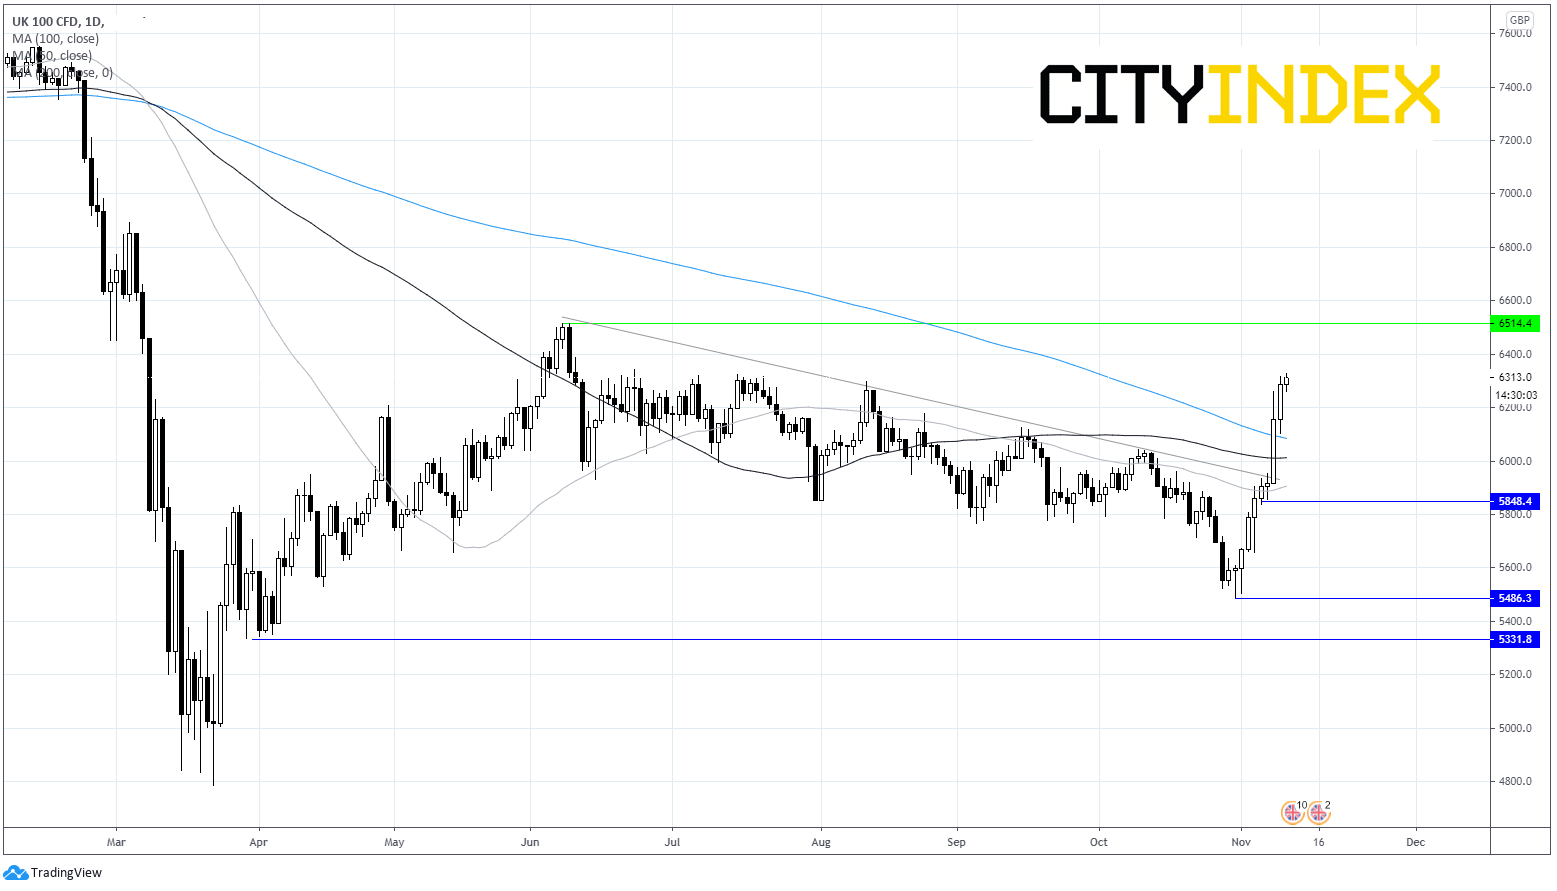
FTSE chart
Wall Street closed mixed with a significant divergence between old world stock and tech stock as investors continue to price in the Pfizer vaccine news and a return to “normal” life. The rotation from tech stocks into value stocks in response to a vaccine coming is driving market moves. The Dow closed 0.9% higher, whilst the tech heavy Nasdaq closed -1.3% in the red.
Faster global economic recovery
European stocks are pointing to a firmer start still buoyed by the game changing vaccine news from earlier in the week. In light of Pfizer’s announcement that its vaccine was found to be 90% effective, expectations are now for the global economy to recover considerably more quickly. Goldman Sachs is predicting US growth will be back to pre-pandemic levels by Q2 of 2021. Expectations for UK growth is , in some cases equally optimistic, and the UK could also return to pre-pandemic growth levels potentially as soon as mid-2021.
European stocks are pointing to a firmer start still buoyed by the game changing vaccine news from earlier in the week. In light of Pfizer’s announcement that its vaccine was found to be 90% effective, expectations are now for the global economy to recover considerably more quickly. Goldman Sachs is predicting US growth will be back to pre-pandemic levels by Q2 of 2021. Expectations for UK growth is , in some cases equally optimistic, and the UK could also return to pre-pandemic growth levels potentially as soon as mid-2021.
UK NIESR GDP data
The UK NIESR GDP reading for the three months to October is expected to show that momentum in the British economy kept building through Autumn, up 20.1% , compared to 15.2% in the 3 months to September. However, with lockdown 2.0 now in full swing November is expected to show a sharp fall. That doesn’t mean to say that October’s print is meaningless, a strong reading would reveal that the UK economy is falling this month from a stronger position.
The UK NIESR GDP reading for the three months to October is expected to show that momentum in the British economy kept building through Autumn, up 20.1% , compared to 15.2% in the 3 months to September. However, with lockdown 2.0 now in full swing November is expected to show a sharp fall. That doesn’t mean to say that October’s print is meaningless, a strong reading would reveal that the UK economy is falling this month from a stronger position.
Vaccine trade
Those stocks which suffered the most during the pandemic, such as travel, aviation and hotel stocks are seen as those benefitting the most in this weeks’ vaccine inspired rally. Other beaten down areas of the market such as energy and banks have also been in favour as investors search for areas of value .The euphoria of Monday has certainly calmed considerably, particularly given the very difficult few months that need to be navigated through first before any covid vaccination becomes widely available, hopefully by the spring.
Those stocks which suffered the most during the pandemic, such as travel, aviation and hotel stocks are seen as those benefitting the most in this weeks’ vaccine inspired rally. Other beaten down areas of the market such as energy and banks have also been in favour as investors search for areas of value .The euphoria of Monday has certainly calmed considerably, particularly given the very difficult few months that need to be navigated through first before any covid vaccination becomes widely available, hopefully by the spring.
Divergences in Europe
Equities in the UK, France and Spain are once again looking to outperform the Dax. This could be because these are the countries which have been hardest hit by the pandemic with higher mortalities and a bigger hit to the economy – therefore they stand to gain more from a vaccine. The other point to consider is that the Dax had already put in an impressive run up from its mid-March lows, outperforming other EU indices to trade almost at pre-pandemic levels even prior to the vaccine announcement.
In an otherwise quiet day on the economic calendar, investors will be looking towards a speech by ECB President Christine Lagarde for clues over the economic outlook for the region particularly following the vaccine news and the prospects of stimulus.
FTSE chart
Related tags:
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD, FTSE 100 Forecast: Two trades to watch 1507
EUR/USD rises after weaker US CPI, PPI up next. FTSE 100 falls as weak China GDP data hits miners.

FTSE 100, USD/JPY Forecast: Two trades to watch
FTSE eases modestly despite inflation unexpectedly holding steady. USD/JPY drifts lower ahead of the FOMC rate decision.
EUR/USD, FTSE 100 Forecast: Two trades to watch 21-05-26
EUR/USD slips below 1.16 as weak eurozone data weighs on sentiment. FTSE 100 slips as oil prices rebound and caution returns.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.