



Europe Steady as Fed, BoE, and Earnings Ahead
Markets open cautiously as Eurozone inflation stays firm, limiting ECB flexibility. Focus shifts to a busy week of central bank decisions, with the Fed on Wednesday and the BoE on Thursday. U.S. NFP beat forecasts, but growth signals remain mixed. Crude oil dips, silver gains, and earnings from Uber, Disney, and Shopify are on this week. Stay alert as central bank guidance and macro data define the path for global markets.
Share this:

Weekly – Europe Forecast | 5 May 2025
🇺🇸 US Labor Market & Economy
- April NFP: +177,000 jobs (above expectations by ~40K), but prior months revised down by 58K.
- Unemployment steady at 4.2%, labor force participation ticked up to 62.6%.
- Wages: +0.2% MoM / +3.8% YoY (both slightly below expectations).
- Result: Fed rate cut bets slightly reduced, pushing yields, USD, and equities higher.
- ISM Manufacturing PMI: down to 48.7, remains in contraction. Export orders and production weakened.
- Persistent economic uncertainty is pressuring margins and slowing growth.
📉 Markets Recap (April)
- S&P 500 saw large swings:
- -5th biggest 2-day drop since 1945 after April 2 tariffs.
- +9.5% rally on April 9 after tariff pause – biggest since 2008.
- Finished April down just 0.7%.
- USD Index fell 7.6% (Mar–Apr), largest 2-month drop since 2002.
- Gold: Strongest yearly start since 2006.
- Oil (Brent/WTI): -15%+ amid demand fears.
- Late April trade talk optimism boosted risk appetite modestly.
🇪🇺 Eurozone Inflation & Labor
- Headline inflation: Held at 2.2% YoY, vs expectations for a decline.
- Core inflation: Rose to 2.7% (from 2.4%), driven by services inflation (+3.9% YoY).
- Unemployment rate: Steady at 6.2%, a record low.
- Implication: Rising wage pressures could limit ECB rate cuts beyond the one priced for June.
- Bond yields in the eurozone rose; EUR firmed slightly.
DE – DAX 4H Technical Analysis
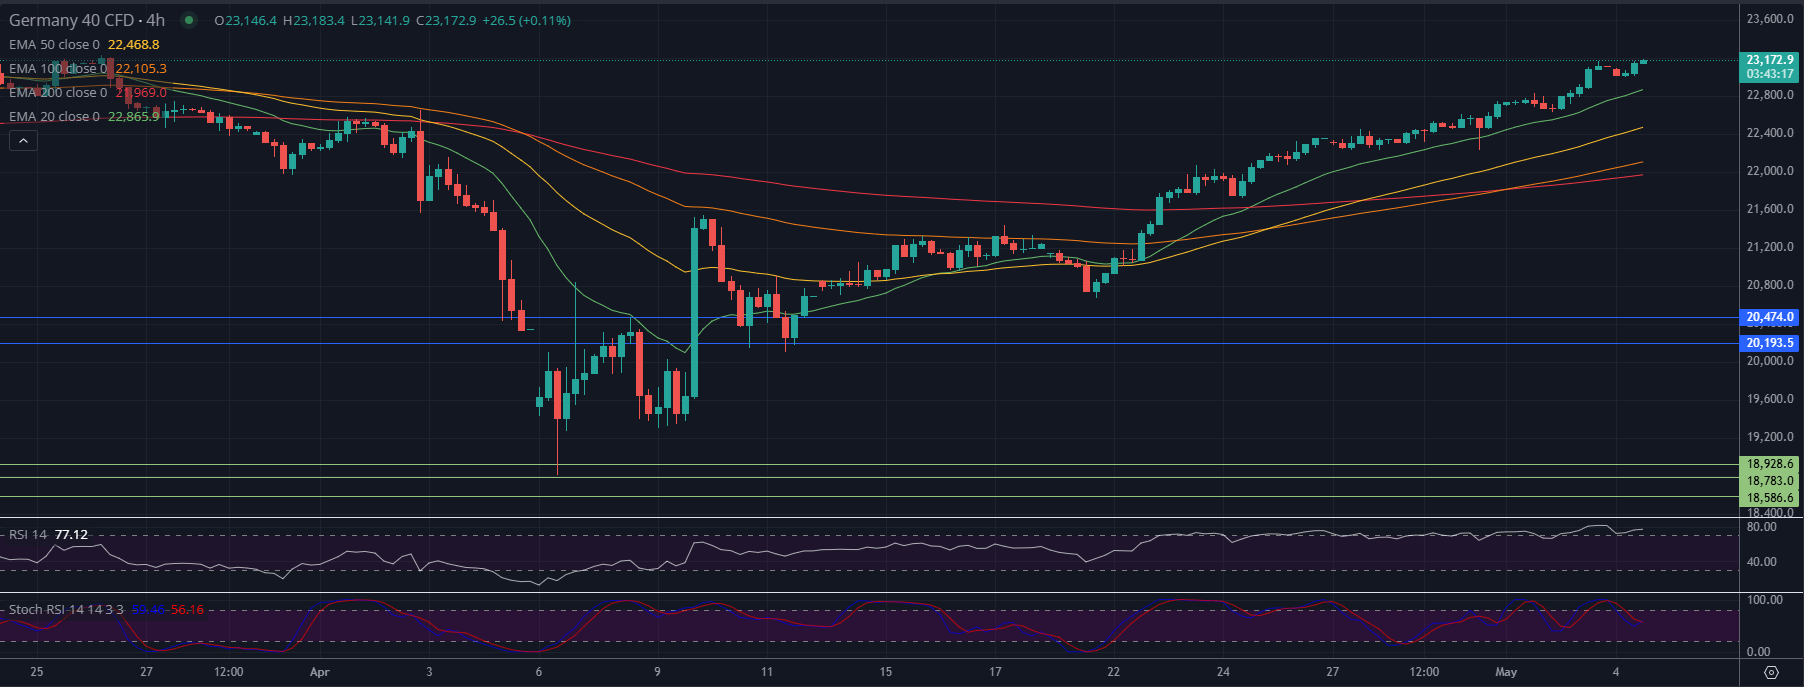
The Germany 40 (DAX)– 4H chart shows the index trading at 23,172.9 (+0.11%), pressing into a key resistance zone near previous swing highs from early March. The rally from the April lows has been sharp and well-structured, with price now at a critical decision point.
🔍 Technical Breakdown:
- EMA Alignment:
- Price remains well above all major EMAs (20/50/100/200), showing strong trend momentum.
- All EMAs are now in a bullish sequence (20 > 50 > 100 > 200), supporting continued upside unless broken.
- Momentum Indicators:
- RSI is at 77.12 — firmly in overbought territory, which doesn't imply reversal, but warns of potential consolidation.
- Stochastic RSI is also cooling from overbought levels (crossing down), reinforcing the idea that the rally might be pausing.
📌 Key Levels:
Resistance:
- 🔴 23,200–23,300 → Key resistance from the March breakdown; current area of interest
- 🔺 Breakout above this could open the door to 23,500+
Support:
- 🟢 22,865 (20 EMA) → First intraday dynamic support
- 🟠 22,468 (50 EMA) → Next major support level if momentum fades
- 🔵 20,474 → Structural pivot and key zone from April breakout
⚠️ Outlook:
The DAX is still strongly bullish, but short-term indicators suggest upside may be temporarily stretched. If price fails to break cleanly above 23,200–23,300, expect a healthy pullback toward 22,800–22,500 to refresh momentum.
📈 Bias: Bullish, but cautious at resistance. Watch for breakout above 23,300 or rejection/pullback into EMA support.
🌐 This Week’s Calendar Highlights
Monday
- Quiet start due to holiday closures.
- Data: Swiss CPI, US ISM Services PMI.
- Palantir earnings after market.
Tuesday
- Calm day; watch for SNB Chair Schlegel (London session) and Canada Ivey PMI.
- AMD & Electronic Arts earnings after market.
Wednesday
- Busy day:
- NZ employment (early Asia),
- UK Construction PMI,
- Fed rate decision – key event of the week.
- Earnings: Uber, Walt Disney (premarket).
Thursday
- Focus: Bank of England rate cut expected.
- US Weekly Jobless Claims also due.
- Earnings: Rheinmetall, Shopify, Coinbase.
Friday
- Speakers: BoE's Bailey, then multiple Fed officials (Kugler, Waller, Williams, etc.).
- Canada employment data released at NY open.
🔍 Asset Snapshot
- Asia equities opened soft (0% to -0.5%).
- EU indices slightly subdued.
- Silver +1%.
- Crude oil -3% at $56, pressured by OPEC+ output hikes and looming surplus.
Key Focus This Week
➡️ Fed rate decision (Wednesday)
➡️ Bank of England (Thursday)
➡️ Central bank speeches + earnings → tone for global markets.
Related tags:
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
RBA delivers 25bp hike, Bullock now the main event
The RBA delivered the expected 25bp hike, but Bullock’s press conference now looms as the bigger volatility risk for AUD/USD and the ASX 200.


Gold outlook: XAU/USD hammered, stretched and vulnerable to a sharp rebound
Gold is getting hammered for solid fundamental reasons, but history suggests extreme four-hourly oversold conditions can produce violent countertrend rallies.

EUR/USD, USD/JPY Outlook: Oil, yields and an FX identity crisis
Crude oil is setting the tone across rates and FX, leaving EUR/USD vulnerable and USD/JPY caught between higher Treasury yields and the growing threat of intervention
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.