


Gold: make-or-break week for USD as short-dated yields test fresh highs
A pivotal week for interest rates and the sustainability of the US dollar rally.
Share this:

This week looms as a pivotal moment for the US rates and dollar outlook with 2-year US Treasury yields testing cyclical highs into a busy calendar laden with top-tier economic releases. Given the influence short-dated rate differentials play in determining FX valuations, whether 2-year yields can push higher will likely make-or-break the prospects for a sustained US dollar rally in the absence of a ‘Black swan’ event.
US 2-year yields testing fresh cyclical highs
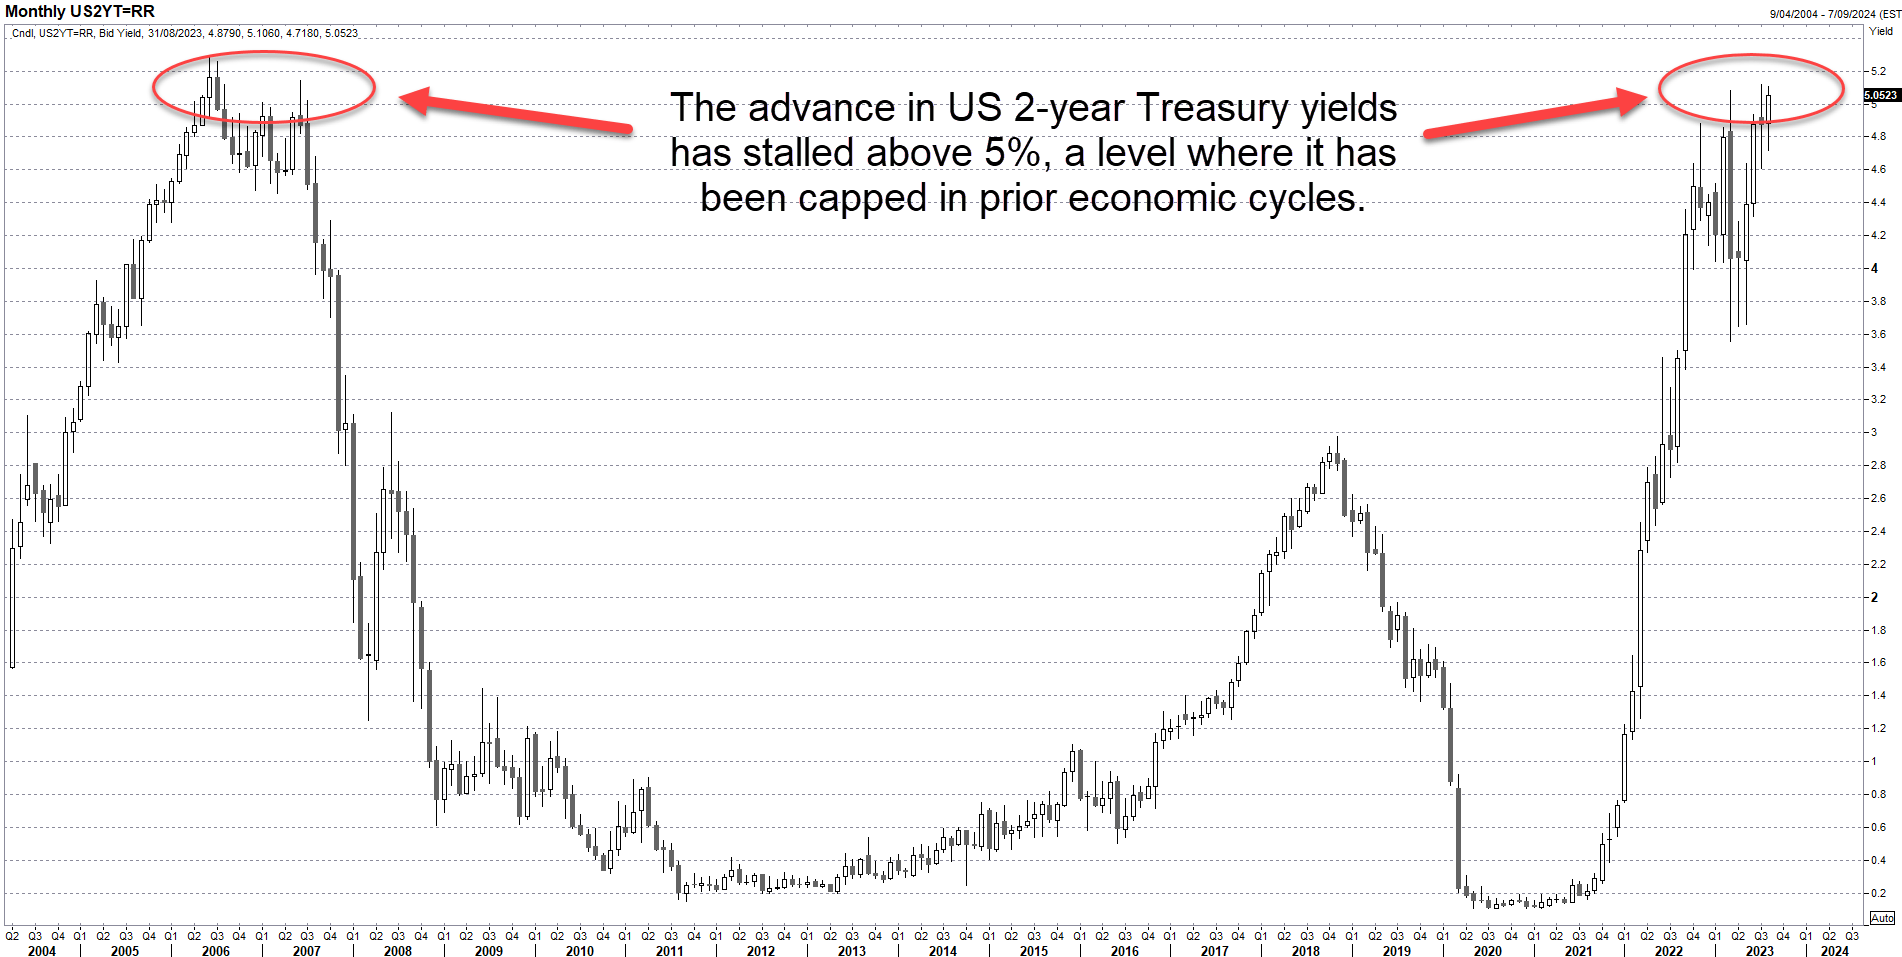
The monthly chart below shows that after the rapid increase coming out of the pandemic, US 2-year yields have stalled above 5%, trying and failing on multiple occasions to sustain a push to fresh multi-decade highs.
Make-or-break week for the US dollar
While the economic backdrop appears vastly different compared to 16-years ago, the willingness of investors to purchase shorter-dated Treasuries above 5% is similar what was seen before the GFC. The question is whether that will continue? Because whatever the answer, it will have ramifications for a variety of asset classes, especially those priced in or against the US dollar.
Market is positioned for higher short-term yields
As pointed out by my colleague Matt Simpson, net short exposure in US 2-year note futures sits at the highest level on record, according to latest data from the CME Commitment of Traders’ (COT) report. While that does not mean short exposure can’t increase further, adding to upside risks for yields, it suggests expectations for US rates to remain ‘higher for longer’ is largely factored in. Markets are priced for a soft economic landing, characterised by ongoing labour market strength and the risk of inflationary pressures reemerging.
Path of least resistance for yields now lower?
But what will happen if the consensus view were to suddenly change? Predicting such outcomes is difficult but we may have received a small taste last week following the release of the S&P Global US composite flash PMI report for August.
Without passing comment on whether it’s justified, few will argue this report rarely receives attention, especially given the reliable historical track record of the rival Institute of Supply Management (ISM) PMI report. But on this occasion, it caused an unusually large market reaction after reporting softening activity at US private sector firms. US Treasury yields and dollar fell sharply on a release that’s usually ignored. While the moves were reversed quickly, it would have been interesting to see whether that would have occurred without Fed Chair Jerome Powell speaking less than 24 hours after.
It reinforces why this week could be crucial for the USD. 2-year yields are testing fresh highs, with record short interest, heading into non-farm payrolls and core PCE inflation. Based on price action and trader positioning, it appears the path of least resistance for shorter-dated yields may shifting from the upside to downside. That’s important for assets worldwide, especially those highly influenced by the US dollar and interest rate fluctuations. Commodities stand out, especially gold.
Gold worth watching
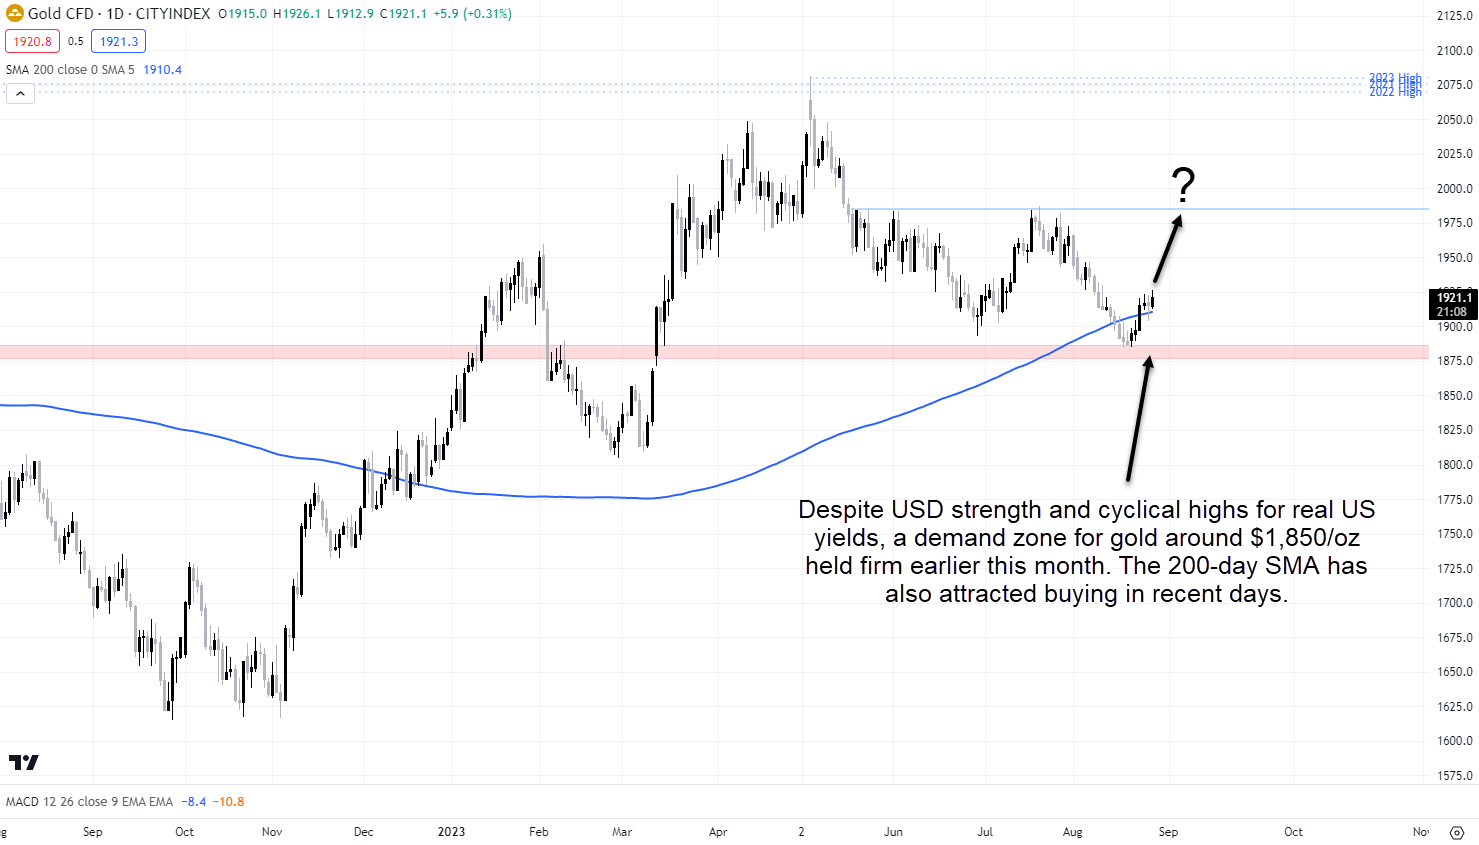
Even with the strengthening dollar and fresh cyclical peaks for US yields across several durations, gold prices hung tough earlier this month, repeatedly finding bids at the top of a demand zone located around $1,850/oz. More recently, probes below the 200-day MA have also been bought.
Given the resilient price action, any renewed declines in the US dollar and bond yields may act to push the gold back towards resistance located around $1885/oz. A break of that level could potentially open the way for a retest of the multiple multi-decade highs located above $2,050/oz. On the downside, minor resistance is found around $1,900/oz and $1,894/oz before the larger support zone kicks in.
Outside of bullion, currencies that have underperformed recently against the US dollar, such as the Japanese yen, Chinese yuan, Australia and New Zealand dollars, may also experience outsized moves to a recalibration of US interest rate expectations.
-- Written by David Scutt
Follow David on Twitter @scutty
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Gold outlook: XAU/USD hammered, stretched and vulnerable to a sharp rebound
Gold is getting hammered for solid fundamental reasons, but history suggests extreme four-hourly oversold conditions can produce violent countertrend rallies.
EUR/USD, USD/JPY Outlook: Oil, yields and an FX identity crisis
Crude oil is setting the tone across rates and FX, leaving EUR/USD vulnerable and USD/JPY caught between higher Treasury yields and the growing threat of intervention

Gold Outlook: XAU/USD hit hard as US yields, dollar resume ascent
A stronger dollar, surging front-end yields and renewed geopolitical tension have combined to push gold back towards key technical support.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.