





Market Brief Antipodeans Drive FX Volatility Again
A summary of news and snapshot of moves from today’s Asia session.
Share this:

View our guide on how to interpret the FX Dashboard
FX Brief:
- It was another volatile session courtesy of the Antipodeans, with Australian employment missing the mark and sending AUD broadly lower. Whilst unemployment rose to 5.3% as expected, it was employment growth contracting for the first time since September 2016 (with fulltime employment also falling) which made its presence known.
- And that was before weak Chinese data. Retail sales fell to 7.2% YoY (7.8% prior and 7.9% expected), industrial output fell to 4.7% YoY (5.8% prior, 5.4% expected) and investments fell to 5.2% (5.4% prior and expected).
- RBNZ’s deputy governor spoke earlier in the session, stating they made a call to “bide our time for now” on interest rates, but RBNZ could move rates in February if they needed to.
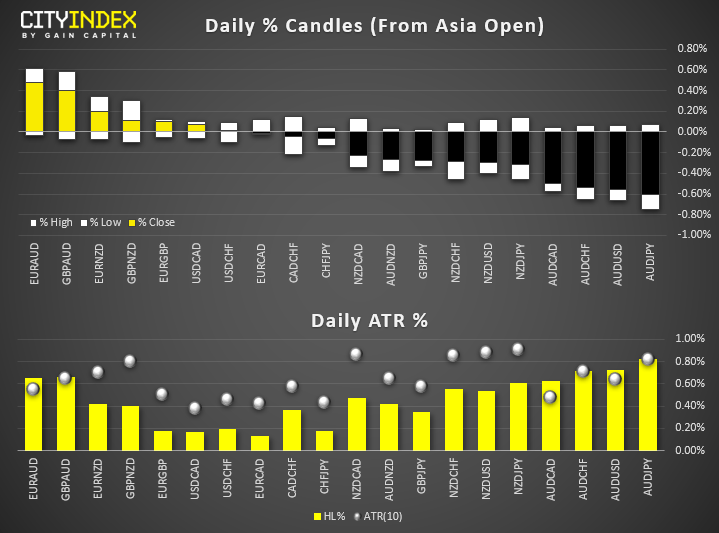
- AUD and NZD are the weakest majors (in that order) and the yen was slightly bid on further trade doubts. NZD/CAD has retreated from yesterday’s high but we’re keeping a close eye on 0.8500 for a potential trend reversal. AUD/USD is below 68c after breaking out of its corrective channel, AUD/NZD fell to a 10-weel low.
- Volatility was higher than usual in Asia today, with the average daily rage to ATR sitting at 69%. Yet six AUD pairs exceeded their AR following weak employment and Chinese data.

Equity Brief:
- Cautious trading mood continue to reign in today’s Asian session where traders continue to monitor the on-going anti- government demonstrations in Hong Kong that are not showing at signs of abating at this juncture. Also, key economic data releases out from China, Japan and Australia have remined traders that the global economy remains fragile.
- China’s retail sales and industrial output growth for Oct has slowed down more than expected (retail sales; 7.2% y/y vs consensus of 7.9% y/y & industrial output; 4.7% y/y vs consensus of 5.4% y/y) which indicates that the current piecemeal stimulus programmes from Chinese policy makers are not gaining much traction to boast economic activities.
- Japan’s preliminary Q3 GDP came in at 0.2% y/y below consensus of 0.8% y/y, down sharply from a revised Q2 reading of 1.8% y/y. Meanwhile, Australia’s jobs data for Oct painted a sombre picture as it shed jobs for the first time in 17 months with employment change at -19K versus consensus of +15K.
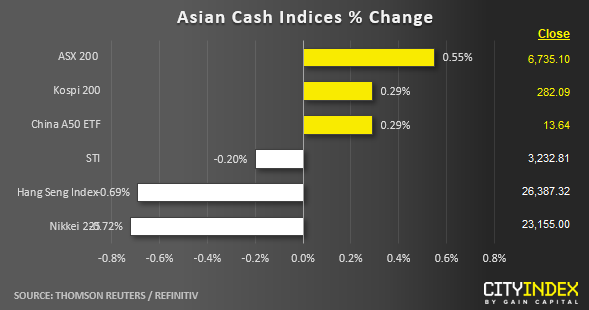
- Hong Kong’s Hang Seng Index has continued to be the worst performer for the 4th consecutive session where it has dropped by around -0.70% so far reinforced by a plunge of -2.10% seen in Tencent Holdings, the 2nd largest component stock in the HSI after its Q3 earnings missed estimates with a -13% y/y decline in net profits (CNY 20.4 billion vs consensus of CNY 23.5 billion).
- Australia’s ASX 200 has managed to shrug off the negative sentiment arising from the weak AU employment data to record a gain of 0.55% led by technology and healthcare related stocks where Afterpay Touch has soared by 7.5% after an announcement of A$200 million subscription by U.S. based Coatue Management and a 110% increase in its global sales for 4 months ended 31 Oct. Another tech stock, Nearmap also posted a stellar gain of 14% after an upbeat outlook for 2020.
Matt Simpson and Kelvin Wong both contributed to this article
Data from Refinitiv. Index names may not reflect tradable instruments and not all markets are available in all regions.
View our guide on how to interpret the FX Dashboard
FX Brief:
- It was another volatile session courtesy of the Antipodeans, with Australian employment missing the mark and sending AUD broadly lower. Whilst unemployment rose to 5.3% as expected, it was employment growth contracting for the first time since September 2016 (with fulltime employment also falling) which made its presence known.
- And that was before weak Chinese data. Retail sales fell to 7.2% YoY (7.8% prior and 7.9% expected), industrial output fell to 4.7% YoY (5.8% prior, 5.4% expected) and investments fell to 5.2% (5.4% prior and expected).
- RBNZ’s deputy governor spoke earlier in the session, stating they made a call to “bide our time for now” on interest rates, but RBNZ could move rates in February if they needed to.
- AUD and NZD are the weakest majors (in that order) and the yen was slightly bid on further trade doubts. NZD/CAD has retreated from yesterday’s high but we’re keeping a close eye on 0.8500 for a potential trend reversal. AUD/USD is below 68c after breaking out of its corrective channel, AUD/NZD fell to a 10-weel low.
- Volatility was higher than usual in Asia today, with the average daily rage to ATR sitting at 69%. Yet six AUD pairs exceeded their AR following weak employment and Chinese data.
Equity Brief:
- Cautious trading mood continue to reign in today’s Asian session where traders continue to monitor the on-going anti- government demonstrations in Hong Kong that are not showing at signs of abating at this juncture. Also, key economic data releases out from China, Japan and Australia have remined traders that the global economy remains fragile.
- China’s retail sales and industrial output growth for Oct has slowed down more than expected (retail sales; 7.2% y/y vs consensus of 7.9% y/y & industrial output; 4.7% y/y vs consensus of 5.4% y/y) which indicates that the current piecemeal stimulus programmes from Chinese policy makers are not gaining much traction to boast economic activities.
- Japan’s preliminary Q3 GDP came in at 0.2% y/y below consensus of 0.8% y/y, down sharply from a revised Q2 reading of 1.8% y/y. Meanwhile, Australia’s jobs data for Oct painted a sombre picture as it shed jobs for the first time in 17 months with employment change at -19K versus consensus of +15K.
- Hong Kong’s Hang Seng Index has continued to be the worst performer for the 4th consecutive session where it has dropped by around -0.70% so far reinforced by a plunge of -2.10% seen in Tencent Holdings, the 2nd largest component stock in the HSI after its Q3 earnings missed estimates with a -13% y/y decline in net profits (CNY 20.4 billion vs consensus of CNY 23.5 billion).
- Australia’s ASX 200 has managed to shrug off the negative sentiment arising from the weak AU employment data to record a gain of 0.55% led by technology and healthcare related stocks where Afterpay Touch has soared by 7.5% after an announcement of A$200 million subscription by U.S. based Coatue Management and a 110% increase in its global sales for 4 months ended 31 Oct. Another tech stock, Nearmap also posted a stellar gain of 14% after an upbeat outlook for 2020.
Matt Simpson and Kelvin Wong both contributed to this article
Data from Refinitiv. Index names may not reflect tradable instruments and not all markets are available in all regions.Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.
AUD/USD Q4 Outlook: RBA and Fed Hikes Set the Tone
AUD/USD enters Q4 with RBA and Fed hikes in focus as sticky inflation, rising unemployment and US dollar strength shape the Australian dollar.

USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.