





Market Brief Contrasting Headlines Whip Prices
A summary of news and snapshot of moves from today’s Asia session.
Share this:

FX Brief:
- We saw a few whipsaws on price action today as contrasting headlines on trade talks rolled in. Rumours that China may leave this week’s trade talks early were recirculated in the South China Morning Post, which the US went on to deny (not sure why they’d know if true though…). And then reports surfaced that the US were going to suggest a currency pact with China, in which China are not to interfere with their currency (takes two to tango…) and the US were going to lighten restrictions on some US companies selling to Huawei.
Japan’s machinery orders, a measure for business investment, fell at its fastest rate since 2009 at -14.5% YoY. This only increases the odds of BOJ to ease at their next meeting. - A similar pattern has emerged with AUD and NZD taking the lead among FX majors, with JPY being the weakest currency. This has seen AUD/JPY an NZD/JPR far exceed their typical daily ranges, so momentum traders may want to look elsewhere for intraday trends and focus on pairs which have potential meat on the bone.
Equity Brief:
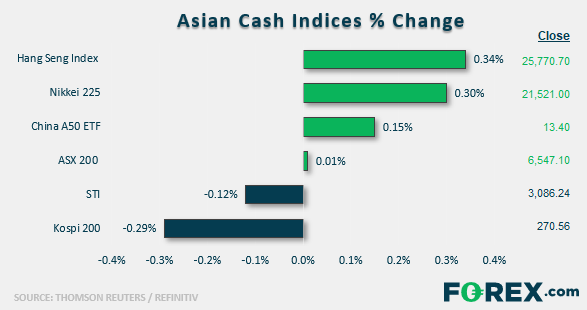
- Mix performances seen in key Asian stock markets ahead of the high-level U.S-China trade talk that is set to kick-start today in Washington. Also, contrasting trade related headlines out in Asian session today do not offer any clear direction on how the talks will progress. On the positive side, it has been reported that U.S. administration is considering a currency pact with China that could lead to a partial deal. On the negative flipside, deputy-level talks among junior trade officials have shown no progress ahead of today’s key negotiation talk and the Chinese trade delegation may leave earlier today rather than stay for the scheduled two days of talks till Fri, 11 Oct.
- South Korea’s Kospi 200 is the worst performer today which has recorded a loss of -0.30% to hit a month low of 266 as it resumed trading from yesterday’s holiday break
- Cautious trading has continued to be seen in Hong Kong stock market as anti-government protestors have indicated to plan more protests today and over the weekend. Property related stocks have underperformed where Henderson Land, Hang Lung Properties and Sun Hung Kai Properties have dropped by -0.90% to -0.80%.
Up Next
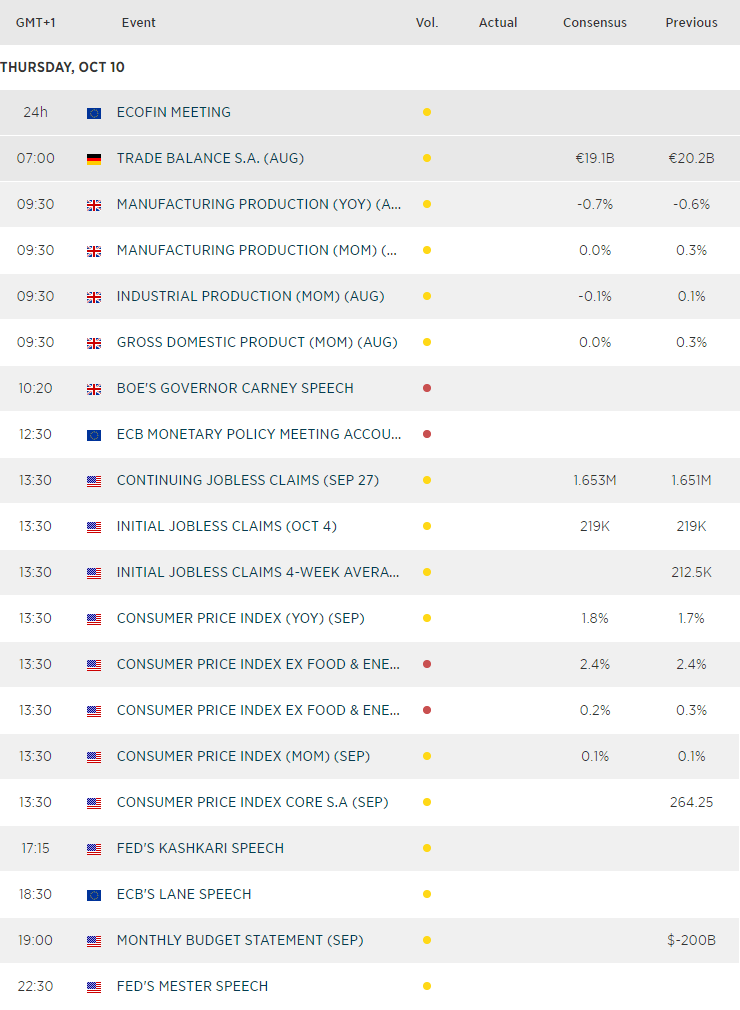
- A slew of data from UK includes monthly GDP, manufacturing, industrial and construction output. Mark Carney is also speaking, although it’s about the new £20 note so we doubt it will be riveting. Unless we see surprisingly strong rebounds on the data front, Brexit headlines remain the dominant driver behind GBP moves.
- US inflation data is expected to remain at 2.4%, well above the Fed’s 2% target. A slight miss below this figure increase the already high odds that they’ll cut next week (which is around 85% according to the CME FedWatch tool).
Matt Simpson and Kelvin Wong contributed to this article
Data from Refinitiv. Index names may not reflect tradable instruments and not all markets are available in all regions.
FX Brief:
- We saw a few whipsaws on price action today as contrasting headlines on trade talks rolled in. Rumours that China may leave this week’s trade talks early were recirculated in the South China Morning Post, which the US went on to deny (not sure why they’d know if true though…). And then reports surfaced that the US were going to suggest a currency pact with China, in which China are not to interfere with their currency (takes two to tango…) and the US were going to lighten restrictions on some US companies selling to Huawei.
Japan’s machinery orders, a measure for business investment, fell at its fastest rate since 2009 at -14.5% YoY. This only increases the odds of BOJ to ease at their next meeting. - A similar pattern has emerged with AUD and NZD taking the lead among FX majors, with JPY being the weakest currency. This has seen AUD/JPY an NZD/JPR far exceed their typical daily ranges, so momentum traders may want to look elsewhere for intraday trends and focus on pairs which have potential meat on the bone.
Equity Brief:
- Mix performances seen in key Asian stock markets ahead of the high-level U.S-China trade talk that is set to kick-start today in Washington. Also, contrasting trade related headlines out in Asian session today do not offer any clear direction on how the talks will progress. On the positive side, it has been reported that U.S. administration is considering a currency pact with China that could lead to a partial deal. On the negative flipside, deputy-level talks among junior trade officials have shown no progress ahead of today’s key negotiation talk and the Chinese trade delegation may leave earlier today rather than stay for the scheduled two days of talks till Fri, 11 Oct.
- South Korea’s Kospi 200 is the worst performer today which has recorded a loss of -0.30% to hit a month low of 266 as it resumed trading from yesterday’s holiday break
- Cautious trading has continued to be seen in Hong Kong stock market as anti-government protestors have indicated to plan more protests today and over the weekend. Property related stocks have underperformed where Henderson Land, Hang Lung Properties and Sun Hung Kai Properties have dropped by -0.90% to -0.80%.
Up Next
- A slew of data from UK includes monthly GDP, manufacturing, industrial and construction output. Mark Carney is also speaking, although it’s about the new £20 note so we doubt it will be riveting. Unless we see surprisingly strong rebounds on the data front, Brexit headlines remain the dominant driver behind GBP moves.
- US inflation data is expected to remain at 2.4%, well above the Fed’s 2% target. A slight miss below this figure increase the already high odds that they’ll cut next week (which is around 85% according to the CME FedWatch tool).
Matt Simpson and Kelvin Wong contributed to this article
Data from Refinitiv. Index names may not reflect tradable instruments and not all markets are available in all regions.Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Japanese Yen Outlook: USD/JPY, GBP/JPY, AUD/JPY Setups
USD/JPY and GBP/JPY show signs of stabilising, while AUD/JPY remains vulnerable as yen crosses deliver mixed technical signals.
EUR/USD Forecast: Euro Struggles to Find Support Even After U.S. PCE Data
The euro continues to face a challenging environment in the short term. The currency has struggled to regain ground against a U.S. dollar that remains firmly supported, a dynamic reflected in EUR/USD, which has now recorded three consecutive losing sessions and a decline of roughly 0.6%.

Canadian Dollar Forecast: USD/CAD Four-Week Rally Eyes Yearly Highs 9 30 2026
USD/CAD has advanced in 14 of the past 15 sessions, but stretched momentum raises the stakes as major resistance and NFP come into focus.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.